


Why V.F (VFC) Is Back On Investors’ Radar
V.F (VFC) just delivered second quarter results with higher net income and earnings per share alongside softer sales, reaffirmed its 2027 earnings outlook, and kept its quarterly dividend in place.
That mix of stronger profitability, reaffirmed 2027 guidance and a maintained dividend has coincided with a sharp turn in sentiment toward V.F. The stock’s 30 day share price return of 41.52%, alongside a 42.16% 1 year total shareholder return but a 5 year total shareholder return that is down 68.67%, suggests powerful recent momentum following a much weaker long term stretch.
Scan beyond V.F and look for apparel and consumer brands showing similar earnings resilience and price momentum with our curated 19 high quality undiscovered gems.
The rebound in V.F has already pushed the share price slightly above the average analyst target, while some models still point to a sizeable intrinsic discount. Is the market now too cautious, or suddenly too optimistic on this turnaround story?
Most Popular Narrative: 4% Overvalued
V.F closed at $20.35 compared with a narrative fair value of $19.65, which suggests investors are already paying up for the recovery story while still wrestling with execution risk and leverage.
Elevated debt levels and higher leverage (currently over 4x, with a target of 2.5x by 2028) continue to constrain financial flexibility, making future investments in growth, innovation, or shareholder returns more challenging if cash flow improvements do not materialize as planned.
Industry wide inventory and wholesale demand caution, especially amid uncertain macroeconomic conditions and shifting fashion/lifestyle trends, amplify the risk of overstocking, forced discounting, and margin erosion, ultimately threatening profitability and future earnings power.
See why 49 investors see V.F as 4% overvalued.
Result: Fair Value of $19.65 (OVERVALUED)
Still, the V.F narrative can break if Vans continues to struggle for longer than expected or if elevated debt leaves less room to absorb any setback.
Find out about the key risks to this V.F narrative.
Another View On V.F’s Value
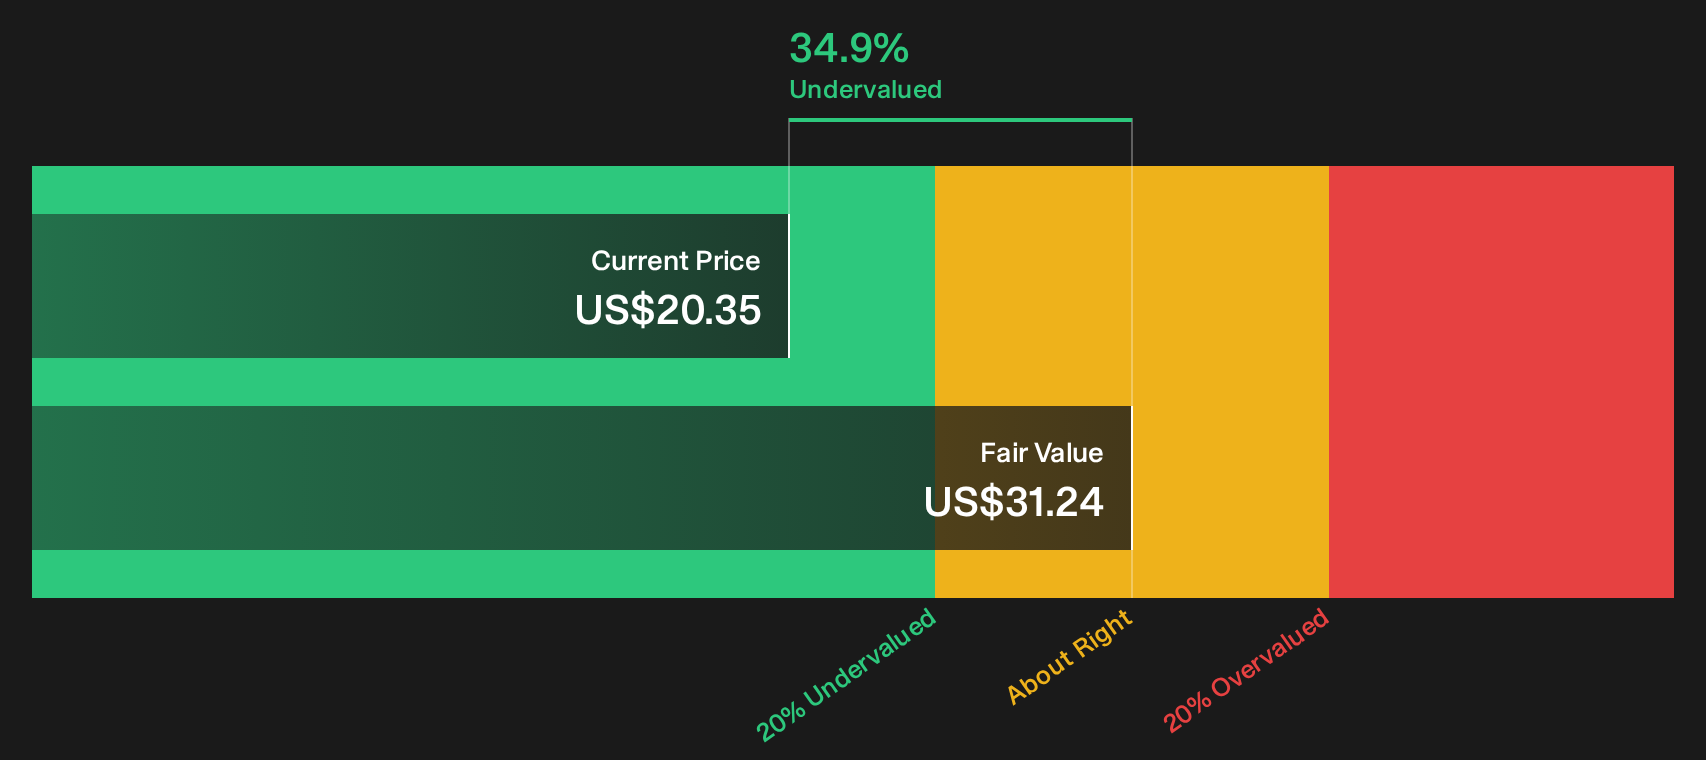
The narrative fair value for V.F sits at $19.65 and frames the stock as about 4% overvalued. A different lens tells a very different story. The SWS DCF model puts the future cash flow value closer to $31.24, which points to V.F trading at roughly a 35% discount instead.
If future cash flows come through anywhere near that DCF path, investors are not paying up for that scenario at $20.35. The question is whether the narrative risk focus or the cash flow outlook deserves more weight in your own process.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out V.F for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mix of risk and recovery around V.F feels finely balanced, act quickly, review the numbers in detail, and pressure test the trade-off yourself with 3 key rewards and 3 important warning signs.
Ready To Act On Your Next Idea Beyond V.F?
Do not stop with V.F. Use the Simply Wall St screener to uncover fresh ideas, compare risk profiles, and pressure test where your next dollar should go.
- Target potential mispricings and see which quality companies still trade at a discount with the 39 high quality undervalued stocks.
- Prioritize resilience and support more restful investing by focusing on businesses flagged in the 29 resilient stocks with low risk scores.
- Zero in on balance sheet strength and funding flexibility using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com