


Digi International (DGII) just rolled out the Digi EX61, a rugged indoor and outdoor 5G extender that leans into managed connectivity, AI driven oversight and recurring service focused offerings.
The launch of the new Digi EX61 comes against a mixed share price backdrop. The stock trades at US$63.21, with the 1 day share price return of 1.40% offering only a small uptick after a 7 day share price decline of 13.10% and a 30 day drop of 15.96%. Year to date, the share price return of 46.46% and a 1 year total shareholder return of 78.56% point to strong longer term momentum.
Scan for other connectivity and AI focused plays pacing alongside Digi International by reviewing the 52 AI infrastructure stocks that zeroes in on businesses building the networks behind next generation traffic and data.
The recent pullback in Digi International after a strong year long run leaves you choosing between leaning into the weakness now or waiting for a cleaner reset in the valuation work that follows.
Most Popular Narrative: 26% Undervalued
Digi International is priced at $63.21 while the most followed narrative anchors fair value at $85.40. The new EX61 launch therefore fits into a story that already assumes meaningful upside is justified by recurring revenue and acquisition execution.
The accelerating transition of customers to Digi International's subscription-based and recurring revenue solutions, with ARR growing faster than revenue and reaching $191 million in fiscal Q3 2026, continues to shift the mix toward higher margin software and services. This can support more stable revenue and stronger net margins over time.
See why 3 investors see Digi International as 26% undervalued.
Result: Fair Value of $85.40 (UNDERVALUED)
Still, the Digi International story can wobble if acquisition targets underdeliver on ARR, or if insider selling and rich P/E expectations reset sentiment quickly.
Find out about the key risks to this Digi International narrative.
Another View: What Digi International’s P/E Is Telling You
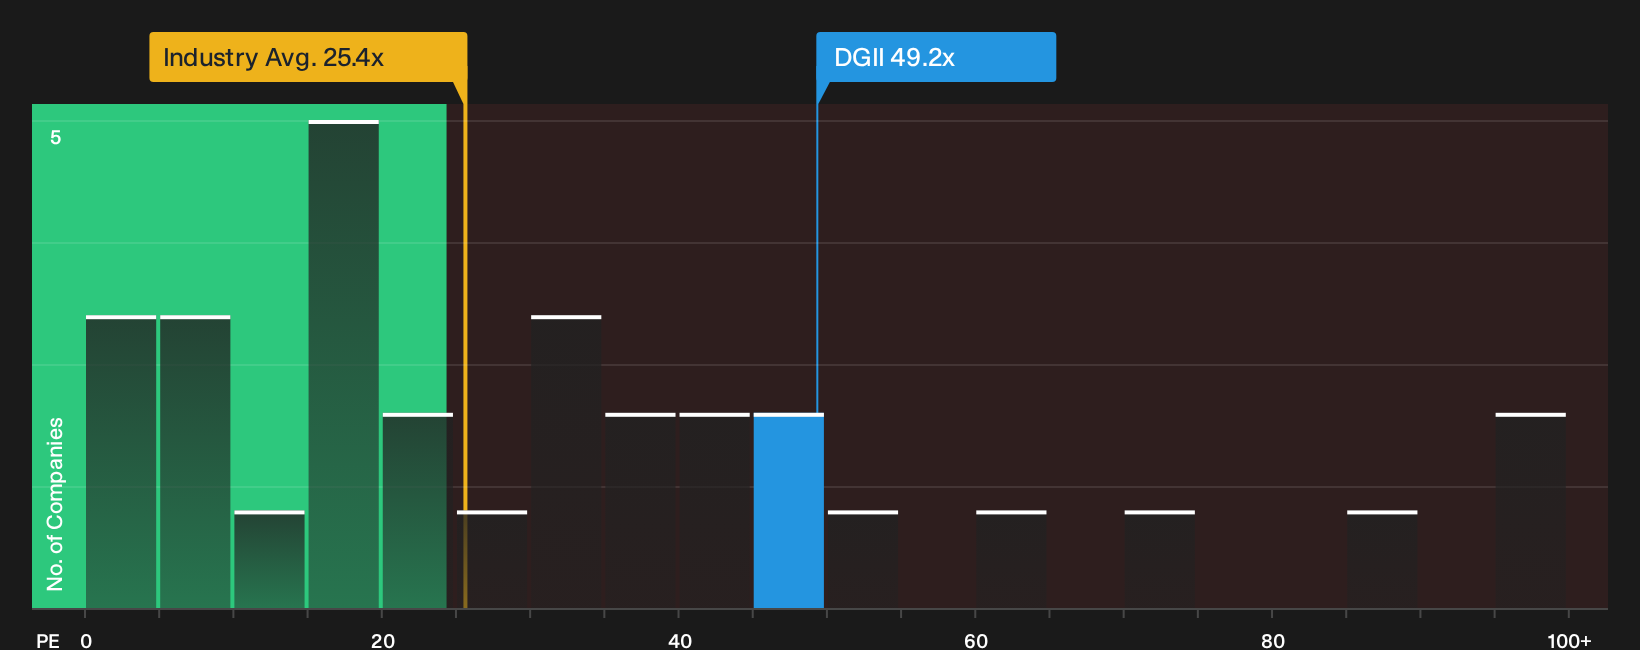
Digi International may screen as undervalued on cash flow work, yet the simple earnings multiple is flashing a very different message. The stock trades on a P/E of 49.2x, compared with 25.5x for the US Communications sector and a peer average of 33.6x. Our fair ratio sits even lower at 30.1x, which points to meaningful valuation risk if sentiment cools or growth assumptions get questioned.
For anyone weighing those signals side by side, the big question is which anchor you trust more when expectations are already this full.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between Digi International's recent pullback and its bullish fair value work is normal. Move quickly, pressure test the numbers yourself, and then weigh those 4 key rewards.
Looking for more investment ideas beyond Digi International?
If Digi International has your attention, do not stop there. Use the same disciplined lens across other opportunities and let the data surface ideas you might otherwise miss.
- Target resilient compounding potential by scanning a 39 high quality undervalued stocks that filters for quality businesses trading below their implied worth.
- Protect your downside first by running through a 29 resilient stocks with low risk scores that highlights companies with sturdier financial profiles and calmer risk scores.
- Get ahead of the crowd by reviewing a 19 high quality undiscovered gems that focuses on under the radar stocks backed by solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com