


Thermo Fisher Scientific has delivered a strong share price run in recent years, which puts a sharper spotlight on whether the cash the business can generate really lines up with where the stock now trades. With the spotlight also on new capital allocation moves, the question for investors is how well the current market value ties back to the company’s underlying cash flows.
- Over the past 3 years the stock has returned 56.4%, which raises the question of how much future cash generation is already reflected in that performance.
- The newly authorized US$5b share repurchase program may support per share cash flow metrics over time, since fewer shares can spread the same or higher level of cash generation across a smaller base.
- If you'd rather focus on earnings, this one's for you. See why Thermo Fisher Scientific's 36.4x P/E tells a different valuation story.
The issue now is whether Thermo Fisher Scientific’s current share price is adequately supported by its cash flows when assessed against an intrinsic value estimate built from a Discounted Cash Flow (DCF) model.
If you want to test the same cash flow question that surrounds Thermo Fisher Scientific across a wider opportunity set, scan through 39 high quality undervalued stocks.
Is Thermo Fisher Scientific Getting Expensive on Cash Flow?
The Discounted Cash Flow (DCF) approach used here takes Thermo Fisher Scientific’s forecast free cash generation and brings it back to today’s dollars. Latest twelve month free cash flow sits at about $7.7b, with the model assuming that cash flow grows over time into the low teens of billions of dollars by the early 2030s.
Those growing cash projections are set against a current share price of $694.76, and the DCF output indicates that the estimated intrinsic value comes out meaningfully below where the stock trades today. The newly authorized $5b share repurchase program can lift per share cash flow, yet the DCF result suggests the market is already placing a full value on Thermo Fisher Scientific’s projected cash generation at current levels. Find out what Thermo Fisher Scientific could be worth using our Discounted Cash Flow (DCF) estimate.
The Thermo Fisher Scientific Narrative: What Would Justify Today's Price?
Thermo Fisher Scientific’s Narratives on Simply Wall St pick up where the DCF question leaves off, by spelling out what kind of future for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Rather than lean on a single multiple or model number, each Narrative lays out the key levers behind its view of fair value so you can later compare those assumptions with the results the business actually reports.
Thermo Fisher Scientific splits the community, with one side seeing well supported upside and the other arguing expectations already look full.
Bull case: 7% undervalued
"Ongoing portfolio-deepening M&A, including the recent Clario and Solventum filtration deals that are tracking ahead of initial assumptions, is set to tilt the mix toward higher value segments..."
Discover why this Narrative puts Thermo Fisher Scientific at 7% undervalued.
Bear case: 8% overvalued
"Some analysts with a bearish view expect Thermo Fisher Scientific's margins and global growth to remain constrained, as the microbiology divestiture reduces earnings and academic and government spending stays muted..."
Explore why this Narrative puts Thermo Fisher Scientific at 8% overvalued.
One more Thermo Fisher Scientific check before you move on
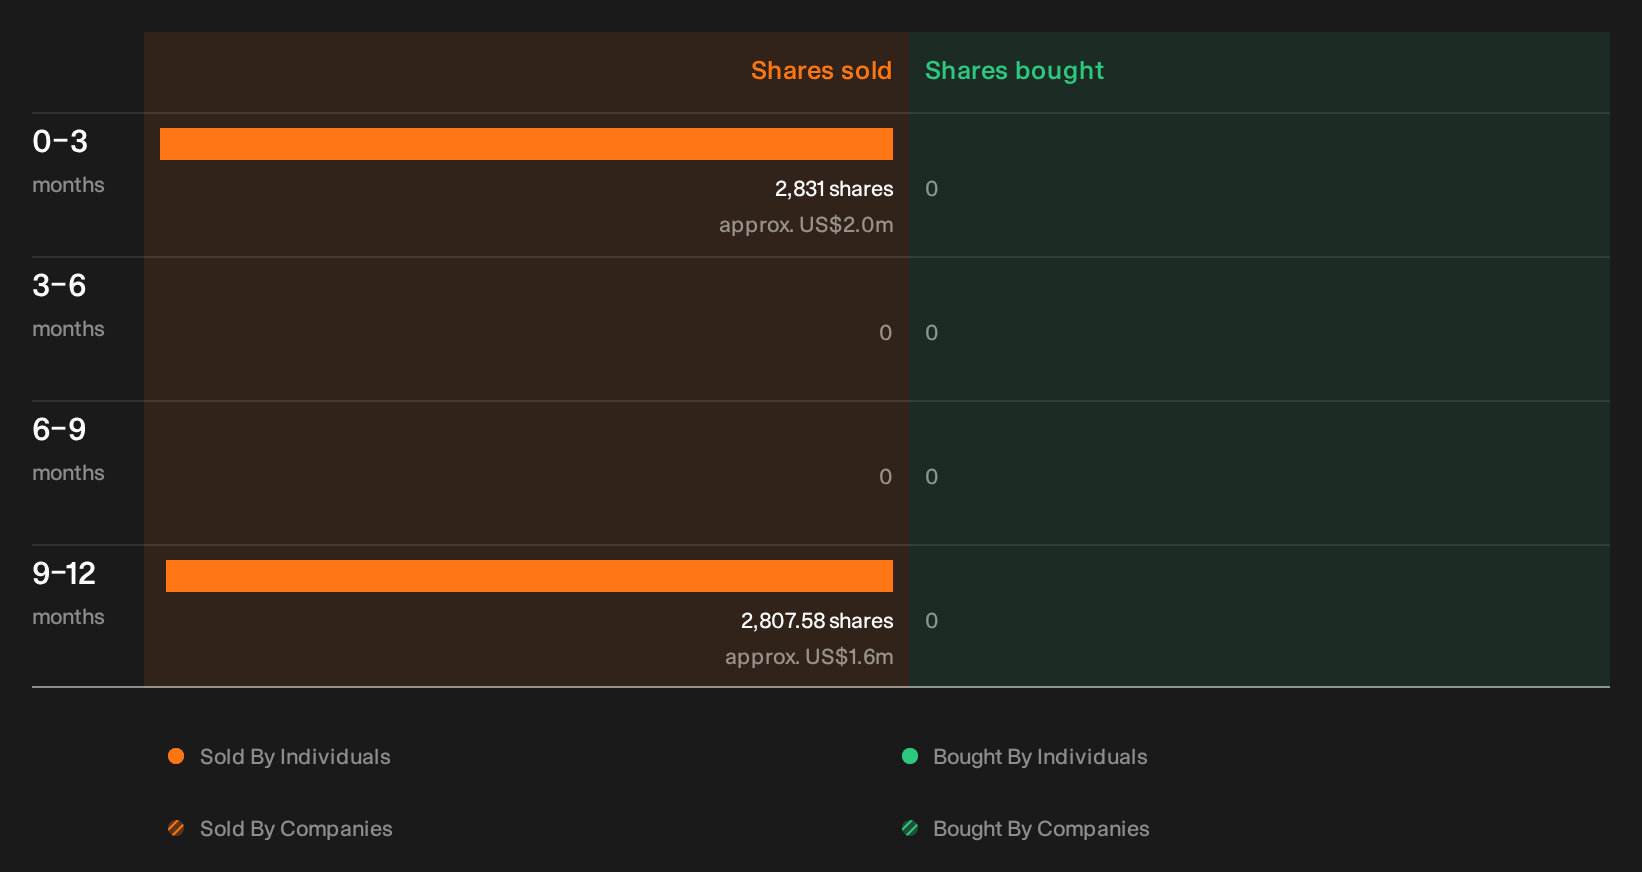
Price and cash flow only tell part of the story, since recent trading by people inside Thermo Fisher Scientific has also been flagged by our checks, and the specific sellers, sizes and possible read through are waiting for you to review. See the recent insider selling flagged for Thermo Fisher Scientific.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com