


Telephone and Data Systems has delivered a strong multiyear share price rise, which now raises a clear question for investors about whether the current valuation is adequately supported by its earnings power. After that kind of move, the issue is not just what the business is doing, but whether the profit stream behind the stock price justifies where it trades today.
- Over the past 5 years the stock has gained 90.3%, which puts real pressure on the earnings story to carry that kind of re rating.
- Management is pushing hard on fiber broadband expansion and Array Digital Infrastructure, which can reshape expectations for future profitability and the timing of cash flows that support Telephone and Data Systems' earnings base.
- There is a second opinion on Telephone and Data Systems worth weighing. See what analysts think Telephone and Data Systems's shares could be worth.
The stock's next move may depend on whether Telephone and Data Systems' current share price fairly reflects what its recent earnings say about the business.
If you are weighing Telephone and Data Systems against other earnings focused opportunities, it can help to compare it to companies viewed from the same perspective using 39 high quality undervalued stocks.
Does Telephone and Data Systems Look Pricey on Earnings?
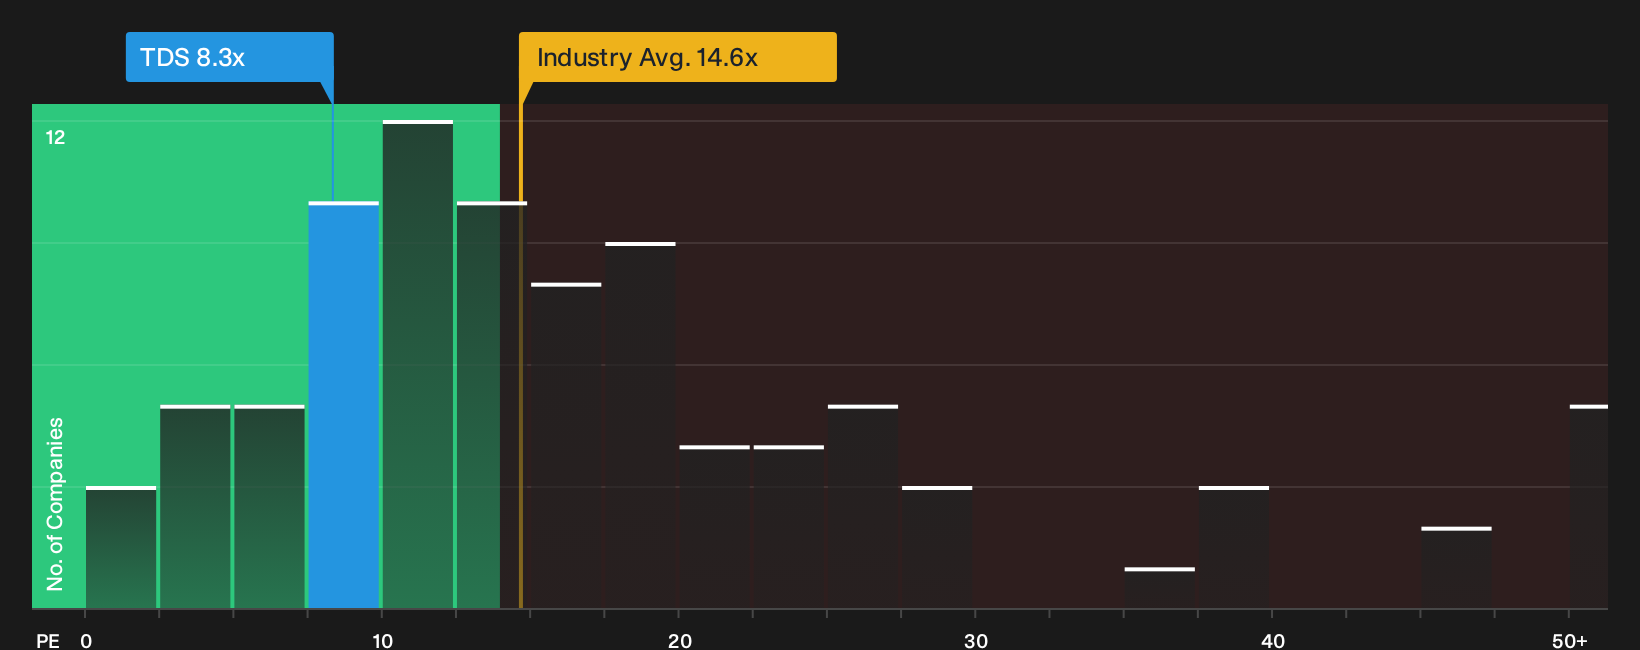
P/E works well for Telephone and Data Systems because earnings are the key reference point investors use for telecom style businesses. On this yardstick, the stock trades on a P/E of 8.3x, which is well below the Wireless Telecom industry average of 14.6x and also under the broader peer group on about 15.2x. That gap tells you the market is asking for a clear earnings proof point before it is willing to pay a sector level multiple for this ticker.
The Fair Ratio model, which adjusts the P/E you might expect for Telephone and Data Systems given its business mix, margins and risk profile, sits meaningfully below the current 8.3x figure, so the shares screen as overvalued on this framework. Because management has just leaned into heavier fiber capex and fresh buybacks following the Q3 2026 update, the current multiple already bakes in a fair amount of confidence that those plans will support the earnings base investors are paying for today. Explore the numbers behind Telephone and Data Systems's P/E valuation.
The Telephone and Data Systems Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that P/E puzzle around Telephone and Data Systems and turn it into clear, testable scenarios on the Community page that spell out which paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than it is today. Each scenario links its number to a specific view on how Telephone and Data Systems' growth profile, profitability and risk picture might evolve, which you can revisit as fresh results and announcements arrive.
One of the top community narratives on Telephone and Data Systems: 31% undervalued
"The divestiture of UScellular and major spectrum assets has substantially deleveraged TDS's balance sheet, freeing up capital for aggressive expansion..."
Discover why this Narrative puts Telephone and Data Systems at 31% undervalued.
One more check for Telephone and Data Systems before you close the file
Price ratios and community views tell only part of the story for Telephone and Data Systems, because professional earnings projections a few years out offer a separate yardstick you can compare with where the shares trade today. Explore where analysts expect Telephone and Data Systems to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com