


Earnings jump and fresh guidance put Zurn Elkay Water Solutions in focus
Zurn Elkay Water Solutions (ZWS) moved into the spotlight after reporting third quarter earnings per share from continuing operations of US$0.46 basic and US$0.45 diluted, along with new fourth quarter net sales guidance of US$430 million to US$437 million.
The recent earnings update landed against a weaker tape for Zurn Elkay Water Solutions. The share price is down about 6.5% over the past month and roughly 15.5% over 90 days. Even so, the 3 year total shareholder return of about 55% still points to a much stronger longer term outcome than the past year’s total shareholder return decline of around 7.6%.
Compare Zurn Elkay Water Solutions' latest move with a curated group of industrials that pair earnings momentum with resilient balance sheets using the list of solid balance sheet and fundamentals (24 results).
The question now is whether Zurn Elkay Water Solutions’ recent share price slide reflects a colder view on the business, or simply sentiment resetting around stronger earnings and fresh guidance, and how that lines up with today’s valuation.
Most Popular Narrative: 19% Undervalued
On this view, Zurn Elkay Water Solutions screens as cheaper than its narrative fair value of about $53.67, with the last close at $43.47. That gap is framed around margin strength, balance sheet capacity and cash generation rather than short term share price moves.
The main thing that has to go right is that Zurn Elkay maintains recent EBITDA margin gains, which reached 27.7% by Q2 2026, while continuing to integrate adjacencies like Intellihot and manage slower core sales growth as tariff related pricing tailwinds ease.
The current valuation implies the share price does not fully reflect the company’s recent margin expansion, low net leverage near 0.3x, and raised 2026 guidance for adjusted EBITDA and free cash flow. This narrative holds that Zurn Elkay Water Solutions is undervalued and presents a bullish stance.
See why 2 investors see Zurn Elkay Water Solutions as 19% undervalued.
Result: Fair Value of $53.67 (UNDERVALUED)
Still, this bullish Zurn Elkay Water Solutions story can be knocked off course if core sales growth slows as tariff pricing fades or if institutional investors keep trimming holdings and adding selling pressure.
Find out about the key risks to this Zurn Elkay Water Solutions narrative.
Another View: What Zurn Elkay Water Solutions’ P/E Is Telling You
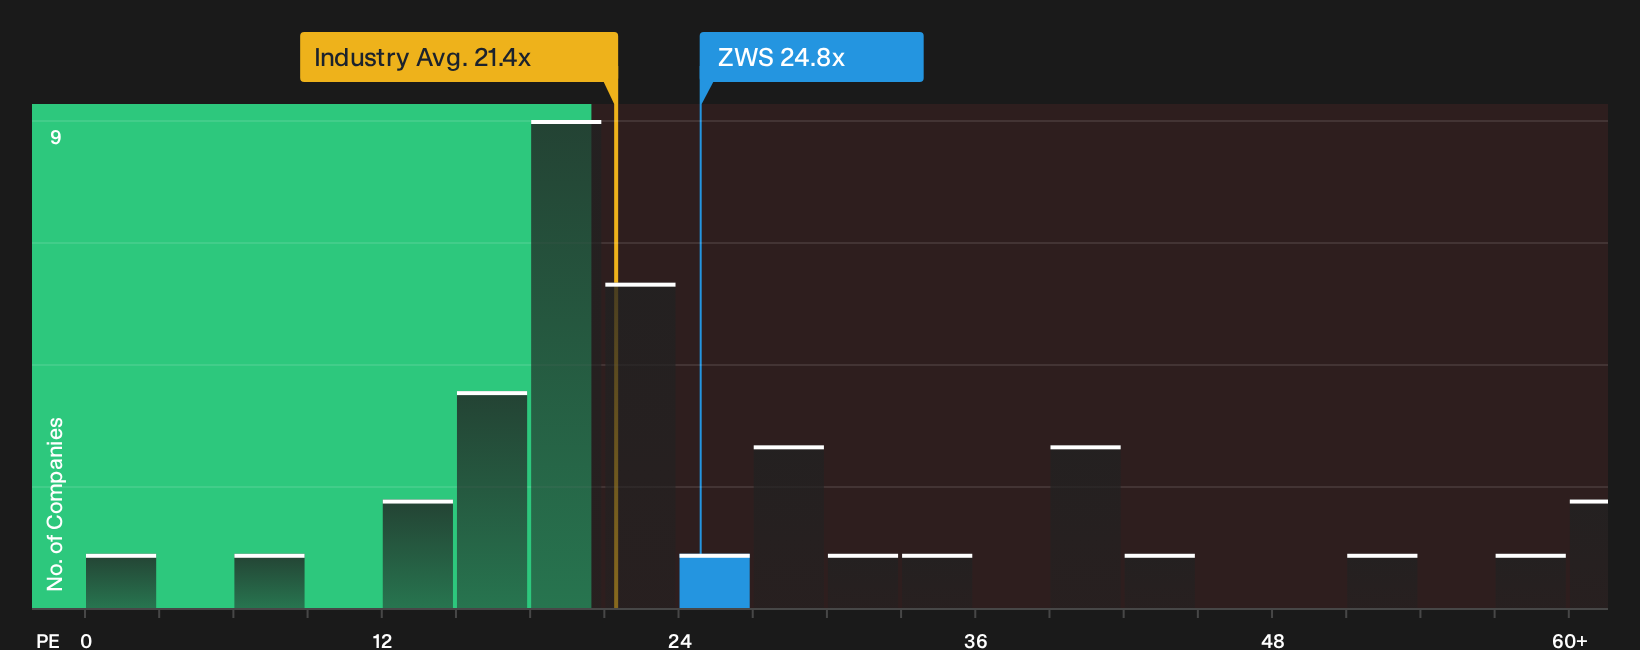
There is a different read on Zurn Elkay Water Solutions when the focus shifts to the current P/E ratio. The stock trades at about 24.8x earnings, which is higher than the US Building industry average of 21.3x and above a fair ratio estimate of 19.1x, so any move back toward that fair ratio could limit potential upside, even if earnings keep growing.
That mix of a higher P/E versus the sector, yet only a modest premium to peers and the fair ratio, leaves investors weighing whether this is simply paying up for quality or taking on valuation risk if sentiment cools. Which side of that line do you think the stock sits on?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Zurn Elkay Water Solutions is split, so treat this as your cue to review the numbers yourself and decide where you stand. To see what optimistic investors are focusing on, take a closer look at the 4 key rewards.
Looking for more Zurn Elkay Water Solutions investment ideas?
If Zurn Elkay Water Solutions is on your radar, do not stop here. Fresh ideas often come from comparing it with other high quality opportunities side by side.
- Target sturdier portfolios by stress testing your holdings against a 29 resilient stocks with low risk scores that aims to highlight resilience when conditions turn rough.
- Hunt for mispriced quality by scanning the 19 high quality undiscovered gems that may not yet be crowded with institutional money.
- Strengthen your income stream by reviewing the 8 dividend fortresses that focuses on higher yielding companies with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com