


- Fortuna Mining reported third quarter 2026 sales of US$293.44 million with net income of US$47.83 million, alongside updates on the Seguela expansion, Diamba Sud construction, and a US$750 million growth program supported by existing liquidity.
- The mix of higher year to date sales and net income with a softer quarterly profit, following the Seguela blockade disruption, puts execution risk at the center of Fortuna Mining's growth story.
- This article will assess how Fortuna Mining's investment narrative is reshaped by third quarter earnings and the ambitious Seguela expansion plan.
Scan Fortuna Mining's latest move in West African gold, then widen your radar to a curated set of 33 elite gold producer stocks that could reshape your watchlist.
Fortuna Mining Investment Narrative Recap
To own Fortuna Mining, you need to buy into a story of concentrated growth in West Africa, with Séguéla, Diamba Sud and Bambadji doing more of the heavy lifting after recent asset sales. The latest quarter keeps that thesis intact but with a clear warning label. Sales for the period were US$293.44 million, while net income came in at US$47.83 million.
In the short term, the key swing factor is whether Séguéla and Diamba Sud advance without fresh disruption or permitting surprises. The blockade at Séguéla and softer quarterly profit keep execution and cost control as the biggest near term risks. If those projects stay on schedule, the growth program and liquidity story remain largely unchanged.
The most relevant update for this earnings print is management’s decision to press ahead with a US$750 million growth program anchored by the Séguéla expansion and Diamba Sud build. That plan is backed by existing liquidity, rather than new equity. This keeps the focus on project delivery rather than capital raising.
For you as a shareholder, the link is direct. The same projects that concentrate risk are also the main catalysts, because they frame future production volumes, unit costs and cash generation. Any delay, cost overrun or fresh community or regulatory issue at Séguéla or Diamba Sud would matter more now that Fortuna Mining is leaning on fewer core mines.
Analysts frame Fortuna Mining's medium term path around revenue rising to $2.3b and earnings of $771.8m by 2029, based on an assumed 24.1% yearly sales growth rate and an earnings increase of about $393.6m from $378.2m today.
Uncover why Fortuna Mining's fair value indicates a 43% potential upside to its current price that could narrow quickly.
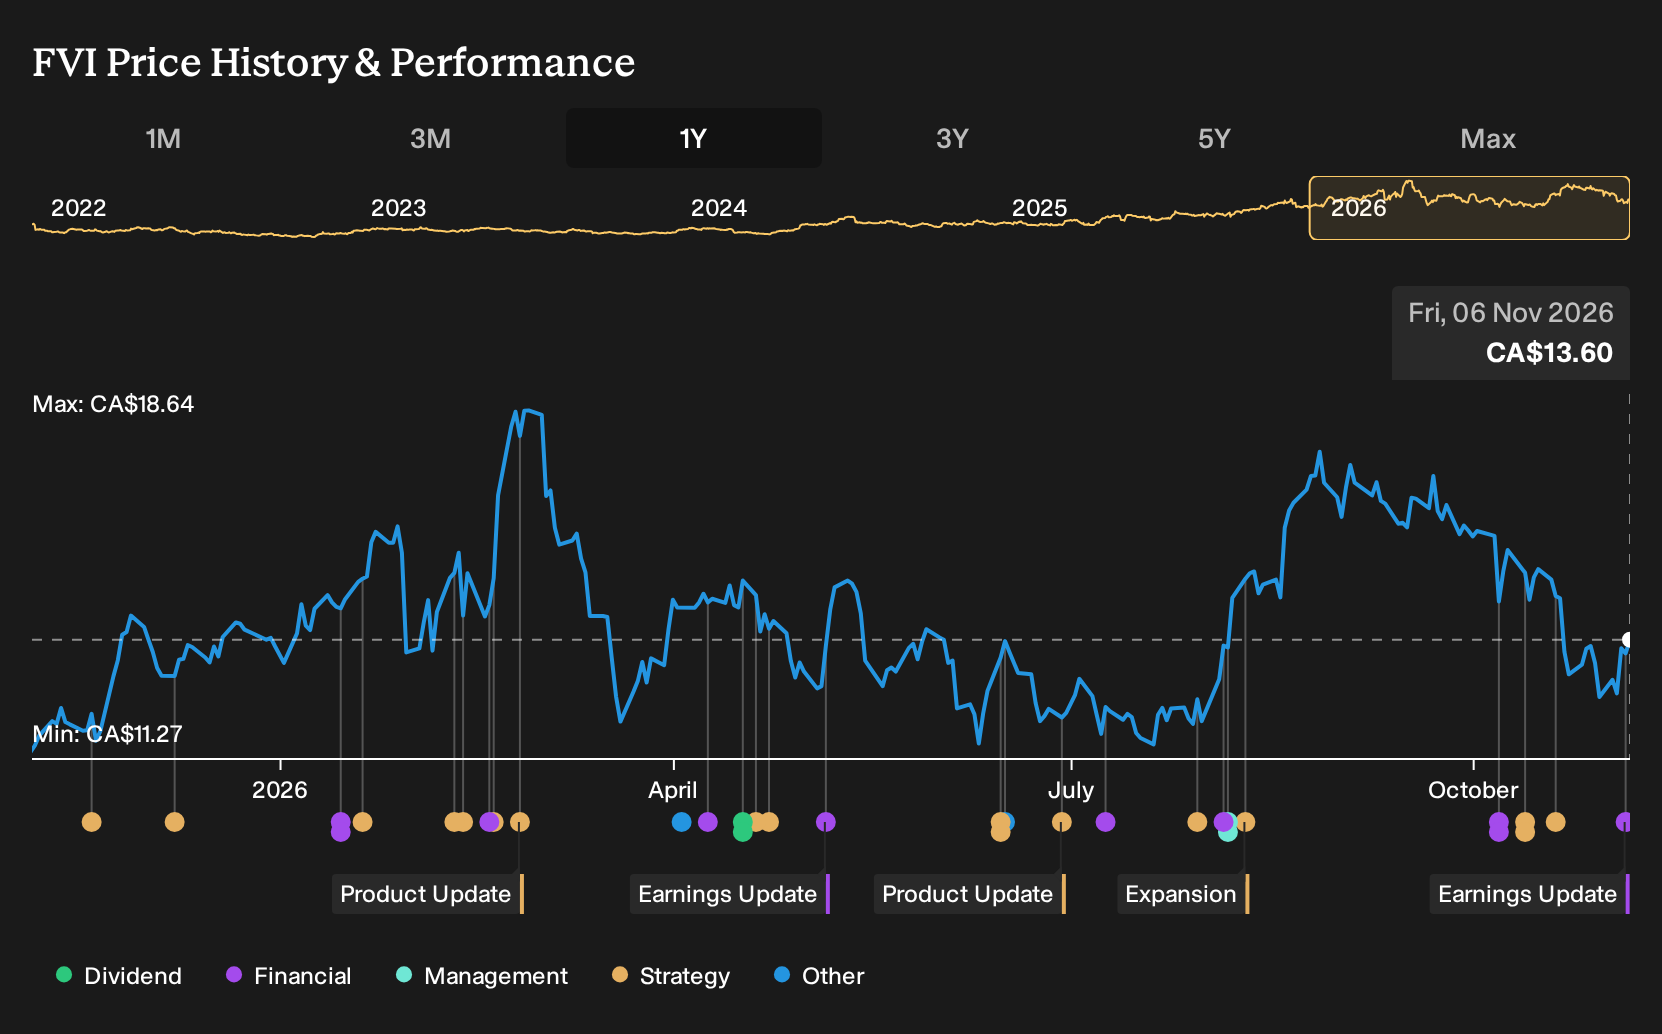
Exploring Other Perspectives
Some of the most optimistic analysts focus less on execution risk and more on Fortuna Mining’s volume potential. They were expecting revenue to reach about US$2.4b and earnings of roughly US$817.6 million by 2029. That is a much punchier story than consensus, and this third quarter update may push those views to evolve.
Explore 4 other Fortuna Mining fair value estimates, including one that suggests as much as 290% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fortuna Mining research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Fortuna Mining. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fortuna Mining's overall financial health at a glance.
Looking for more Fortuna Mining style investment ideas?
If Fortuna Mining has sharpened your focus on where to take risk, it can help to line it up against other opportunities that match your preferences on value, resilience and income using the Simply Wall St Screener.
- For investors who care most about quality at a reasonable entry point, scan a curated set of 6 high quality undervalued stocks that combine attractive fundamentals with pricing that may appeal to value focused portfolios.
- If capital protection sits high on your priority list, narrow your search to a 9 resilient stocks with low risk scores that screens for businesses with more resilient profiles and lower risk scores.
- When you want strong underlying finances to anchor your research, start with a list of solid balance sheet and fundamentals (5 results) so you are only comparing companies with balance sheets and fundamentals that clear a high bar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com