


Veracyte has just seen its share price fall sharply, and that move throws a fresh spotlight on whether the current valuation still lines up with the earnings power of the business. After a turbulent stretch, the question for anyone tracking the stock is how that price now compares with what the company is actually earning.
- Over the past week the stock has fallen 51.7%, which puts recent news and expectations about the business under far closer scrutiny when you weigh the price against its earnings.
- The reduced outlook for Decipher Prostate testing revenue, alongside the newly announced US$100 million share repurchase plan, can reshape how investors think about the durability and timing of Veracyte's future earnings stream.
- Your read on Veracyte is one view; the desks covering it have another. See what analysts think Veracyte's shares could be worth.
The issue now is whether Veracyte's current share price is adequately supported by its earnings when set against the Fair Ratio benchmark.
For context on how Veracyte's steep weekly decline fits into the broader hunt for earnings-backed opportunities, it can help to compare it with other 39 high quality undervalued stocks.
Where Does Veracyte Sit on Earnings?
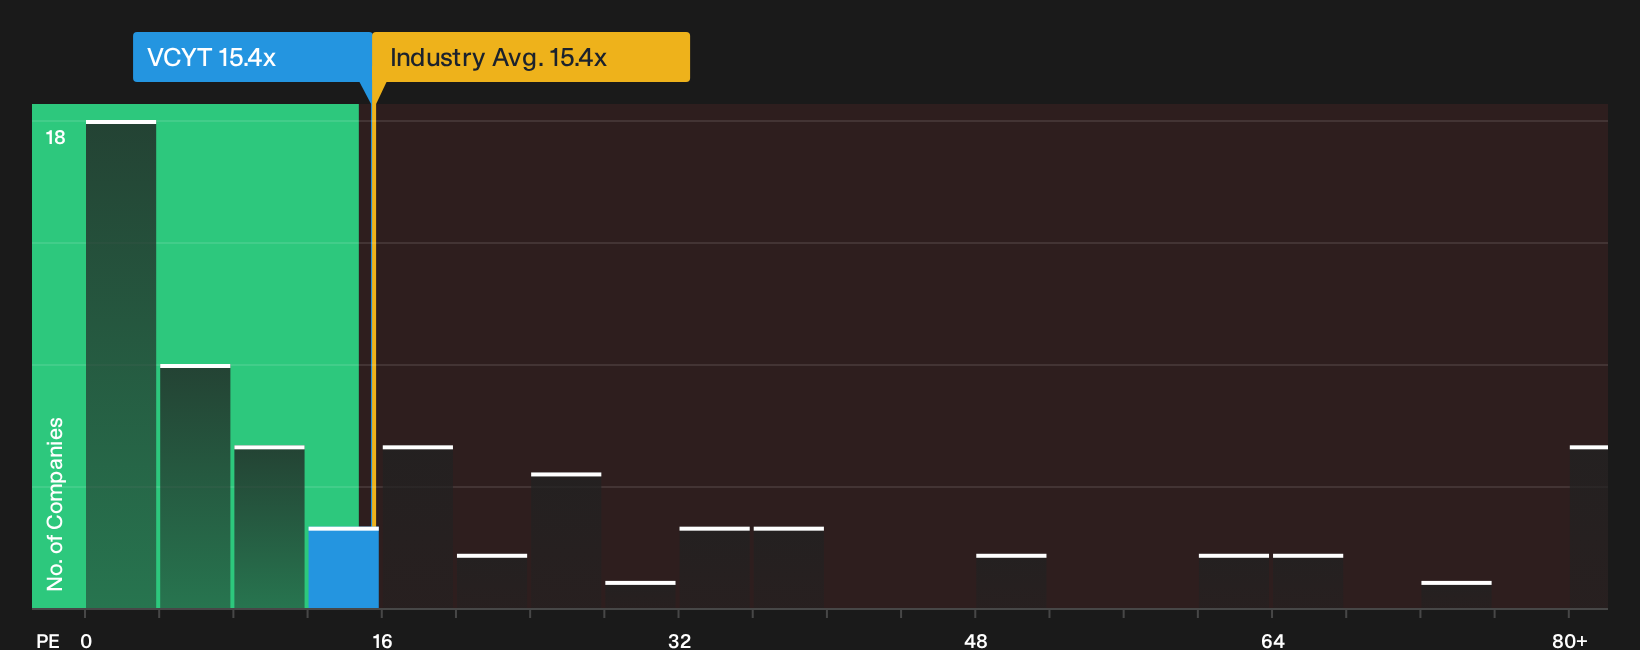
The P/E ratio suits Veracyte because the market is sharply focused on how current earnings stack up against the recent reset in expectations. Veracyte now trades on a P/E of 15.4x, which is close to the biotech industry average of 15.4x and below the wider peer group at 33.3x. The Fair Ratio model, which blends the company’s growth profile, margins, size and risk into a tailored benchmark, points to a level very similar to where the stock is currently priced.
Because the Decipher Prostate outlook was cut in the November 4 earnings release, that alignment with the Fair Ratio suggests the recent share price drop has already realigned Veracyte’s P/E with what the underlying earnings currently justify. The multiple does not indicate a clear discount or a glaring premium, so any call on value now rests on how confident you are in the durability of Veracyte’s earnings after this guidance change. Explore the numbers behind Veracyte's P/E valuation.
The Veracyte Narrative: What Would Justify Today's Price?
Veracyte's Simply Wall St Narratives pick up where the P/E discussion leaves off and spell out the specific future paths for growth, margins and earnings that would need to play out for the share price to look meaningfully higher or lower than it does today on the Community page. Rather than giving a single figure, they unpack the assumptions that figure rests on so you can watch how closely real world outcomes track those embedded expectations.
One of the top community narratives on Veracyte: 60% undervalued
"Heavy dependence on core products and payer coverage, combined with industry shifts and mounting regulatory and reimbursement pressures, threatens Veracyte's growth..."
Discover why this Narrative puts Veracyte at 60% undervalued.
One more Veracyte check before you draw your own line
You have the snapshot on Veracyte's current valuation, but the next piece is how professional analysts currently map out revenue, profits and margins a few years from now compared with today's pricing. Explore where analysts expect Veracyte to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com