


Half year earnings put fresh numbers around General de Galerías Comerciales SOCIMI
General de Galerías Comerciales SOCIMI (BME:GGC) has put fresh numbers on the table, reporting half year revenue of €143.06 million and net income of €92.92 million on sales of €84.4 million.
The fresh half-year figures arrive with General de Galerías Comerciales SOCIMI’s share price steady at €161.0. The stock has produced a 1-year total shareholder return of 13.38% and a 5-year total shareholder return of 17.12%, suggesting that momentum has been built less through short-term trading moves and more through longer-term income and reinvestment effects.
See how General de Galerías Comerciales SOCIMI compares with other real estate players that screen for balance sheet strength and fundamentals using our curated list of solid balance sheet and fundamentals (193 results)
For General de Galerías Comerciales SOCIMI, that steady share price and double digit multi year return leave a simple tension. Are investors paying for a stronger underlying business, or for a sentiment shift that recent earnings just happen to confirm?
Price-to-earnings of 21.8x for General de Galerías Comerciales SOCIMI: Is it justified?
On valuation, General de Galerías Comerciales SOCIMI trades on a P/E of 21.8x while the share price sits at €161. That multiple is well above both local peers on 8.2x and the wider European Retail REITs group on 10x, so the market is clearly paying a premium for each euro of current earnings.
The P/E ratio compares the price investors pay per share with the earnings generated per share. For a real estate owner operator like General de Galerías Comerciales SOCIMI, that metric often signals what the market thinks about the resilience of cash generation, the stability of rental income, and the prospects for future profit.
Earnings have grown 37.4% over the past year and 14.3% per year over five years, with reported net profit margins at 79.6% compared with 61.8% a year earlier. That kind of profitability record, combined with the assessment that the business has high quality earnings, gives one explanation for why investors might accept a richer earnings multiple.
The premium is still stark. A P/E of 21.8x versus a Spanish Retail REITs peer group at 8.2x and a European sector average of 10x indicates that the market is pricing General de Galerías Comerciales SOCIMI much more highly than similar real estate vehicles.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 21.8x (OVERVALUED).
Still, the story around General de Galerías Comerciales SOCIMI could shift quickly if rental conditions soften or if higher financing costs start to pressure that earnings multiple.
Find out about the key risks to this General de Galerías Comerciales SOCIMI narrative.
Another look at General de Galerías Comerciales SOCIMI's value
The earlier P/E view already pointed to a rich price tag for General de Galerías Comerciales SOCIMI. Our DCF model goes further. It estimates future cash flow value at €61.05 per share, well below the current €161, which flags the stock as overvalued on this approach.
When two methods both lean expensive, it raises a simple question for you as an investor. Is the share price stretching too far ahead of the cash General de Galerías Comerciales SOCIMI is expected to generate, or is the model missing something material in the story?
Look into how the SWS DCF model arrives at its fair value.
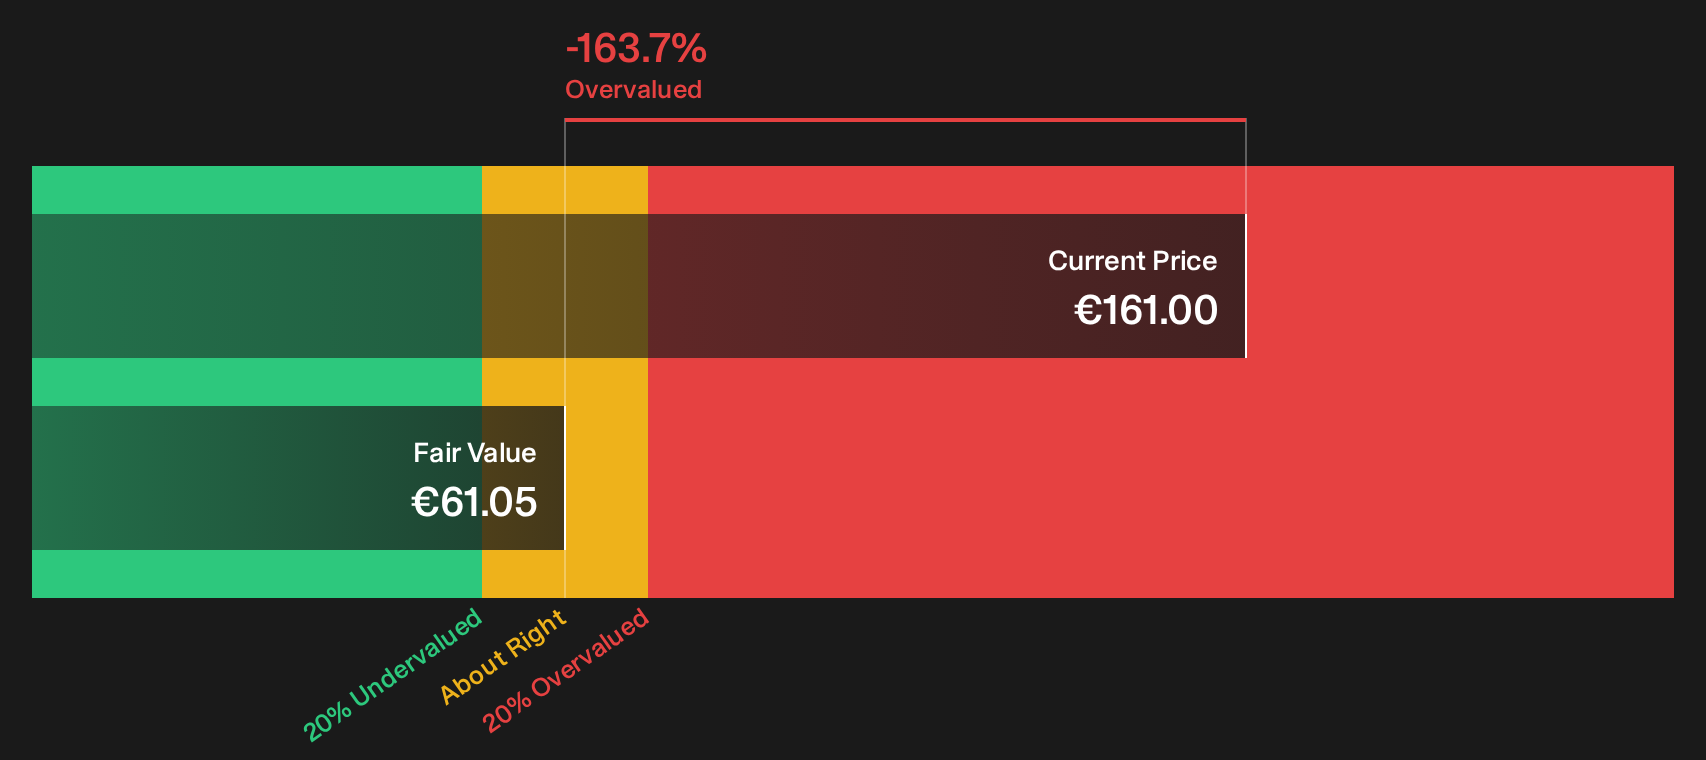
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out General de Galerías Comerciales SOCIMI for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 224 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around General de Galerías Comerciales SOCIMI in this piece leans cautious, so move quickly to review the figures yourself and decide what you think. To see why some investors still focus on potential upsides, take a closer look at the 1 key reward.
Looking for more investment ideas beyond General de Galerías Comerciales SOCIMI?
Do not stop with just one stock. Use fresh screens to widen your opportunity set and pressure test whether General de Galerías Comerciales SOCIMI still earns a place in your portfolio.
- Target reliable income first and assess which high yield opportunities make the cut with our focused list of income ideas using the 232 dividend fortresses.
- Hunt for quality at a sensible entry price and compare richer valuations with potential bargains identified through the 224 high quality undervalued stocks.
- Prioritise peace of mind and stress test your holdings against financially resilient companies highlighted in the 212 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com