


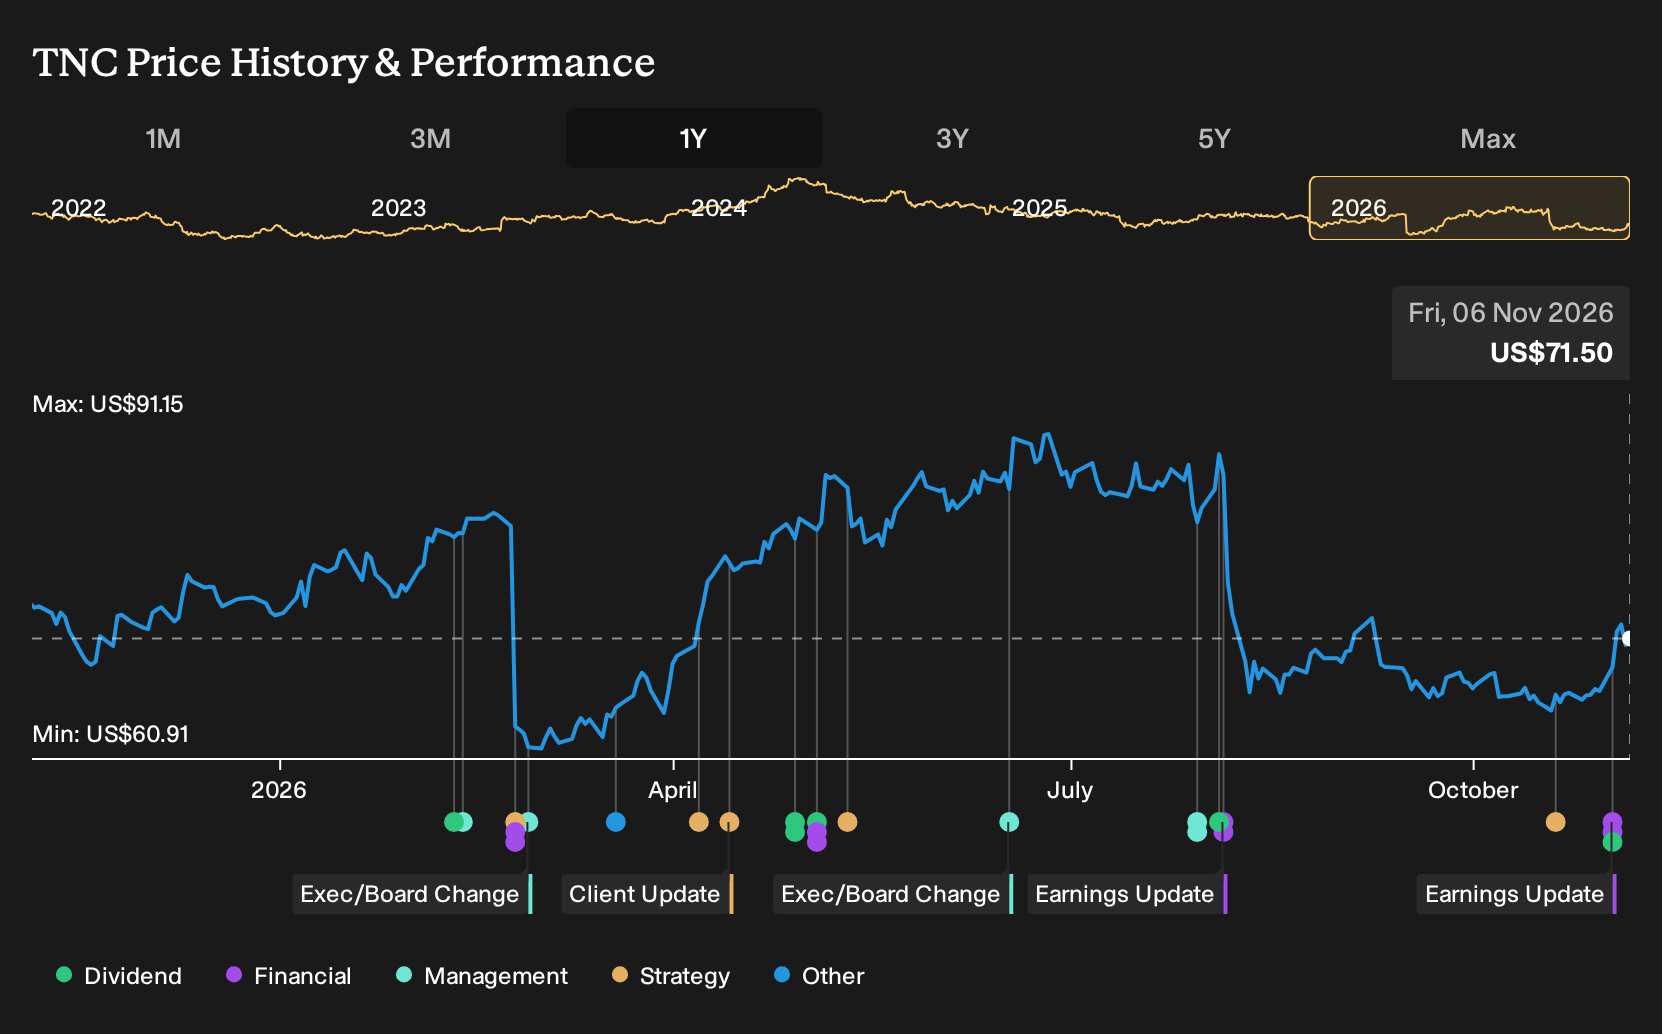
- Tennant Company reported third quarter 2026 sales of US$322.3 million and net income of US$19.5 million, alongside reaffirmed full year 2026 sales and earnings guidance and a quarterly dividend of US$0.325 per share payable in December.
- The mix of higher quarterly earnings, maintained full year targets and an ongoing cash return via dividends highlights Tennant's focus on operational execution and capital discipline despite pressure on year to date net income.
- We will now look at how Tennant's reaffirmed full year guidance could reshape the existing investment narrative around robotics and margins.
Scan Tennant's robotics and cleaning peer group for capital disciplined operators by jumping into our curated list of 89 robotics and automation stocks as this earnings season reshapes expectations across the sector.
Tennant Investment Narrative Recap
Tennant attracts shareholders who believe its mix of industrial cleaning, robotics and service revenue can compound steadily once current growing pains ease. The latest quarter showed higher quarterly net income and sales versus a year ago, which supports that basic thesis, but the nine month earnings drop keeps execution risk very real. The short term hinge still looks like stabilizing margins while keeping robotics momentum intact.
The biggest swing factor remains cleaning up ERP related disruption and regional pricing pressure so that revenue converts more cleanly into profit. The main risk is that cost inflation, competition from lower priced equipment and ongoing ERP remediation keep net margins subdued for longer. This earnings print helps sentiment but does not remove that concern.
The most relevant fresh data point is Tennant reaffirming its 2026 net sales guidance of US$1.27b to US$1.31b and diluted EPS guidance of US$2.15 to US$2.80. Keeping those targets after nine month net income of US$27.3 million, down from US$48.2 million a year earlier, signals confidence in the operational plan and the second half margin path.
For you as an investor, that guidance effectively becomes the scoreboard for whether ERP fixes, robotics growth and cost control are tracking to plan. Any future miss against those ranges would likely raise questions about competitive intensity, pricing power and the speed of ERP recovery, while delivery in line with guidance would reduce some of the execution overhang that has weighed on Tennant in recent years.
Tennant consensus targets: what the numbers imply
Tennant's narrative projects US$1.5b revenue and US$131.1 million earnings by 2029. This is based on an assumption of 6.5% yearly revenue growth and an earnings increase of about US$112.8 million from US$18.3 million today.
Uncover why Tennant's fair value indicates a 23% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic Tennant analysts lean hard into robotics subscriptions as the swing factor. Before this earnings release, that group was penciling in roughly US$1.5b of revenue and US$121.5 million of earnings by 2029. You can treat this as one possible path and then compare it with more cautious views that may adjust as fresh results land.
Explore 3 other Tennant fair value estimates, including one that suggests as much as 164% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Tennant research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Tennant. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tennant's overall financial health at a glance.
Looking for more investment ideas beyond Tennant?
If this Tennant update has sharpened your view on quality, income and risk, you can use the Simply Wall St Screener to hunt for other stocks that fit those same priorities in a more systematic way.
- If resilience matters most to you, start with companies that pair sturdy financial profiles with measured volatility by checking out the 29 resilient stocks with low risk scores.
- For investors who want income front and center, scan for reliable payers with elevated yields through the 8 dividend fortresses.
- If you are searching for potential future leaders that are still under the radar, broaden your watchlist with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com