


Fresh earnings are driving the conversation around Colgate-Palmolive (CL) after the consumer products group reported third quarter 2026 results and lifted its full year outlook for sales and profitability.
Colgate-Palmolive's recent Q3 beat and higher full year guidance come after a strong run, with the share price delivering a 24.29% year to date return and a 25.54% total shareholder return over the past year, even though the stock slipped 2.16% on the day after the results.
See how Colgate-Palmolive compares to other consumer staples showing resilient earnings momentum by running the hand picked 29 resilient stocks with low risk scores alongside this latest Q3 update.
After Colgate-Palmolive's strong run and modest pullback, the share price now sits between its recent high, analyst targets and intrinsic estimates. Where does fair value really land within that range?
Most Popular Narrative: 12% Overvalued
Colgate-Palmolive closed at $96.56, while the most followed narrative, according to rcb9, points to a fair value of $86.48 using a 7% discount rate. That gap frames the latest Q3 beat as impressive on execution but tight on valuation headroom.
A note on the shape of this result. Twenty four times forward Base Business earnings of roughly $3.88 implies about $93 today. This model returns $86.48. The whole difference is structural. When the discount rate exceeds the growth rate, five years at a three point gap costs about 16%. For a slow compounder this method is inherently more conservative than a simple multiple, and that is worth knowing before treating the output as a verdict rather than as one lens.
See why 11 investors see Colgate-Palmolive as 12% overvalued.
Result: Fair Value of $86.48 (OVERVALUED)
Still, this fair value lens could crack if North America stays weak for longer or if another impairment in skin health hits Colgate-Palmolive earnings quality.
Find out about the key risks to this Colgate-Palmolive narrative.
Another View: Colgate-Palmolive Through The DCF Lens
Colgate-Palmolive looks very different when viewed through the SWS DCF model. On this framework, the shares at $96.56 sit about 23% below an estimated future cash flow value of $125.78. This frames the stock as undervalued rather than stretched.
That places the cash flow view directly against the $86.48 narrative fair value. Investors are left to consider whether the market eventually leans toward the cautious multiple-based lens or the richer DCF outcome.
To see how this cash flow driven approach works in practice, and what assumptions sit underneath it, Look into how the SWS DCF model arrives at its fair value.
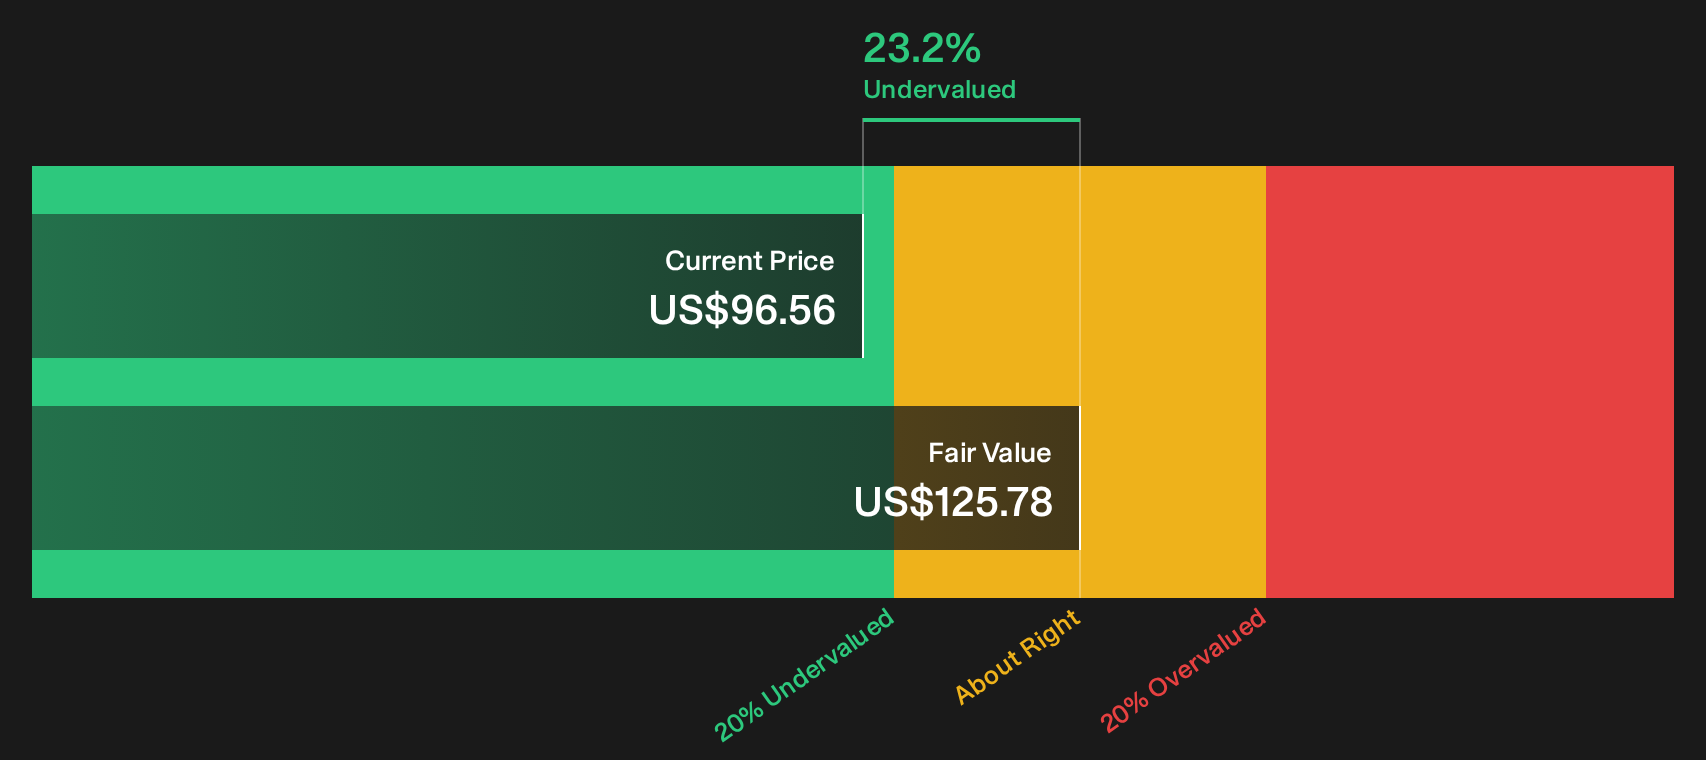
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Colgate-Palmolive for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Colgate-Palmolive feels familiar, that is the point. Act quickly, stress test the assumptions for yourself, then weigh up 3 key rewards and 3 important warning signs
Looking for more Colgate-Palmolive sized ideas?
You have seen how one detailed story can reshape your view on Colgate-Palmolive. Do not stop here when other opportunities could be waiting just outside your portfolio.
Use the Simply Wall St screener to pressure test your current holdings and surface fresh candidates before the crowd catches on.
- Upgrade portfolio quality by scanning a list of solid balance sheet and fundamentals (24 results). This can help highlight businesses with healthier financial footing than many headline stocks.
- Hunt for mispriced potential using the 19 high quality undiscovered gems and spot companies the wider market may not be paying close attention to yet.
- Lock in more dependable income streams by running the 8 dividend fortresses and lining up options that focus on stronger yield support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com