


- Guidewire Software recently introduced a broad agentic insurance platform and related AI tools, while Gore Mutual Insurance Company embedded Guidewire ProNavigator into its underwriting and claims systems to support faster, more consistent decisions.
- The combination of AI driven product expansion and real world deployment at Gore Mutual highlights how Guidewire Software is pushing deeper into insurers’ core workflows, which can influence how much value existing customers extract from Guidewire Cloud over time.
- The focus now turns to how Guidewire Software's new agentic insurance platform could reshape the existing investment narrative around cloud adoption.
Scan the insurers most actively integrating AI into underwriting and claims by reviewing the hand picked 41 AI small caps that reflect the same automation trend as Guidewire Software.
Guidewire Software Investment Narrative Recap
To own Guidewire Software, you need to believe insurers keep committing budget to cloud based core systems and higher value AI tools on top of them. The near term swing factor is how consistently that cloud and AI attach story comes through in ARR and subscription metrics, especially with revenue growth forecasts below 20% and a high P/E multiple.
The biggest operational risk is a pause in insurer IT spending or slower migrations from on premise platforms, which could pressure ARR and limit operating leverage. The latest AI announcements look additive but do not by themselves remove execution risk around cloud transitions or investor sensitivity to guidance and margins.
The launch of Guidewire Software's agentic insurance platform is the clearest operational link to the current news. It pulls AI agents, data, and workflow tools into the same infrastructure as PolicyCenter, ClaimCenter, and other cloud products, which aligns with the catalyst of selling more functionality into the existing P&C customer base.
For you as an investor, the practical question is whether this platform approach results in higher value software tiers, more AI usage inside live workflows, and better services efficiency. The same launch also raises execution risk, since insurers need guardrails, governance, and performance they can trust before putting agentic tools into production at scale.
Guidewire Software Forecasts and Valuation Set-Up
Guidewire Software's current analyst narrative ties the new agentic insurance platform directly into a long term financial arc that runs out to 2029. The working assumption is that property and casualty clients keep shifting more policy, billing, and claims workloads into Guidewire Cloud, then layer on tools like ProNavigator and underwriting assistants, which underpins both subscription metrics and the earnings profile analysts are modeling.
On the top line, the consensus view bakes in 15.7% annual revenue growth over the next three years. That pace is what has to support broader use of Guidewire Cloud and adjacent products such as PricingCenter and UnderwritingCenter, while AI agents are slotted into day to day underwriting and claims flows. The same forecasts assume profit margins move from 9.4% today to 15.7% in about three years, which implies that higher value software tiers and more efficient services work eventually flow through to the income statement.
Earnings are a key pressure point. Analysts currently expect Guidewire Software to lift earnings from US$139.3 million today to US$359.7 million by around 2029, which is roughly 2.6x higher than current levels. That path is not settled though. The most bullish forecast sits at US$436.9 million, while the most cautious call is US$301.7 million, which shows there is real debate about how much profit the new AI heavy product set and cloud usage can support by the end of the decade.
Guidewire Software's narrative projects US$2.3b revenue and US$359.7 million earnings by 2029. This assumes 15.7% yearly revenue growth and an earnings increase of about US$220 million from US$139.3 million today.
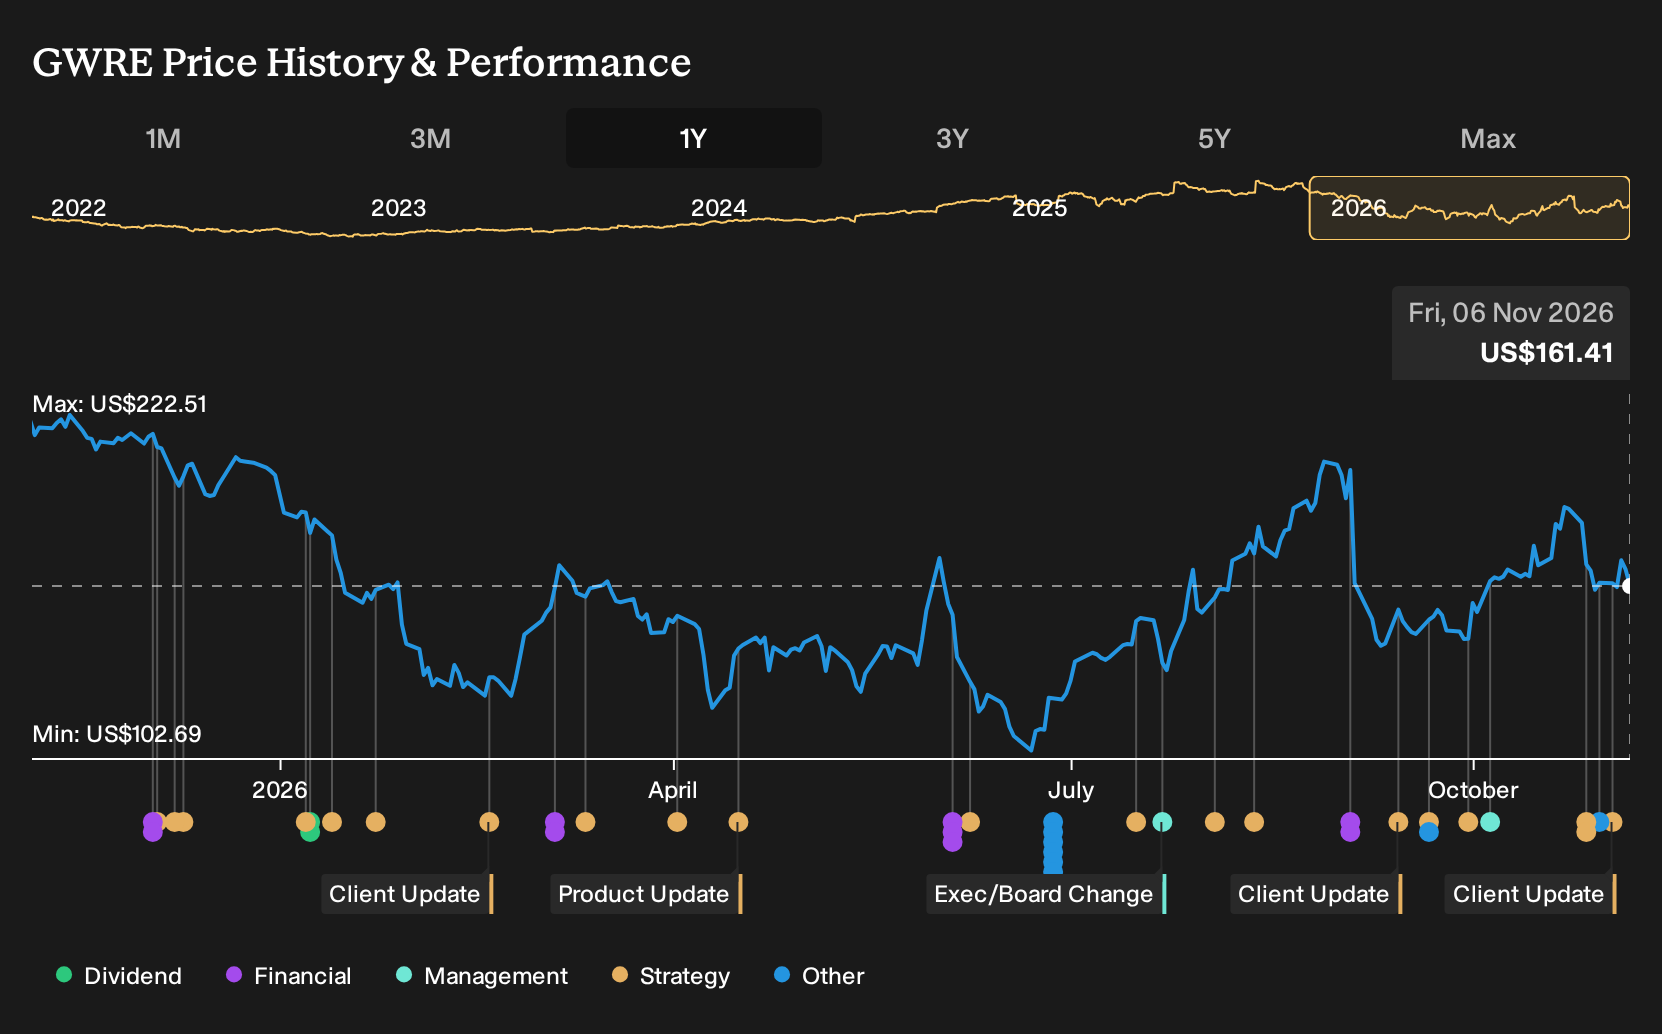
For the current analyst price targets to hold, Guidewire Software would need to be valued at a P/E of 56.0x on those 2029 earnings, compared with about 99.4x today and against a US Software sector average of 30.8x. That gap highlights how much faith is being placed in earnings expansion and margin progress tied to cloud migrations and AI deployment. It also means sentiment on this stock can swing sharply when management updates ARR, subscription growth, or profitability guidance, because those updates touch the core of what is being priced in.
Forecasts also assume the share count edges down by roughly 3.56% a year over the next three years. That expectation effectively layers a small buyback tailwind on top of the operational story and influences how investors think about earnings per share outcomes once the agentic insurance platform is fully woven into customer workflows.
Uncover how Guidewire Software's fair value indicates a 32% potential upside to its current price that might be short-lived.
Exploring Other Perspectives
One alternative angle focuses on how bullish analysts framed Guidewire Software even before this agentic platform and the Gore Mutual deployment. That group was modeling roughly US$2.5b of revenue and about US$434.5 million of earnings by 2029, a more optimistic arc than consensus. These views can shift, so explore several viewpoints before deciding what this news means for you.
Explore 3 other Guidewire Software fair value estimates, including one that suggests the potential for as much as 58% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Guidewire Software research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Guidewire Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Guidewire Software's overall financial health at a glance.
Looking for more investment ideas beyond Guidewire Software?
If this Guidewire Software story has sharpened your thinking about cloud and AI adoption, use that same lens to scan a wider field of potential opportunities with the Simply Wall St Screener.
- If you want income to play a bigger role in your portfolio, start with companies that combine higher yields with resilience by screening through 8 dividend fortresses.
- If capital preservation sits near the top of your priority list, narrow the universe to businesses with sturdier balance sheets and steadier fundamentals using the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for mispriced quality, focus on companies that pair solid cash generation with attractive valuations by reviewing the 39 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com