


TD SYNNEX (SNX) has just locked in a new US$1.75b senior unsecured term loan, refinancing an existing US$750m facility and reserving extra capacity for general purposes, including potential acquisitions.
Against that backdrop, TD SYNNEX’s share price has pulled back recently, with a 7 day share price return of down 7.6% and a 30 day share price return of down 19.4%, even though the year to date share price return is 42.6% and the 1 year total shareholder return is 45.7%. Recent AI focused product launches, new cybersecurity partnerships and now the US$1.75b term loan are all landing in a market that is reassessing how much short term risk to price in after a strong multi year total shareholder return of 138.3%, so momentum appears to be cooling in the near term even as longer term holders remain ahead.
Compare TD SYNNEX's AI and cybersecurity push with hand picked peers by scanning the 41 AI small caps now attracting attention around automation, data infrastructure and recurring software revenue.
TD SYNNEX now couples a sharp pullback with fresh AI and cybersecurity bets and new debt capacity. Does that mix still skew the risk reward towards buyers at today’s P/E of about 13.1x?
Most Popular Narrative: 35.6% Undervalued
TD SYNNEX’s most followed valuation story lines up a fair value of about $339.64 against the last close of $218.73, so the gap that narrative highlights is wide enough that investors are focusing on what has to go right in cash flow and margins for that view to hold.
The continued enterprise-wide digital transformation and AI adoption, now supported by TD SYNNEX reporting non GAAP gross billings of US$31.8b and non GAAP EPS of US$5.68 in fiscal Q3 2026 with operating income and EPS growing faster than billings, is extending TD SYNNEX's addressable market and generating higher recurring revenue streams, which can support sustained revenue and earnings growth.
See why 23 investors see TD SYNNEX as 36% undervalued.
Result: Fair Value of $339.64 (UNDERVALUED)
Still, the Hyve unit’s heavy working capital drag and lower margin AI server programs could keep cash flow tight and pressure sentiment around the TD SYNNEX narrative.
Find out about the key risks to this TD SYNNEX narrative.
Another View: TD SYNNEX Through The P/E Lens
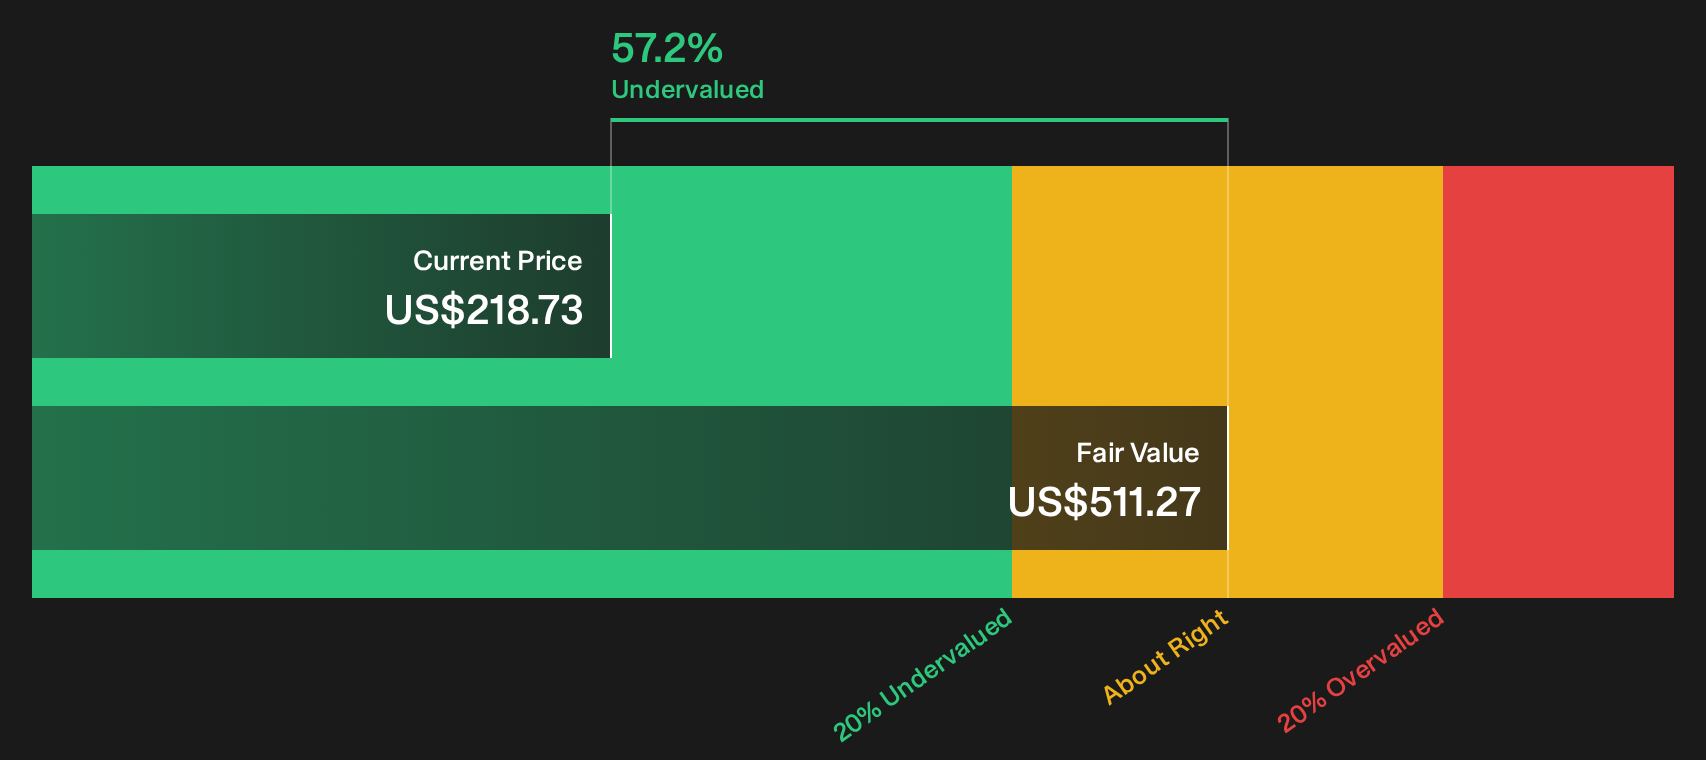
The SWS DCF model points to a fair value of $511.27 for TD SYNNEX, which frames the current $218.73 price as heavily undervalued. Yet on a plain P/E check of 13.3x, the stock looks slightly expensive against a 12.7x peer average. How much weight do you want to give that long range cash flow view versus today’s multiple?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around TD SYNNEX can feel messy, so move quickly, review both the upside and the weak spots, and weigh the 4 key rewards and 2 important warning signs.
Looking for more TD SYNNEX investment ideas?
If TD SYNNEX has your attention, do not stop here. Wider context across other opportunities often sharpens your view on this stock’s risk and reward.
- Spot potential mispricings by scanning a curated set of companies that currently screen as 39 high quality undervalued stocks based on their fundamentals and recent pricing.
- Strengthen your income stream by reviewing a focused group of 8 dividend fortresses that emphasise higher yields with resilient profiles.
- Prioritise resilience by scanning a carefully filtered 29 resilient stocks with low risk scores that emphasises sturdier balance sheets and steadier risk characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com