


PepsiCo (PEP) just renewed and expanded its beverage supply deal with KFC across eight international markets, keeping its brands front and center in a key global fast food channel.
PepsiCo shares have picked up speed recently, with a 30 day share price return of 14.23% and a 7 day gain of 2.91%. This comes even though the year to date share price move is slightly lower and the 3 year total shareholder return is still down 5.64%, as investors weigh fresh deals with KFC and ETF buying against earlier earnings guidance cuts and margin pressure.
Spot 39 high quality undervalued stocks that, like PepsiCo after its renewed KFC deal and fresh ETF interest, could be setting up for their next re-rating.The recent jump in PepsiCo shares raises a simple fork in the road for investors. Has this KFC renewal and ETF interest already done the heavy lifting, or is valuation still pointing to meaningful upside from here?
Most Popular Narrative: 29% Undervalued
The most followed PepsiCo valuation story pegs fair value at $200.01 per share, well above the last close of $141.34, which puts the recent KFC deal and ETF flows against a backdrop of a stock already framed as materially cheap by that narrative.
PepsiCo [PEP] is a classic *growth + income* compounder, not a high growth stock.1. Long term - Growth and Income caseIncome: Very Strong - *Dividend King: 54 consecutive years* of increases, paying since 1965 - 2026 dividend = *$5.92 / year* ($1.48 quarterly), up 4% from $5.69 - Yield now ∼3.5-3.6%; almost 3x S&P 500. At 20-year average dividend growth of ∼8%, early buyers now have 10% yield on cost.
See why 34 investors see PepsiCo as 29% undervalued.
According to Lijo, who authored this widely followed narrative, PepsiCo is framed less as a fast mover and more as a compounder that leans on a long dividend record and a large global snacks and drinks footprint. That view treats the KFC renewal as another volume channel layered onto a business already generating $98.2b in annual revenue and $10.9b in net income, rather than a one off swing factor.
The same storyline points to PepsiCo as an income led holding, helped by a stated 4.19% dividend yield and a long history of annual increases. For investors who prioritise cash returns, that setup means the recent 14.23% 30 day share price gain is only one part of the equation, with the regular payout forming a large share of the expected total return over time.
Result: Fair Value of $200.01 (UNDERVALUED)
Still, pressure in PepsiCo Foods North America, along with shifting health preferences around sugary drinks and salty snacks, could challenge this income heavy thesis.
Find out about the key risks to this PepsiCo narrative.
Another View: What Multiples Say About PepsiCo
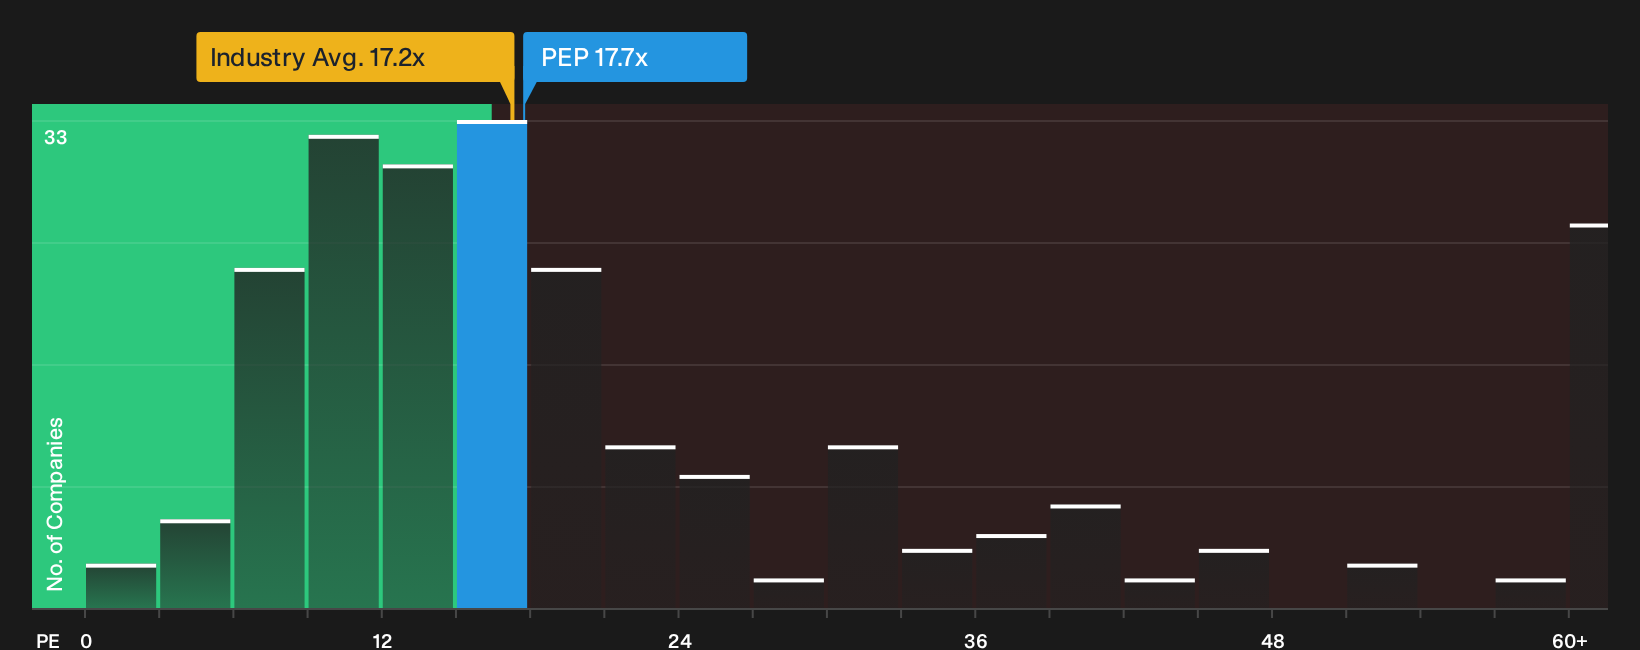
On a simple earnings multiple, PepsiCo tells a different story to that 29% upside narrative. The stock trades on a P/E of 17.7x, only slightly above the global beverage sector at 17.2x, yet well below its closer peer group at 30.2x and beneath a fair ratio of 23.7x.
That gap suggests the market is pricing PepsiCo more cautiously than both peers and the fair ratio imply. This may limit downside if sentiment cools, but it also raises the question of how much re rating room is really left if growth expectations stay modest.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around PepsiCo leaves you undecided, consider acting while the facts are front of mind and weighing both sides yourself. Start by checking the 4 key rewards and 1 important warning sign
Looking for more PepsiCo style investment ideas?
Before the momentum around PepsiCo fades from your mind, take a moment to hunt for other opportunities that could complement or balance your portfolio.
- Scan for resilient dividends that might anchor your income stream through 8 dividend fortresses.
- Hunt for overlooked quality where strong balance sheets and fundamentals do the heavy lifting via list of solid balance sheet and fundamentals (24 results).
- Spot potential future standouts early by running through 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com