


- ICON plc reported third quarter basic earnings per share from continuing operations of US$1.59, turning around a prior year basic loss, and introduced AI-directed video production within its FIRECREST platform to automate clinical trial content while keeping sponsor control and security.
- The mix of materially higher earnings per share for the quarter and nine month period, alongside FIRECREST’s AI video engine that targets faster and more consistent trial communications, points to ICON tightening both financial performance and operational tooling around clinical execution.
- We will look at how ICON's investment narrative is affected by FIRECREST's AI video engine alongside the latest earnings shift.
Scan beyond ICON and see how other research specialists are using AI to reshape clinical workflows with a hand-picked set of 35 healthcare AI stocks in the same broader theme.
ICON Investment Narrative Recap
To own ICON, you need to believe this clinical research group can turn strong recent earnings into durable profitability while working through mix and governance issues. The sharp shift from a basic loss per share to US$1.59 of basic earnings per share in Q3, and US$3.90 over nine months, supports that case but does not erase prior concerns.
The key near term catalyst is whether large recent bookings and AI driven tools like FIRECREST convert into healthier direct fee work and firmer margins, even as management expects 2026 revenue to decline on a constant currency basis. The biggest risk remains execution on mix, plus lingering trust questions after the accounting investigation and control weaknesses.
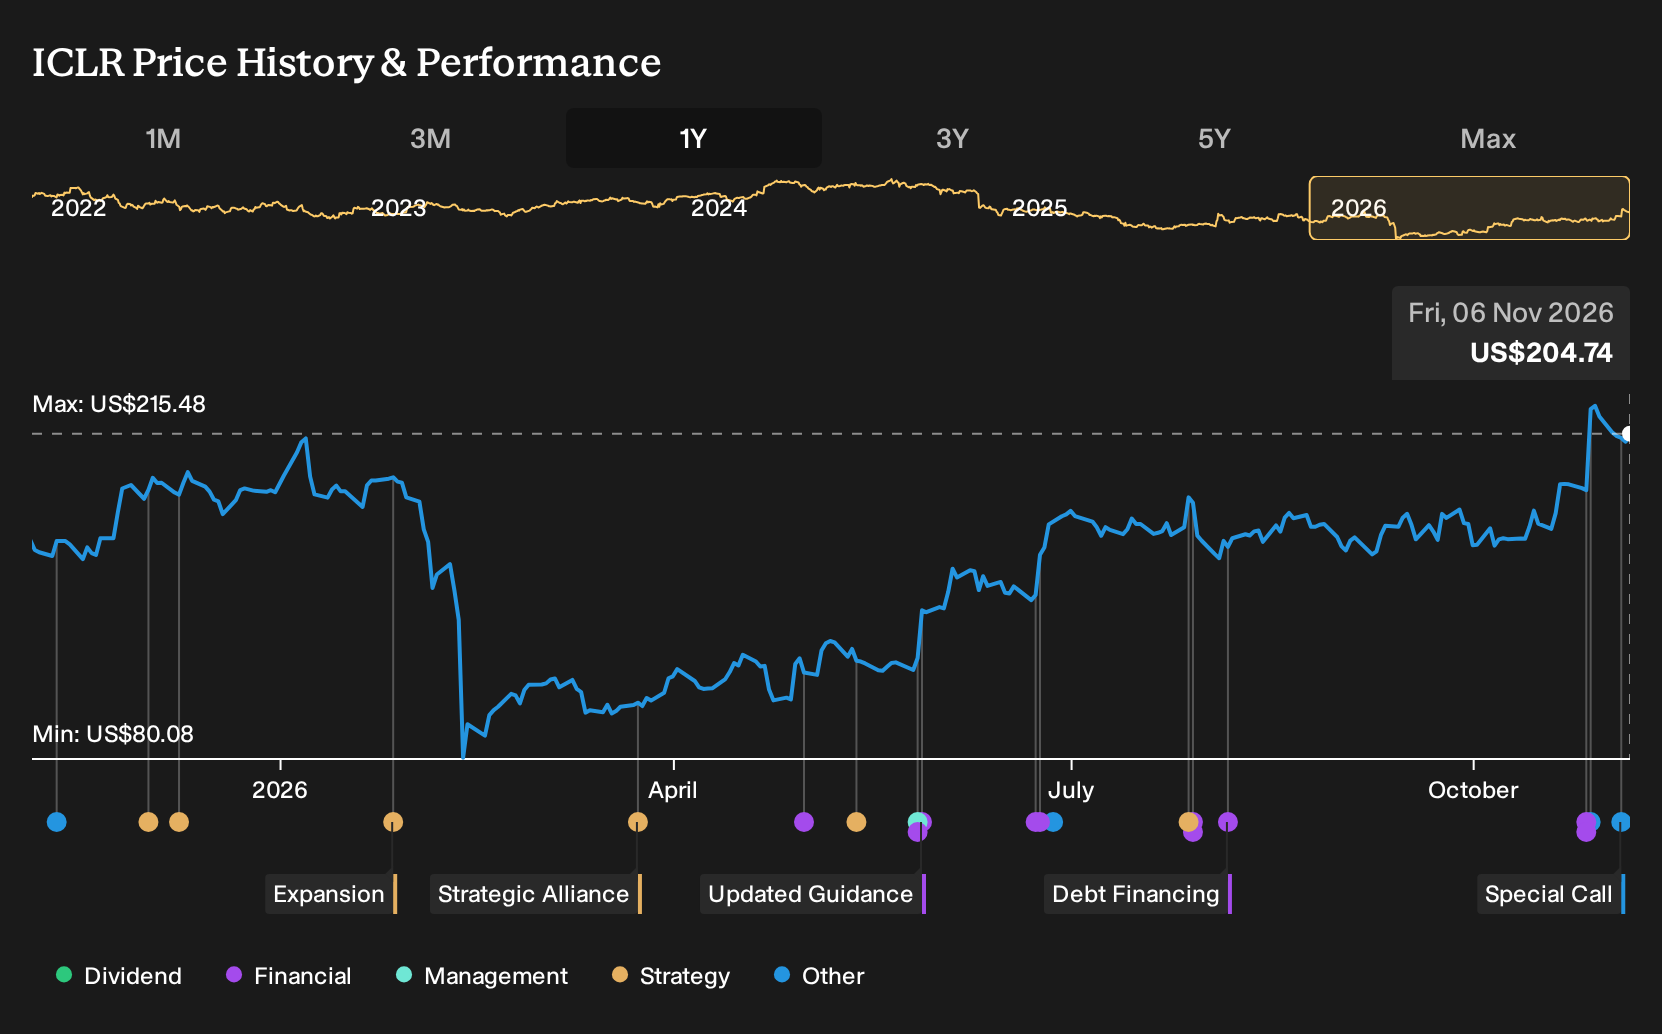
The most relevant update here is ICON’s new earnings guidance for 2026, with management expecting revenue between US$8.1b and US$8.2b. That range helps frame how the recent EPS recovery and FIRECREST’s AI video engine sit against a year where the group already flagged a revenue decline on a constant currency view.
For you as an investor, the guidance keeps attention squarely on delivery. The story now hinges on ICON converting its AI tools, expanded labs and big contract wins into steadier fee revenue and adjusted EBITDA margins, while proving that accounting problems and one off items are contained and that clinical operations can support the earnings profile implied by recent results.
ICON's current analyst blueprint assumes revenue of US$9.5b and earnings of US$820.1 million by 2029, built on 4.9% yearly revenue growth and an earnings increase of about US$386.7 million from US$433.4 million today.
Explore why ICON's fair value suggests a 10% potential upside to its current price before that discount appears to be fully reflected.
Exploring Other Perspectives
One optimistic twist on ICON focuses on AI as a margin story. The most bullish analysts were already assuming revenue of about US$9.4b and earnings of roughly US$990.3 million by 2029, before this FIRECREST update. You can treat those forecasts as a high bar, and then ask how the new earnings and AI news might shift that debate.
Explore 5 other ICON fair value estimates, including one that suggests as much as 241261% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ICON research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ICON. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ICON's overall financial health at a glance.
Looking For More Ideas Beyond ICON?
If the ICON story has sharpened your thinking, use that momentum to line up a broader watchlist. A few focused screens on Simply Wall St can quickly surface other stocks that fit the kind of profile you want to research next.
- If you care most about quality at a reasonable price, start with a shortlist of 39 high quality undervalued stocks that pair fundamentals with what could be appealing valuations.
- If steadier sleep matters more than big swings, consider a curated set of 29 resilient stocks with low risk scores that screen well on resilience and financial risk checks.
- If you want to hunt for future leaders early, scan through a hand picked pool of 19 high quality undiscovered gems that combine solid business traits with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com