


BioNTech (NasdaqGS:BNTX) has put fresh numbers on the table. Third quarter 2026 results showed a move back into profit and management lifted full year revenue guidance, a combination that often resets how investors look at the stock.
BioNTech’s latest guidance hike and return to profit come against a tougher share price backdrop, with the stock down 9.49% on a year to date share price basis and the 1 year total shareholder return declining 15.15%, while the 5 year total shareholder return is down 62.90%. This suggests sentiment is still rebuilding despite the near term earnings improvement and pipeline updates.
Scan BioNTech alongside other beaten down healthcare opportunities by working through our curated list of 39 high quality undervalued stocks that currently pair solid fundamentals with discounted prices.
The gap between BioNTech’s €1,700 million to €1,900 million guidance range, consensus targets near $116, and an $87.51 share price is now in sharp focus. Where does a reasonable fair value anchor for this rebound actually land?
Most Popular Narrative: 25% Undervalued
BioNTech’s most followed valuation thesis places fair value near $116, which sits well above the recent $87.51 close. The hinge question becomes whether the oncology plan and cost cuts really earn that gap.
Expansion of BioNTech’s late stage oncology pipeline, including pumitamig, gotistobart and multiple ADCs such as T PAM and elfetabart drozuntecan, increases the chance of future product approvals that could add new revenue streams and support earnings over time.
Advancement of ADC assets such as T PAM, which is already in a confirmatory Phase III trial in endometrial cancer, and elfetabart drozuntecan, now in Phase III in metastatic castration resistant prostate cancer, adds further shots on goal that could contribute to medium term revenue and margin expansion if successful.
See why 72 investors see BioNTech as 25% undervalued.
Result: Fair Value of $116.76 (UNDERVALUED)
Still, this BioNTech story can crack if pumitamig stumbles in Phase III or COVID 19 demand weakens further and oncology assets do not fill the gap.
Find out about the key risks to this BioNTech narrative.
Another View: What BioNTech’s P/S Ratio Is Telling You
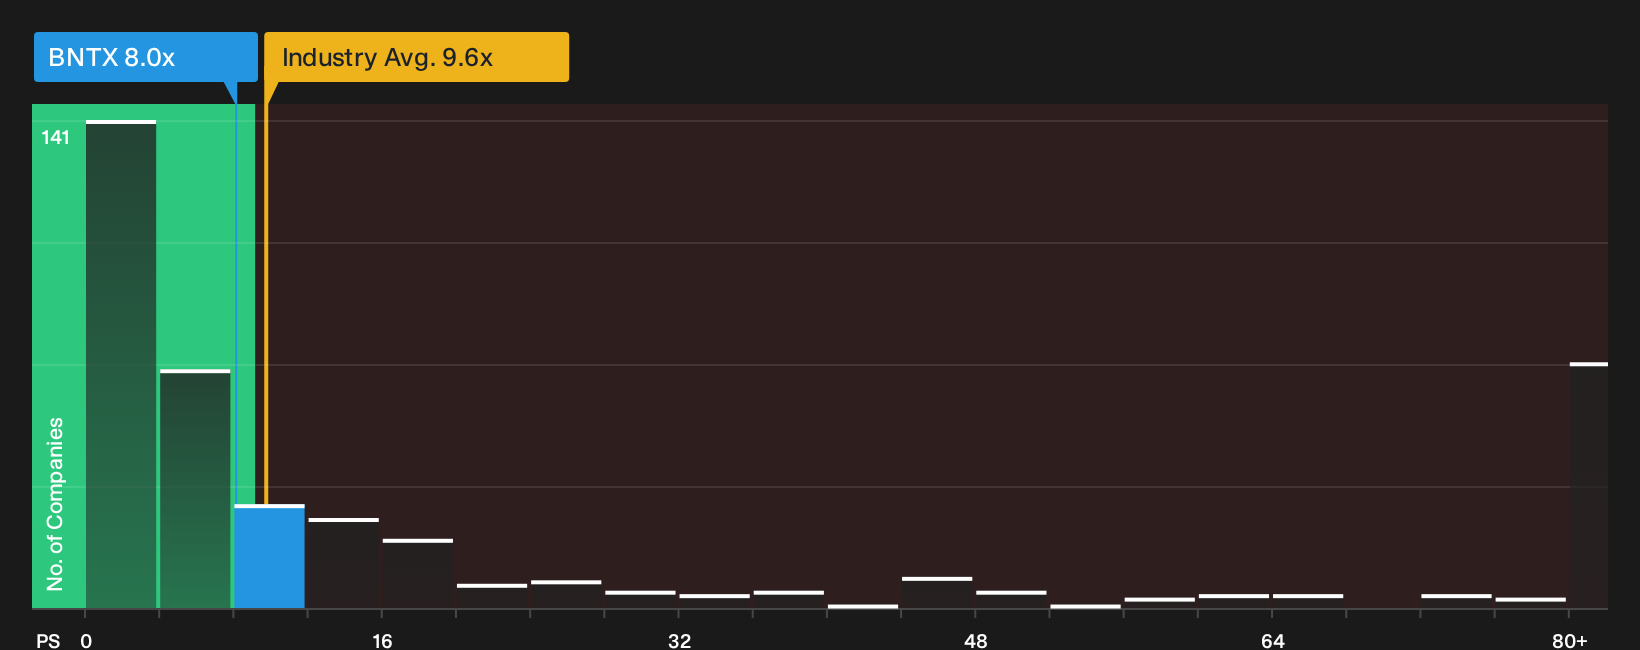
The first BioNTech narrative leans on analyst earnings forecasts and a $116.76 fair value, which implies the stock looks undervalued. A different lens uses its P/S ratio of 8x, which is higher than the peer average of 5.5x and even above a 7.2x fair ratio estimate.
That gap suggests investors are already paying a richer price tag for each dollar of BioNTech revenue, even though the stock has fallen over 60% on a 5 year basis and the business is still loss making. The real question is whether the oncology pivot and cost cuts eventually grow into that premium or force the valuation closer to the fair ratio.
See what the numbers say about this price, then find out in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Looking For More BioNTech Investment Ideas?
If BioNTech has your attention, do not stop here. Fresh opportunities sit across sectors and styles, and the screener helps you surface them quickly.
- Target income first by scanning a curated set of reliable payers using the 8 dividend fortresses.
- Hunt for quality at a discount and let the 19 high quality undiscovered gems highlight stocks with strong fundamentals that the crowd has not rushed into yet.
- Prioritise resilience by filtering for companies with sturdier finances through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com