


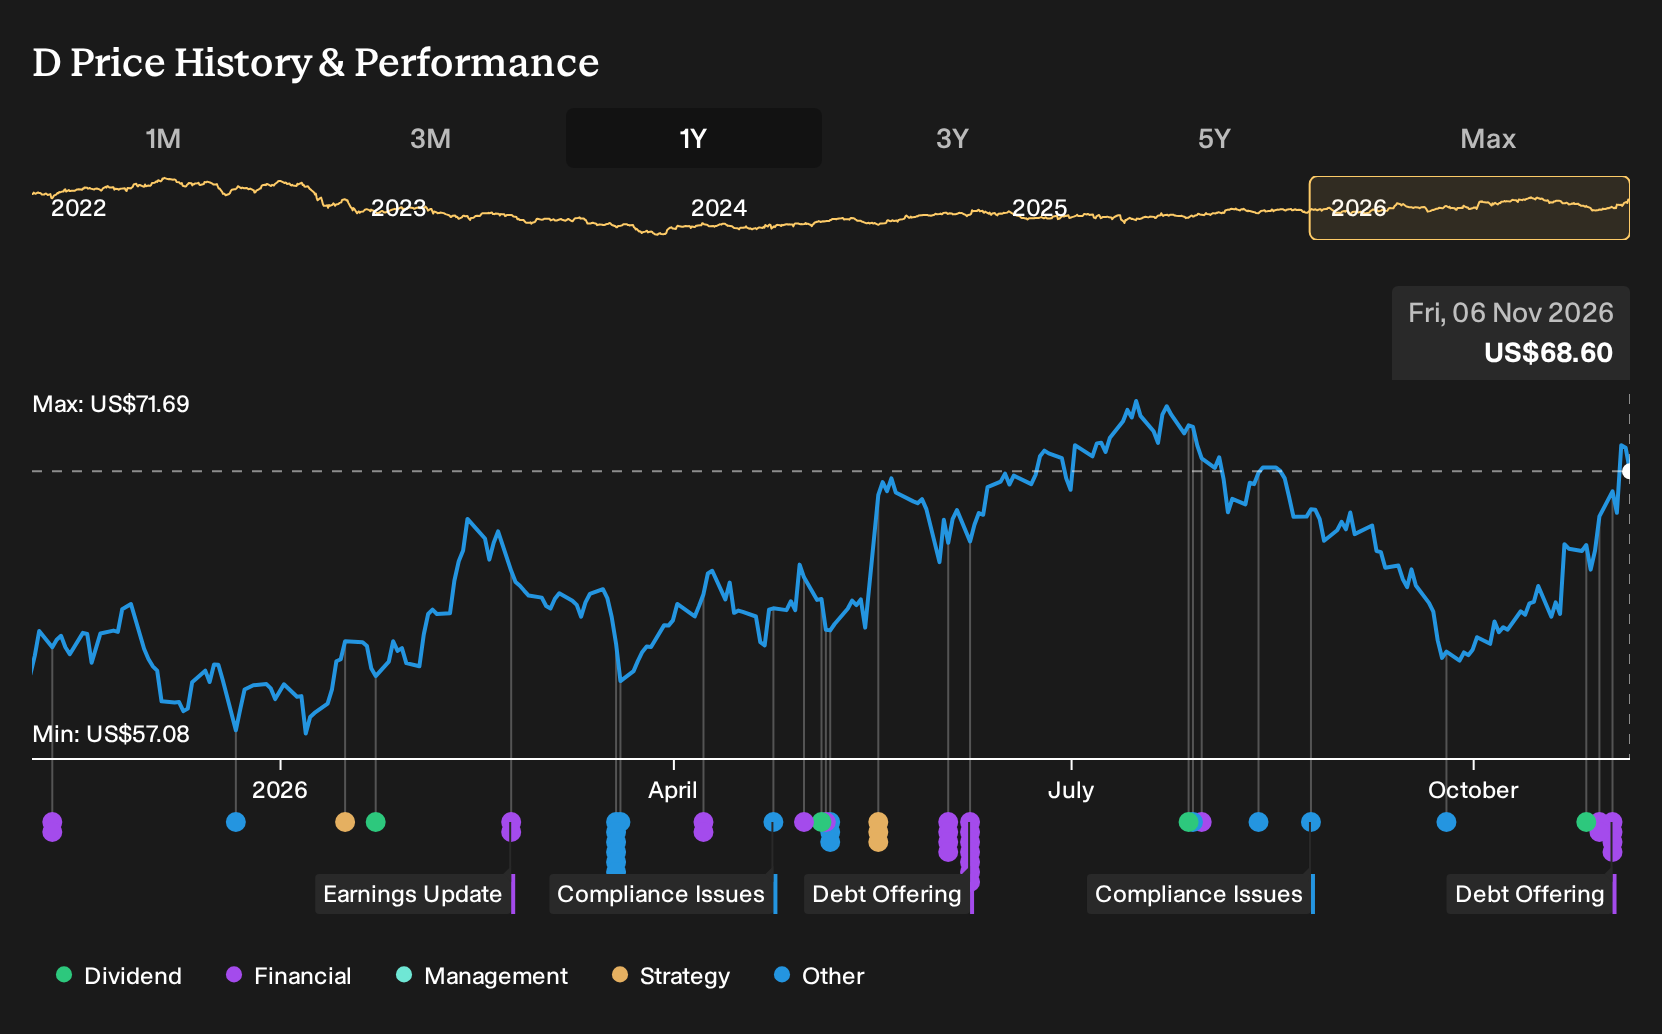
- Dominion Energy reported third quarter 2026 sales of US$5,617 million and net income of US$1,160 million, and reaffirmed full year operating earnings, credit, dividend and long term growth guidance after the period closed.
- The utility also issued and completed callable senior unsecured fixed rate notes maturing in 2029 and 2037, adding fresh long dated capital to support its regulated and clean energy investment program.
- We will examine how Dominion Energy's reaffirmed earnings guidance shapes the investment narrative around its regulated and renewables-focused strategy.
Compare Dominion Energy's latest bond funded build out with other regulated utilities and income ideas by scanning our hand picked 42 power grid technology and infrastructure stocks benefiting from long lived grid and infrastructure spending.
Dominion Energy Investment Narrative Recap
To own Dominion Energy, you need to be comfortable with a utility that leans heavily on massive, long lived projects and a busy capital plan. The story hinges on constructive regulators, timely execution of the Coastal Virginia Offshore Wind build and steady data center driven demand. The recent bond issues extend funding for that pipeline and, by themselves, do not change the near term earnings narrative.
The biggest short term swing factor is still how regulators handle cost recovery for offshore wind, new gas capacity and grid upgrades. Extra leverage and interest costs from new notes add to the existing concern that interest payments are not well covered by earnings, so overruns or delays would bite a little harder.
The most relevant recent update is Dominion Energy’s reaffirmed 2026 operating earnings guidance and commitment to existing credit and dividend plans. That signal matters more for shareholders than the individual bond coupons, because it frames how management sees the balance between heavy capex, financing needs and shareholder distributions.
In that context, the new 5.25% notes due 2029 and 5.95% notes due 2037 appear to be tools to lock in long term funding against an almost US$65b capital plan through 2030. For you as an investor, the key question is whether these projects, including Coastal Virginia Offshore Wind and new gas plants, enter rate base on time and on budget so that this extra debt supports, rather than strains, future cash flows.
Dominion Energy's current analyst narrative points to revenues of US$21.5b and earnings of US$4.0b by 2029, based on an assumed 5.8% yearly revenue growth rate. That profile implies earnings today of about US$2.5b would need to rise by roughly US$1.5b to meet the consensus forecast for 2029.
Uncover why Dominion Energy's fair value indicates that Dominion Energy is roughly in line with its current price.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$70 to about US$175 per share, so community views on Dominion Energy’s worth are wide apart. That spread sits against factors such as a US$65b capital plan and data center load growth, as well as risks around project delays and merger scrutiny. Investors can expect differing opinions and may wish to use these contrasting views as a prompt to explore multiple scenarios before committing fresh capital.
Explore another Dominion Energy fair value estimate, including one that suggests as much as 155% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Dominion Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Dominion Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dominion Energy's overall financial health at a glance.
Looking for more investment ideas beyond Dominion Energy?
Once you have formed a view on Dominion Energy, it can help to compare it with other businesses that share some of the same qualities you care about, whether that is income resilience, balance sheet strength or the potential for mispriced opportunities.
- For investors focused on income resilience with meaningful yield, take a look at stocks in our 8 dividend fortresses that align defensive cash flows with substantial payouts.
- If capital preservation and steadier risk profiles are higher on your list, consider companies highlighted in the 29 resilient stocks with low risk scores to see which balance sheets and earnings streams screen as more resilient.
- For readers hunting for potential mispriced opportunities with solid fundamentals, scan the 19 high quality undiscovered gems that may not yet be widely followed but still clear quality hurdles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com