


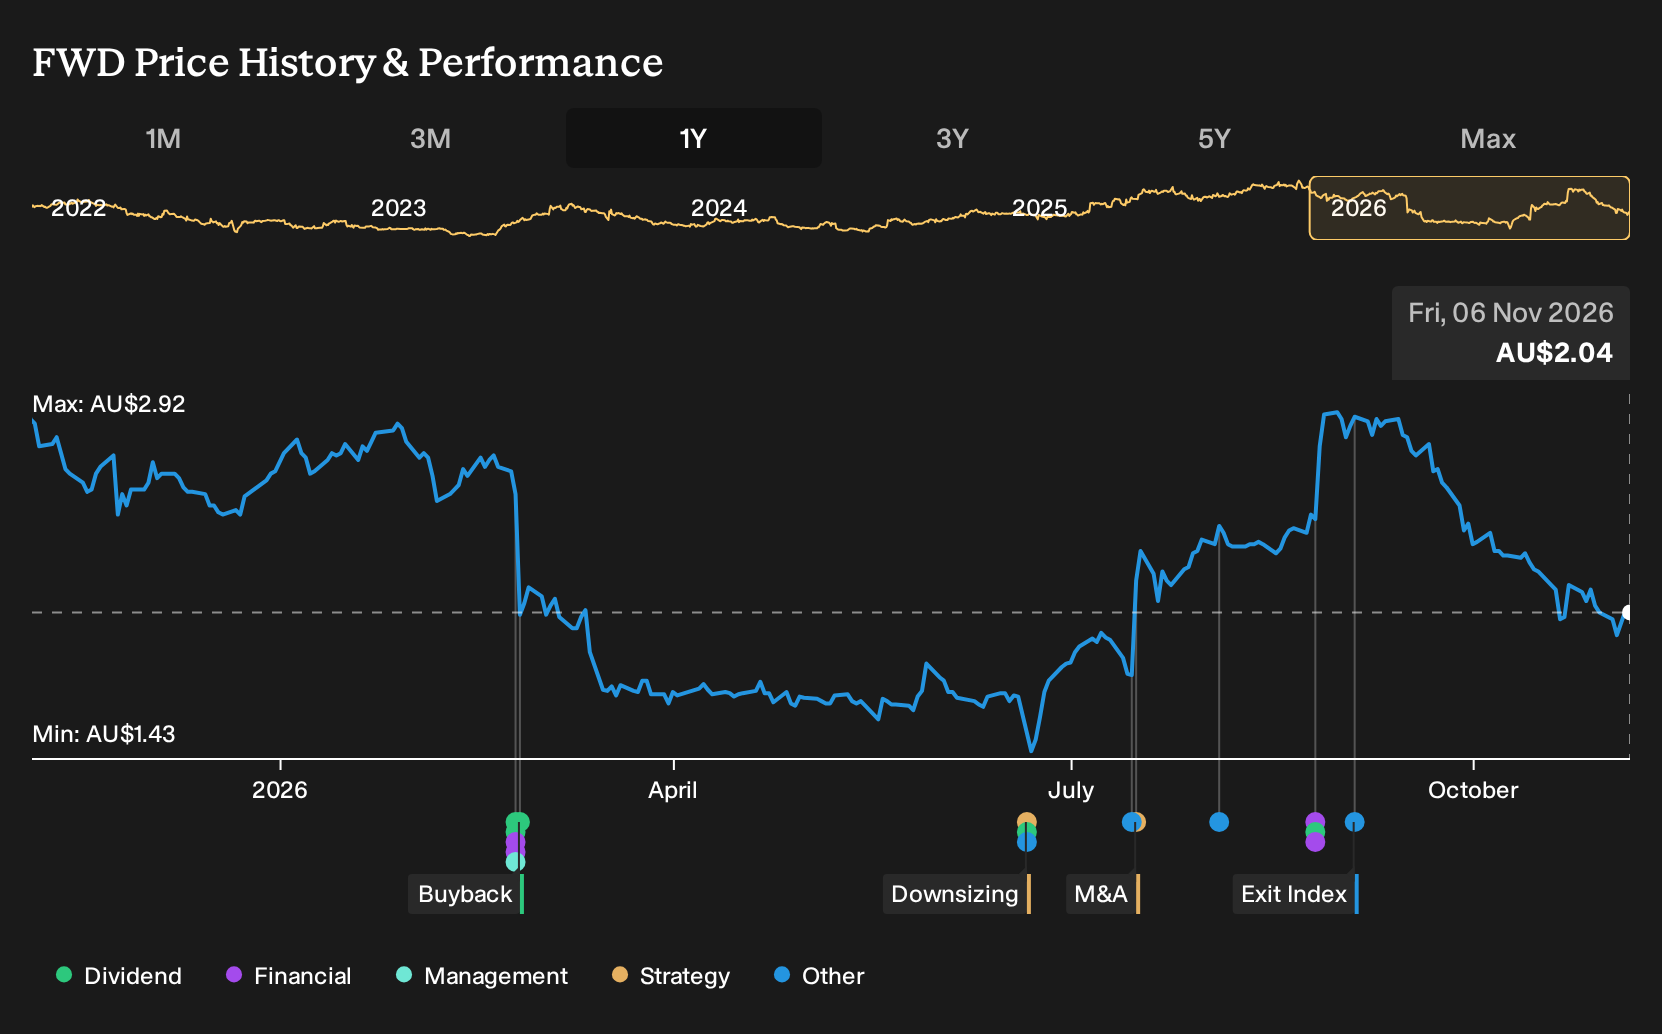
If you backed Fleetwood for its modular housing story and growing government work panels, the past year has been bruising. Holding Fleetwood over the past year would have meant a 20.0% loss, including dividends. If you had been weighing up an investment on 6 November 2025, you would have seen bullish expectations for higher margins, mid single digit revenue growth and a lower future P/E. Which of those specific assumptions about Building Solutions, Community Solutions and RV Solutions proved too optimistic, and which still look intact?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Fleetwood has already moved. See which of 4 high quality undervalued stocks still trade below our estimates.
The Two Fleetwood Stories Investors Had To Weigh
The shares cost A$2.87 at the start of the period, and anyone looking at Fleetwood then had to choose between two very different but reasonable stories.
The bullish narrative put fair value at A$3.46 and focused on modular housing. It assumed 3.4% annual revenue growth and profit margins rising to 5.9%, supported by deeper government panels and higher repeat work.
The cautious view set fair value at A$2.57. That case expected 2.0% revenue growth, a 4.4% margin, and saw heavy reliance on Pilbara projects and RV Solutions as key risks.
What The Results Changed For Fleetwood
The biggest development was Fleetwood’s FY26 shift away from RV Solutions, with a full exit and closure of the Smithfield plant, which backed the cautious case that saw RV as a drag. At the same time, H2 2026 revenue of A$245.5m was higher than H2 2025, yet profit moved to a loss and net margin fell from 4.3% to 2.5%. The evidence cut both ways.
The key lesson is to separate volume from quality. When you see a thesis built on margin expansion, track the reported net margin and segment exits, not just headline revenue or contract wins.
What Fleetwood's Lower Price Now Asks You To Believe
Fleetwood now trades at A$2.04, and the selected Narrative argues that its Fair Value sits above that level, with the balance sheet and cash generation doing more heavy lifting than the share price gives credit for.
The core assumption you would be testing at this price is that Community Solutions and Building Solutions can fill key villages and lift earnings without fresh contract missteps.
"The current numbers, including A$35.6 million of underlying EBIT, A$35.9 million of free cash flow, A$61.5 million of cash with no debt, ongoing dividends and buybacks, and guidance for Building Solutions to move to at least breakeven EBIT in 1H FY27, imply the share price treats Fleetwood as a business with weaker long-term earnings power than these metrics suggest."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Find Your Own Contrarian Opportunity
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 30% below our estimate - sells bundled electronics and appliances through paired physical stores and integrated online channels.
- Company 2 - 29% below our estimate - supplies replacement truck and bus parts while interpreting complex component needs for fleet operators.
- Company 3 - 19% below our estimate - delivers enterprise cloud, security and AI projects alongside long running software and hardware contracts.
That is three of the list. See all 12 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com