


DENTSPLY SIRONA has had a tough share price run in recent years, so the live question now is whether the current US$9.46 level still makes sense when you line it up against the sales the business is generating. With the spotlight on governance and long term shareholder outcomes, a sales based lens can help you decide how much of the story is already baked into the quote.
- Over the past 5 years the stock has fallen 80.9%, which puts the focus firmly on whether the present valuation can still be anchored to the revenue base.
- Investor rights law firm scrutiny of potential fiduciary duty breaches at DENTSPLY SIRONA may influence how investors think about future cash deployment and the reliability of sales driven valuation assumptions.
- There is a second opinion on DENTSPLY SIRONA worth weighing. See what analysts think DENTSPLY SIRONA's shares could be worth.
The stock's next move may depend on whether today’s price can be explained by what DENTSPLY SIRONA generates in sales and what investors are willing to pay for each dollar of that revenue.
If you want to pressure test whether DENTSPLY SIRONA's sales based pricing question shows up elsewhere in healthcare, compare it with a wider group using the solid balance sheet and fundamentals stocks screener (24 results)
Does DENTSPLY SIRONA Look Undervalued on Sales?
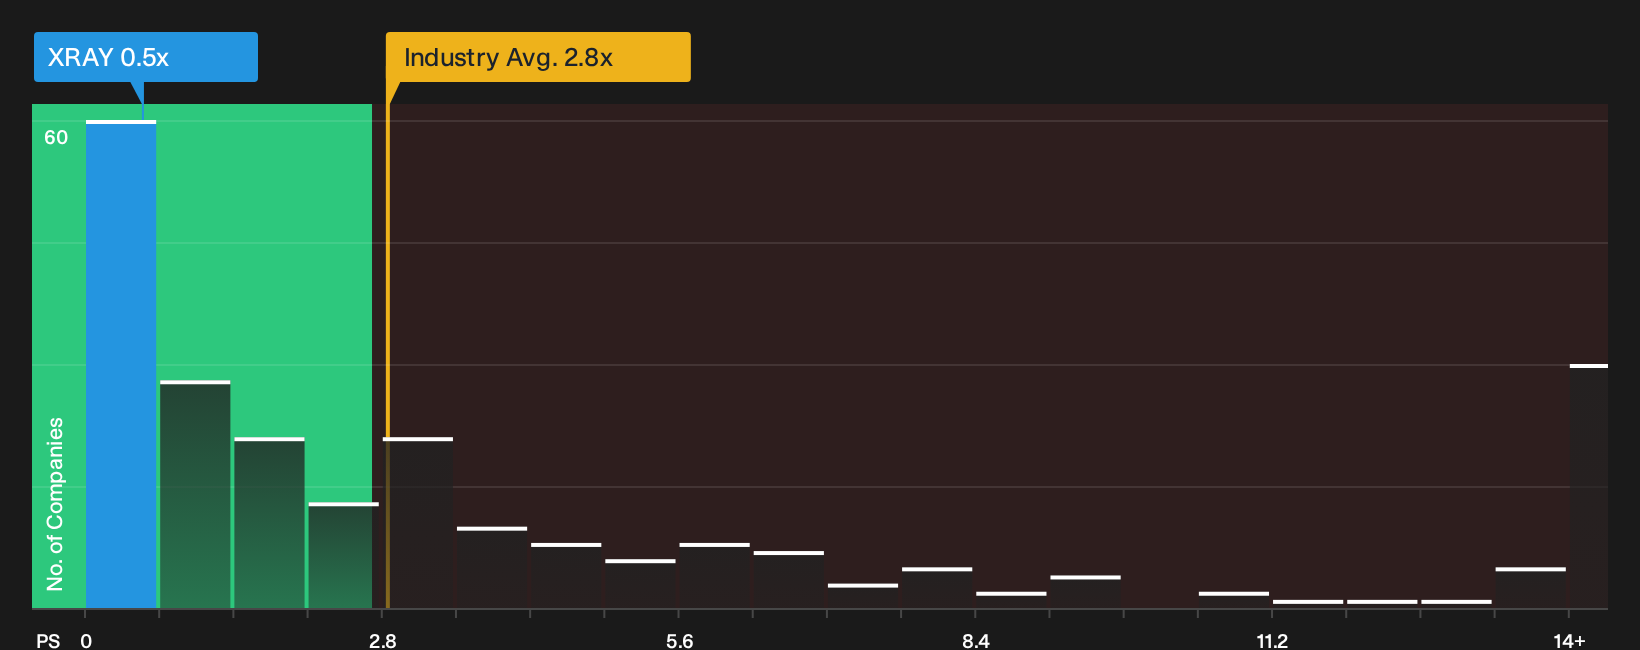
A price-to-sales (P/S) ratio suits DENTSPLY SIRONA because it ties the share price directly to the revenue base in a way that is less distorted by near-term earnings variability. On that yardstick, the stock trades on a P/S of 0.5x, which is well below the broader medical equipment industry on 2.8x and also below the closer peer set on 4.5x. In other words, the market is paying less for each dollar of DENTSPLY SIRONA sales than for many comparable businesses.
Because the fair ratio adjusts for factors such as margins, scale and risk, it indicates where the P/S might be if the company were priced more in line with its fundamentals. The current 0.5x stands below that tailored benchmark, which indicates that the shares screen as undervalued on this measure. Despite the ongoing investigation into potential fiduciary duty breaches, the market multiple still prices DENTSPLY SIRONA at a discount to peers on revenue terms. Explore the numbers behind DENTSPLY SIRONA's P/S valuation.
The DENTSPLY SIRONA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S puzzle for DENTSPLY SIRONA leaves off by spelling out which paths for revenue, margins and earnings would need to play out for the stock to be worth materially more or materially less than today’s price. Instead of a single ratio or model output, you see the specific future that number rests on and can judge over time whether that path still looks realistic.
Community views on DENTSPLY SIRONA are split between those who see a durable, underappreciated franchise and those who think recent pressure already explains the current price.
Bull case: 79% undervalued
"One of XRAY’s strengths is its consumables portfolio, products that practices reorder regularly regardless of capital spending cycles…"
Discover why this Narrative puts DENTSPLY SIRONA at 79% undervalued.
Bear case: 5% overvalued
"Although DENTSPLY SIRONA is investing more in R&D and clinical education under its 24 month Return to Growth Action Plan, the company has yet to show that these higher costs can reverse an average 5.7% constant currency revenue decline over the last two years…"
Explore why this Narrative puts DENTSPLY SIRONA at 5% overvalued.
Before you log off, one more DENTSPLY SIRONA check belongs beside the price charts
Who sits in the key seats at DENTSPLY SIRONA and how their pay packets line up with your interests can tilt the whole investment case, so it is worth seeing that picture next. See who runs DENTSPLY SIRONA and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com