


Fresh trial readouts on diranersen and longer term lecanemab data at the Clinical Trials on Alzheimer’s Disease Conference have pushed Biogen (BIIB) back into focus for many investors.
That backdrop helps explain why Biogen’s recent Alzheimer’s news has landed on a stock that already has momentum. The company has a 30-day share price return of 11.79% and a year to date share price gain of 39.66%. Meanwhile, the 1-year total shareholder return of 59.70% suggests investors have been rewarding the story over a longer stretch, even as the 5-year total shareholder return of an 8.16% loss shows how much of this enthusiasm is relatively recent.
Scan how Biogen’s Alzheimer’s progress compares with other high quality healthcare names by jumping into our hand picked 35 healthcare AI stocks that are riding similar treatment and data catalysts.
Biogen’s surge on Alzheimer’s headlines sets up a sharper question. After a near 60% 1 year total return, does the current valuation still indicate meaningful potential, or has the move already done most of the work?
Most Popular Narrative: 2% Undervalued
Biogen’s most followed valuation narrative pegs fair value at $253.39, only a touch above the latest $248.35 close. This frames recent Alzheimer’s optimism against relatively tight upside implied by the model.
Growing uptake of Biogen’s multi-product growth portfolio, which generated over US$1b of revenue in Q2 2026 and has now exceeded the multiple sclerosis portfolio, supports the idea that a broader base of neurology and immunology brands can increasingly carry total revenue and help stabilise earnings.
See why 63 investors see Biogen as 2% undervalued.
Result: Fair Value of $253.39 (ABOUT RIGHT)
Still, Biogen’s story can change quickly if multiple sclerosis erosion deepens or if key launches like LEQEMBI, SKYCLARYS or ZURZUVAE fall short of analyst assumptions.
Find out about the key risks to this Biogen narrative.
Another View: Biogen On Earnings-Based Valuation
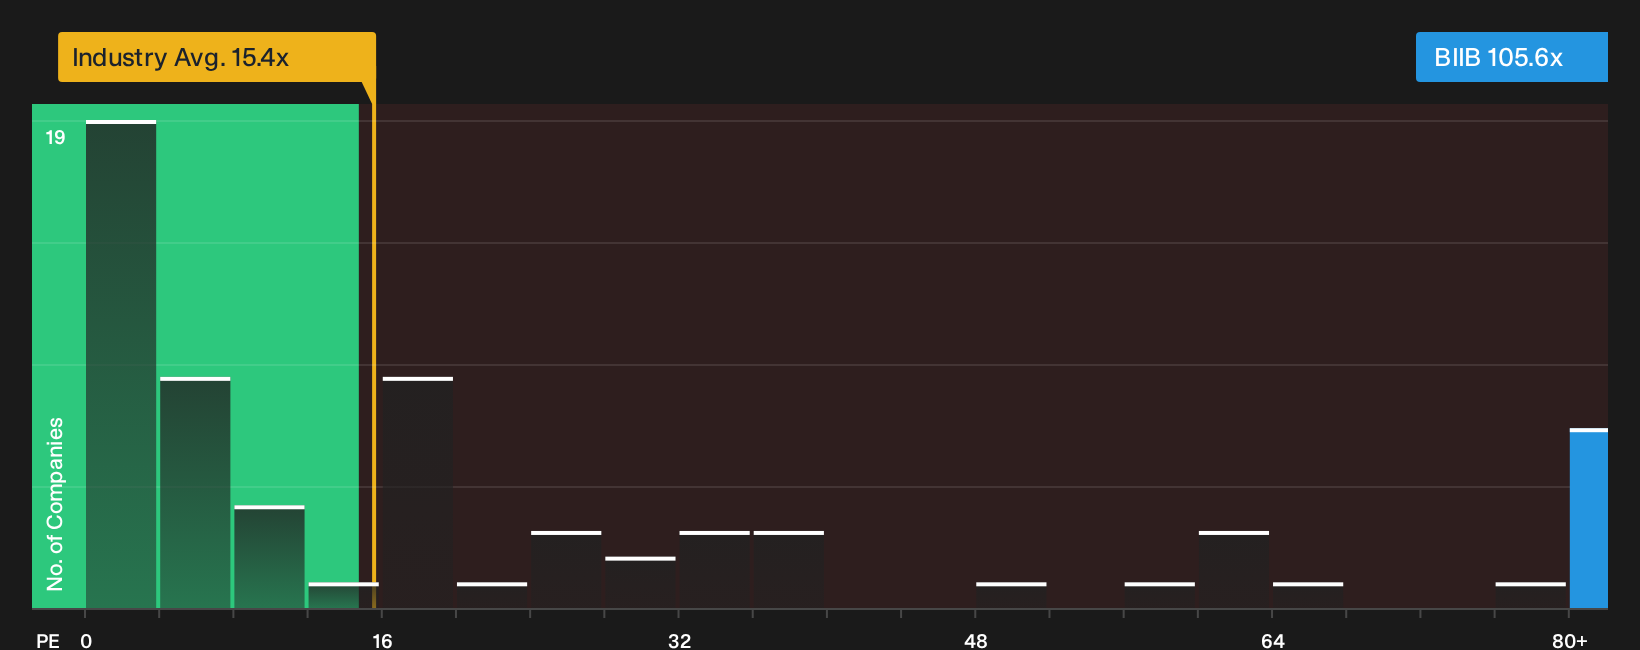
Fair value models and narratives suggest Biogen is only slightly undervalued. The picture looks very different when you focus on the P/E ratio. The stock trades at about 105.6x earnings, compared with a fair ratio of 37.5x and a US Biotechs average of 16.9x.
That gap means investors today are paying a much richer price for each dollar of profit than both peers and the level our fair ratio suggests the market could move toward over time. The question is whether you see that as valuation risk you want to step away from, or a premium you are comfortable paying for Biogen specifically.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
With sentiment split between premium risks and growth potential, you should move fast and pressure test the story against the hard numbers. Start by weighing Biogen’s 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Biogen?
Do not stop with Biogen. Broaden your watchlist now by using focused screeners that surface different types of opportunities other investors may be missing.
- Target quality at a discount by scanning a curated 39 high quality undervalued stocks with strong fundamentals already filtered for you.
- Prioritise resilience and sleep easier at night by reviewing a 29 resilient stocks with low risk scores built around sturdier business profiles.
- Hunt for future leaders before the crowd catches on by running through a 19 high quality undiscovered gems that highlights under followed candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com