


PPL (PPL) just paired a third quarter earnings beat with a higher long term EPS growth target of 7% to 9% through at least 2030, supported by a larger capital plan and a new renewable partnership.
Recent trading tells a mixed story. PPL’s 30 day share price return of 5.45% suggests momentum has picked up into the earnings release, while the 1 year total shareholder return of 1.03% and 5 year total shareholder return of 48.84% point to a steadier long run compounding profile that investors are weighing against the larger capital plan and higher growth ambitions.
Scan how PPL’s renewed growth ambitions compare with other regulated utilities and grid plays by reviewing our curated list of 42 power grid technology and infrastructure stocks
Bulls see PPL’s earnings beat and larger grid buildout as proof the higher growth bar holds. Bears focus on execution risk and capital intensity. Which side does today’s valuation favor?
Most Popular PPL Narrative: 10.8% Undervalued
PPL last closed at $35.80, while the most followed narrative pegs fair value at $40.13 using a 7.24% discount rate and a detailed earnings path through 2029.
The accelerating growth in data center construction and new economic development, now supported by roughly 32 GW of advanced stage projects in Pennsylvania and a 13.7 GW pipeline in Kentucky, continues to point to sizable future load additions for PPL that are expected to require more infrastructure and support higher regulated revenue over time.
See why 19 investors see PPL as 11% undervalued.
Result: Fair Value of $40.13 (UNDERVALUED)
Still, the bullish PPL narrative leans heavily on constructive regulators and on large data center customers following through. Either pillar cracking could quickly shake that story.
Find out about the key risks to this PPL narrative.
Another View On PPL’s Valuation
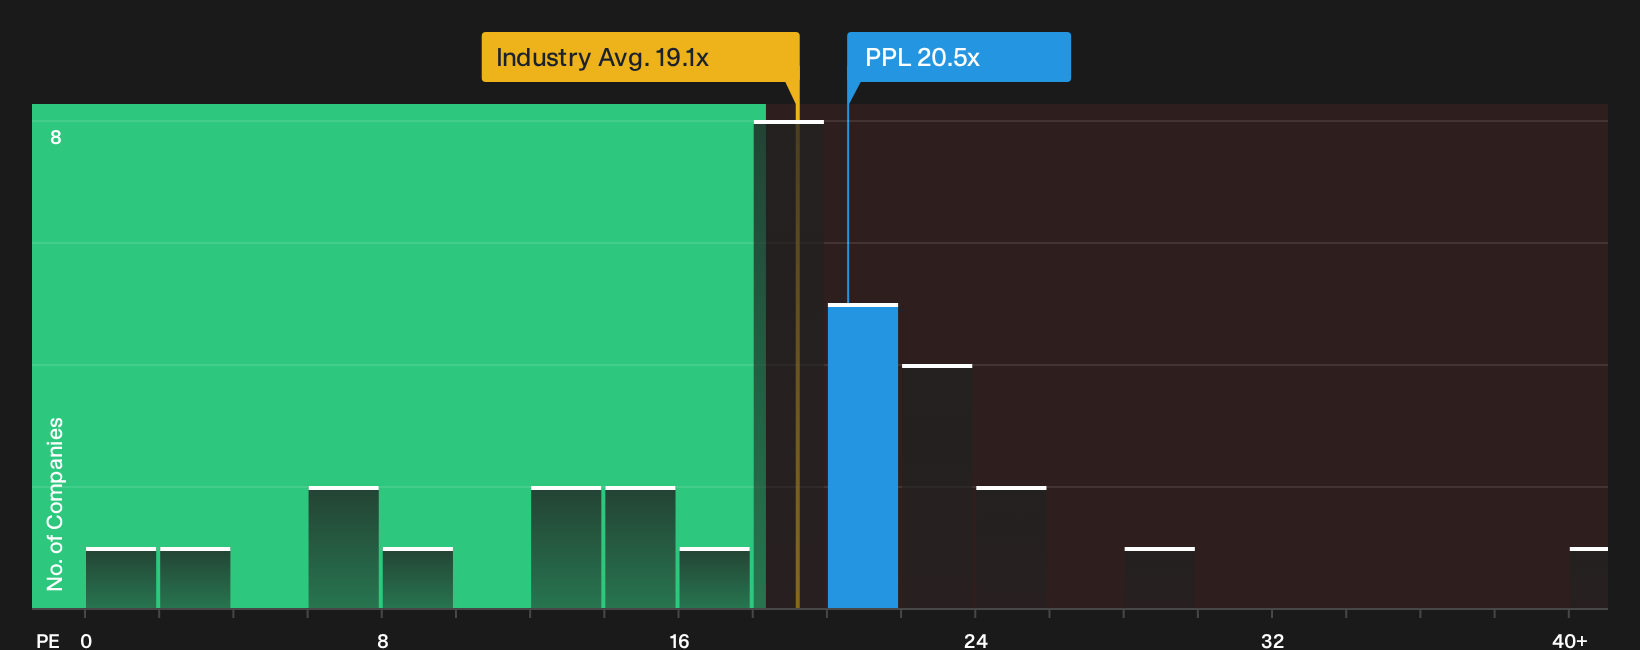
The fair value narrative around PPL leans on a detailed earnings path and discounting those cash flows. A different lens comes from today’s P/E of 20.5x, which sits above both peers at 14.2x and the US Electric Utilities industry at 19.5x.
That premium is partly offset by an estimated fair ratio of 22.3x, which sits higher than the current multiple and suggests the market could move toward that level instead of away from it. For anyone weighing the story, does paying above peers but below the fair ratio feel like risk or room for re rating?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on PPL’s outlook can be useful if you test them against your own expectations. Spend a few minutes with the underlying data, then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond PPL?
If PPL has sharpened your focus on regulated utilities and grid growth, it is worth lining up a few fresh ideas before the next catalyst hits.
- Target steadier opportunities by scanning a 29 resilient stocks with low risk scores that could cushion your portfolio when volatility spikes.
- Spot potential bargains early by reviewing a 19 high quality undiscovered gems before they reach every watchlist on the market.
- Prioritize financial resilience by filtering for a list of solid balance sheet and fundamentals (24 results) so you are not caught holding fragile businesses when conditions tighten.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com