


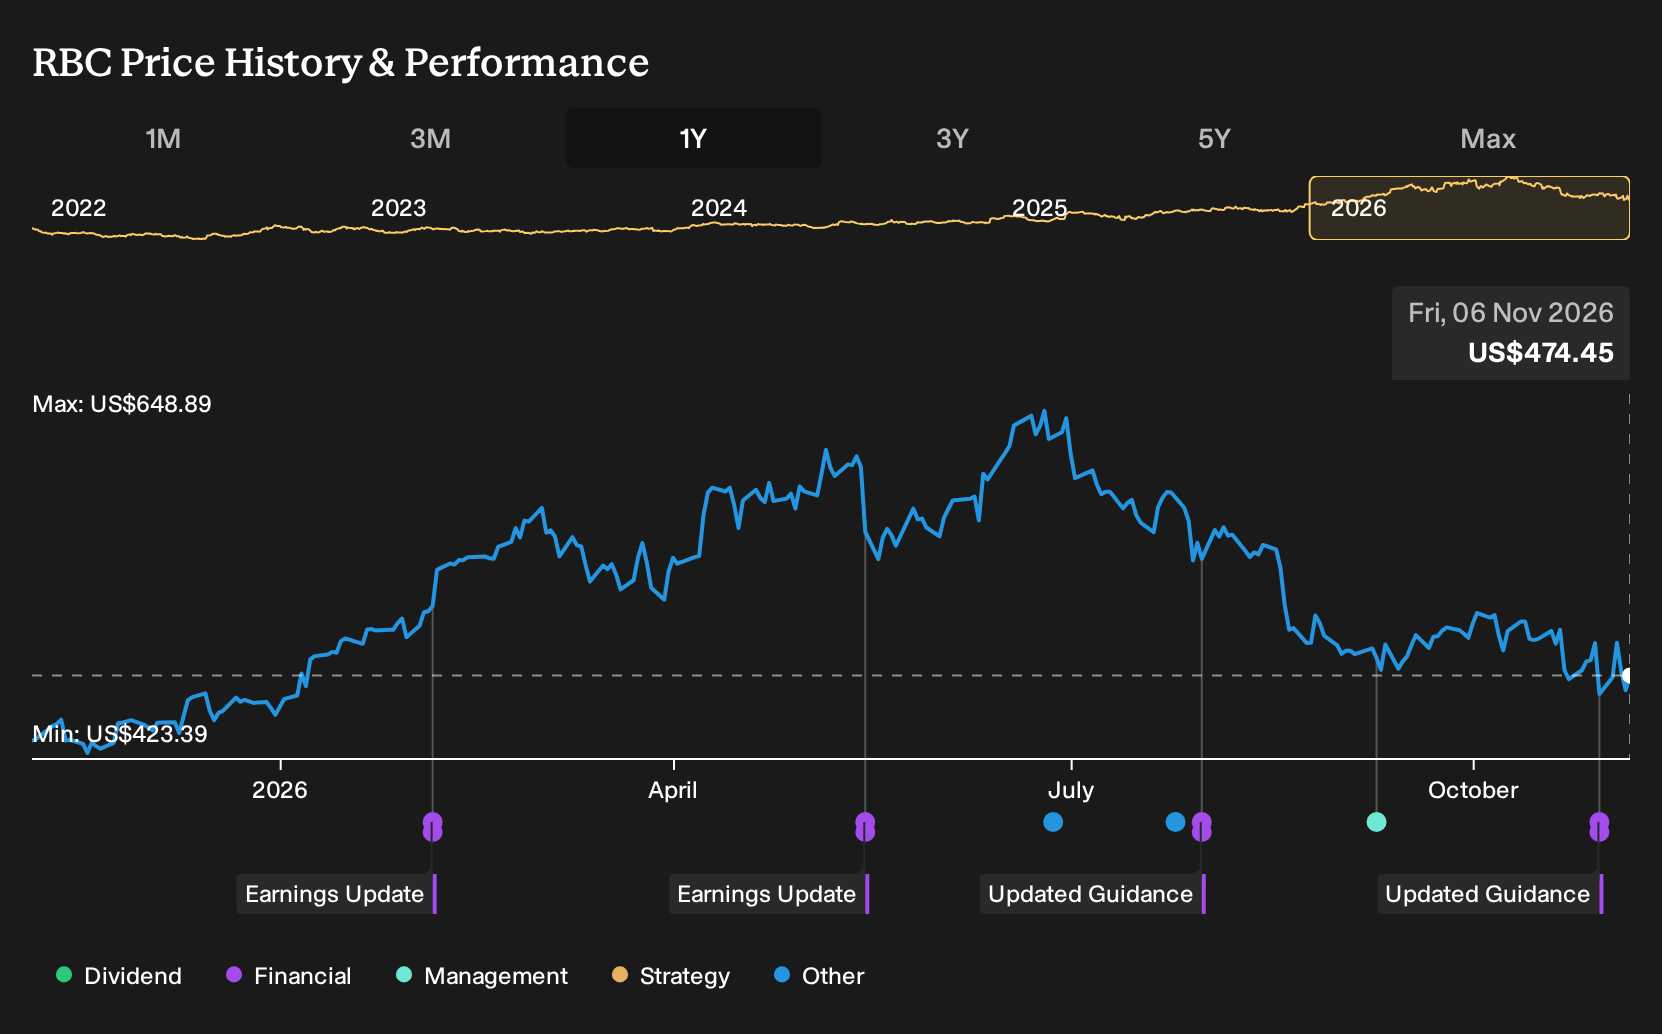
- RBC Bearings reported second quarter 2026 results with sales of US$524.6 million and net income of US$93.8 million, and issued third quarter fiscal 2027 net sales guidance of US$520 million to US$525 million, both described as showing double digit year on year growth compared with the prior periods.
- The business paired higher sales with stronger earnings per share, as diluted EPS from continuing operations reached US$2.96 for the quarter and US$6.16 for the first half. This suggests that operating leverage and cost control played a key role in the recent performance.
- Next, the focus turns to how this EPS acceleration at RBC Bearings might influence the broader investment narrative that investors are tracking.
Scan how RBC Bearings’ latest guidance compares with industrial peers by running the same earnings and balance sheet filters across our curated list of solid balance sheet and fundamentals (24 results)
What Is RBC Bearings' Investment Narrative?
To own RBC Bearings, you need to be comfortable with a straightforward story. This is an engineered components business that lives or dies on execution, pricing discipline, and capital deployment. The latest quarter, with US$524.6 million of sales and US$93.8 million of net income, backs up that narrative with clear operating leverage and firmer margins. Management’s third quarter fiscal 2027 sales outlook of US$520 million to US$525 million signals that recent demand conditions, particularly in aerospace and industrial, still support a healthy order book in the near term.
The real swing factors now sit in how consistently RBC Bearings can convert that demand into earnings while running an asset heavy footprint. Higher EPS for both the quarter and first half hints that cost control and pricing are working in the company’s favor, at least for now. In the short term, the guidance update becomes a key reference point for whether this acceleration is becoming the new baseline or just a strong stretch. With the stock already carrying a P/E well above peer and fair value estimates, execution against this guidance matters more than any headline about analyst targets.
Even so, there is a less comfortable side to the RBC Bearings story that starts to show up when you look closely at...
There's only one way to know the right time to buy, sell or hold RBC Bearings. Head to Simply Wall St's company report for the latest analysis of RBC Bearings's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide band, from about US$316 to roughly US$609, so you are seeing private investors placing RBC Bearings in very different camps. Those views were set before the latest guidance and earnings release, which gives you one more reason to compare multiple opinions before acting.
Explore another RBC Bearings fair value estimate, including one that suggests up to 28% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your RBC Bearings research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for RBC Bearings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RBC Bearings' overall financial health at a glance.
Looking For More Investment Ideas Beyond RBC Bearings?
If the latest numbers from RBC Bearings have sharpened your focus on quality and risk, it can help to scan a broader watchlist built on the same kind of fundamentals driven filters.
- For investors who want income with staying power, review companies that meet strict payout and balance sheet checks through our 8 dividend fortresses.
- If capital protection is front of mind, narrow the field to businesses with steadier financial profiles by running the 29 resilient stocks with low risk scores.
- When you are hunting for underappreciated opportunities, cast a wider net over fundamentally strong stocks trading below their implied worth with the 39 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com