


Whirlpool earnings reset: what the latest loss and guidance mean
Whirlpool (WHR) just posted a quarterly net loss alongside lower sales, then followed up with full year guidance that points to slightly softer revenue and a negative earnings margin for 2026.
Whirlpool’s 1 day share price return of 3.17% and 90 day share price decline of 29.44% frame a stock that has been repricing sharply as earnings pressure builds, while the 1 year total shareholder return of 53.63% and 5 year total shareholder return of 83.21% point to longer running concerns rather than a short term wobble.
Scan beyond Whirlpool and compare this reset story with other consumer-focused businesses on our hand-picked list of 39 high quality undervalued stocks.
Bulls see Whirlpool as already punished for weak results, while bears point to fresh losses and guidance that still paints a tough picture. Which story do the current valuation markers back up next?
Most Popular Narrative: 17% Undervalued
Whirlpool’s most followed narrative pegs fair value at about $36.73 a share versus a last close of $30.54. This points to a gap the story tries to explain through cost cuts, product mix, and balance sheet repair.
The main requirement is successful execution of the multi year factory consolidation, automation, and logistics footprint changes that are expected to deliver at least $150 million of 2026 cost savings and roughly $180 million or more of annualized EBIT benefits from 2027 onward.
These programs are central to the thesis that Whirlpool can rebuild profitability even if top line trends remain muted.
See why 30 investors see Whirlpool as 17% undervalued.
Result: Fair Value of $36.73 (UNDERVALUED)
Still, Whirlpool’s reliance on mature U.S. and European appliance markets, together with weaker North America volumes and heavier promotions, could easily undercut that recovery narrative.
Find out about the key risks to this Whirlpool narrative.
Another View: Whirlpool And The DCF Check
There is a sharp contrast when the SWS DCF model is brought into the picture. On that math, Whirlpool at $30.54 is trading above an estimated future cash flow value of $14.73, which points to an overvalued signal rather than the 17% undervalued story. Which lens do you trust more when cash flows carry most of the weight in the analysis?
Look into how the SWS DCF model arrives at its fair value.
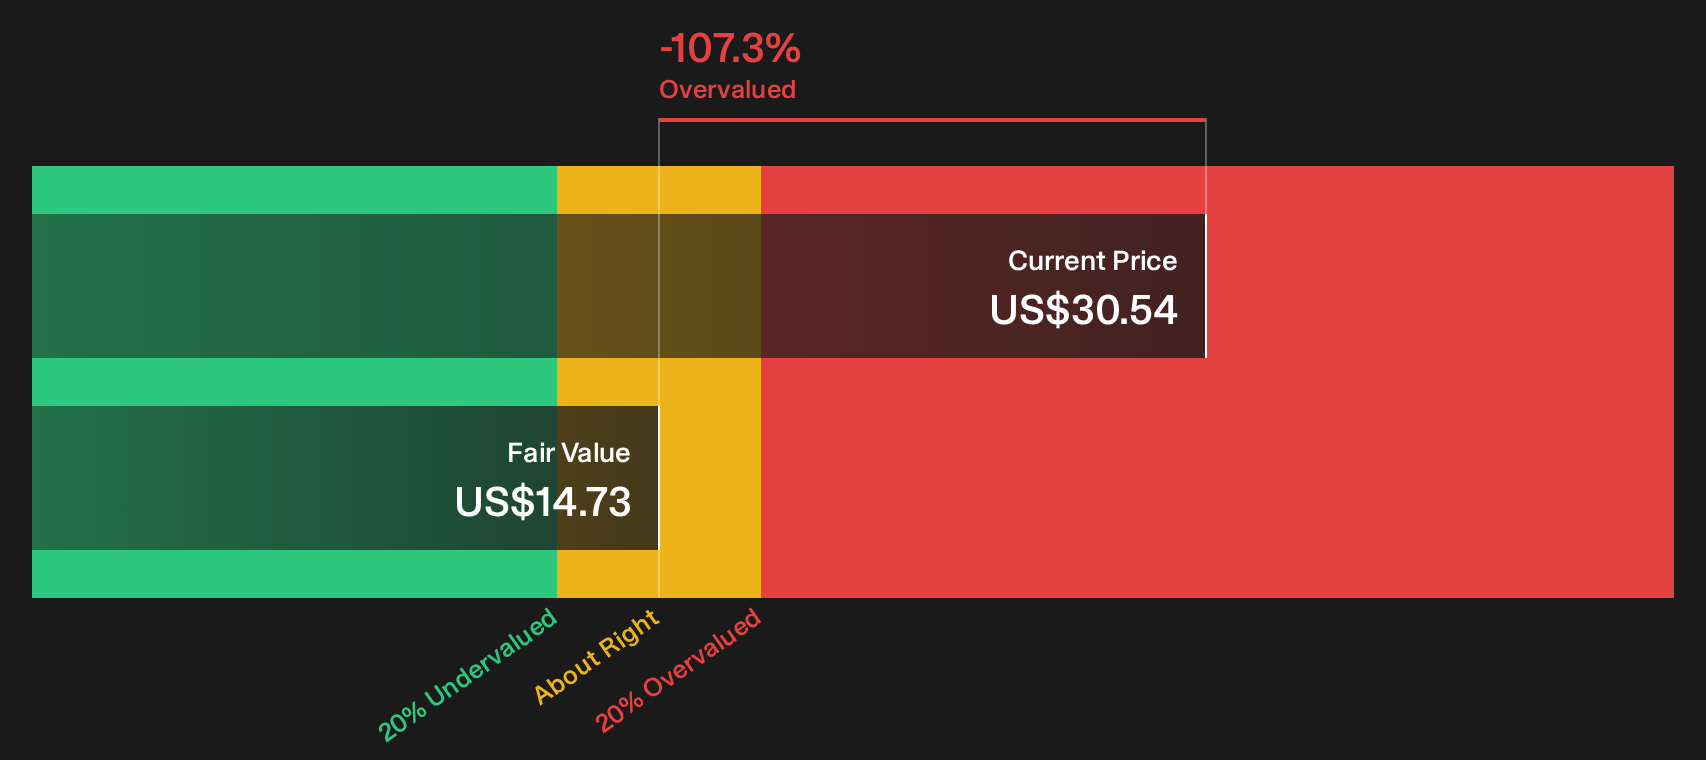
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Whirlpool for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Whirlpool can be confusing, so move quickly, review the numbers in detail, and stress test the story for yourself with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Whirlpool?
If Whirlpool has you rethinking your portfolio, use the Simply Wall Street Screener to quickly spot fresh opportunities before the crowd moves and the window closes.
- Target resilient income by scanning for reliable high yielders with our list of 8 dividend fortresses.
- Hunt for upside potential by checking companies that score well on quality and price through a focused 39 high quality undervalued stocks.
- Prioritise capital protection first and returns second by filtering for a 29 resilient stocks with low risk scores that aims to keep downside in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com