


Hot labor data and a Fed still focused on inflation have pushed interest rates back to center stage, and that reshapes where risk and reward sit in your portfolio. Banks and insurers can feel those rate moves quickly, for better or worse, which creates real opportunity for investors who pay attention instead of reacting late. This article unpacks three U.S. financial stocks exposed to the latest jobs report and rate expectations, showing how the same macro shock can ripple through each business in very different ways.
The stocks covered below are just a starter set from this rate sensitive theme, and the full screen surfaced 25 more U.S. banks and insurers with equally interesting stories that are not discussed in this article. To go straight to the full US Financials screener and identify which interest rate plays best fit your risk profile, analyze the US Financials – Banks and Insurance Benefiting from Rising Interest Rates screener.
Burke & Herbert Financial Services (BHRB)
Burke & Herbert Financial Services is a long established Alexandria based community bank holding company focused on retail and commercial customers. It earns all its US$393.7 million of revenue from community banking in the United States and has a market value of about US$1.4b.
Burke & Herbert Financial Services sits in this rising rate focused financials screen because its core business is classic spread banking. Loan income and deposit costs drive earnings, so higher policy rates can matter more here than for many peers. Investors get that rate sensitivity plus a 3.15% dividend yield and a P/E of 13.8x. What happens when credit costs move is the key pressure point to watch.
When rate moves begin to affect credit quality, the 3 key rewards and 3 important warning signs (1 is major!) can help you see where Burke & Herbert Financial Services might be mispriced on risk.
Farmers National Banc (FMNB)
Farmers National Banc is a Canfield based bank holding company that runs traditional lending, deposit, wealth, and insurance operations geared to interest rate sensitive net interest margins. It generates US$235 million of revenue in the United States and has a market value of about US$920 million.
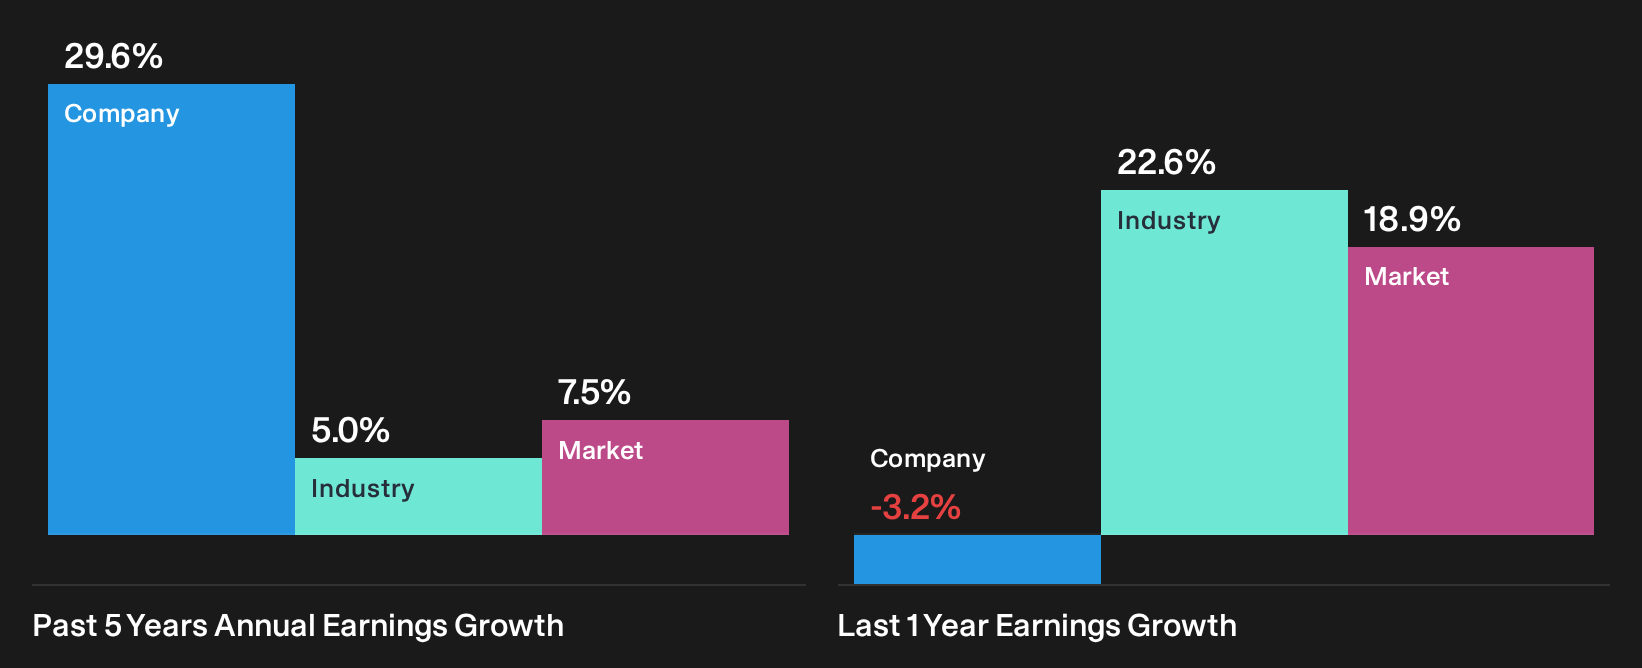
Farmers National Banc gives you a classic rate exposed regional bank story. Higher policy rates feed directly into loan yields and net interest income. Its 4.67% dividend and recent growth in net interest income and net income keep the income case alive, even as funding costs and credit losses quietly test how much margin improvement really sticks when conditions stay tight.
Those pressure points are exactly what the 4 key rewards and 1 important major warning sign surfaces, so you can see whether Farmers National Banc’s income story is masking future strain or extra upside.

Nicolet Bankshares (NIC)
Nicolet Bankshares runs a full service regional bank across Wisconsin, Michigan, and Minnesota, with US$580.8 million of consumer and commercial banking revenue that lives and dies by loan and deposit spreads. All of that income comes from the United States, and the business carries a market value of about US$3.6b.
Nicolet Bankshares sits in this rising rate focused screen because its earnings lean heavily on net interest margins, with recent results already showing higher net interest income and margin expansion as policy rates moved up. Investors get earnings growth forecasts and a dividend stream, and what happens when one unseen pressure on those margins shifts will matter a lot for returns.
If that unseen margin pressure has your attention, read the 3 key rewards and 2 important warning signs (1 is major!) to see how rate sensitivity, credit trends, and valuation assumptions could be quietly diverging.

Seeking Alternatives Before The Crowd Moves
Fresh ideas move first, and the strongest momentum can fly once early buyers get in. Scan these under the radar themes before the best entry points drop away. Consider acting early.
- Scan for income workhorses by tracking the 8 dividend fortresses that could help keep portfolios steady while prices swing and yield hunters arrive later.
- Target AI exposure by using the 41 profitable AI stocks that aren't just burning cash that filters for businesses with cash coming in, not just stories burning through capital.
- Follow the hardware backbone of the AI trend by reviewing the 52 AI infrastructure stocks as demand for compute and data capacity evolves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com