


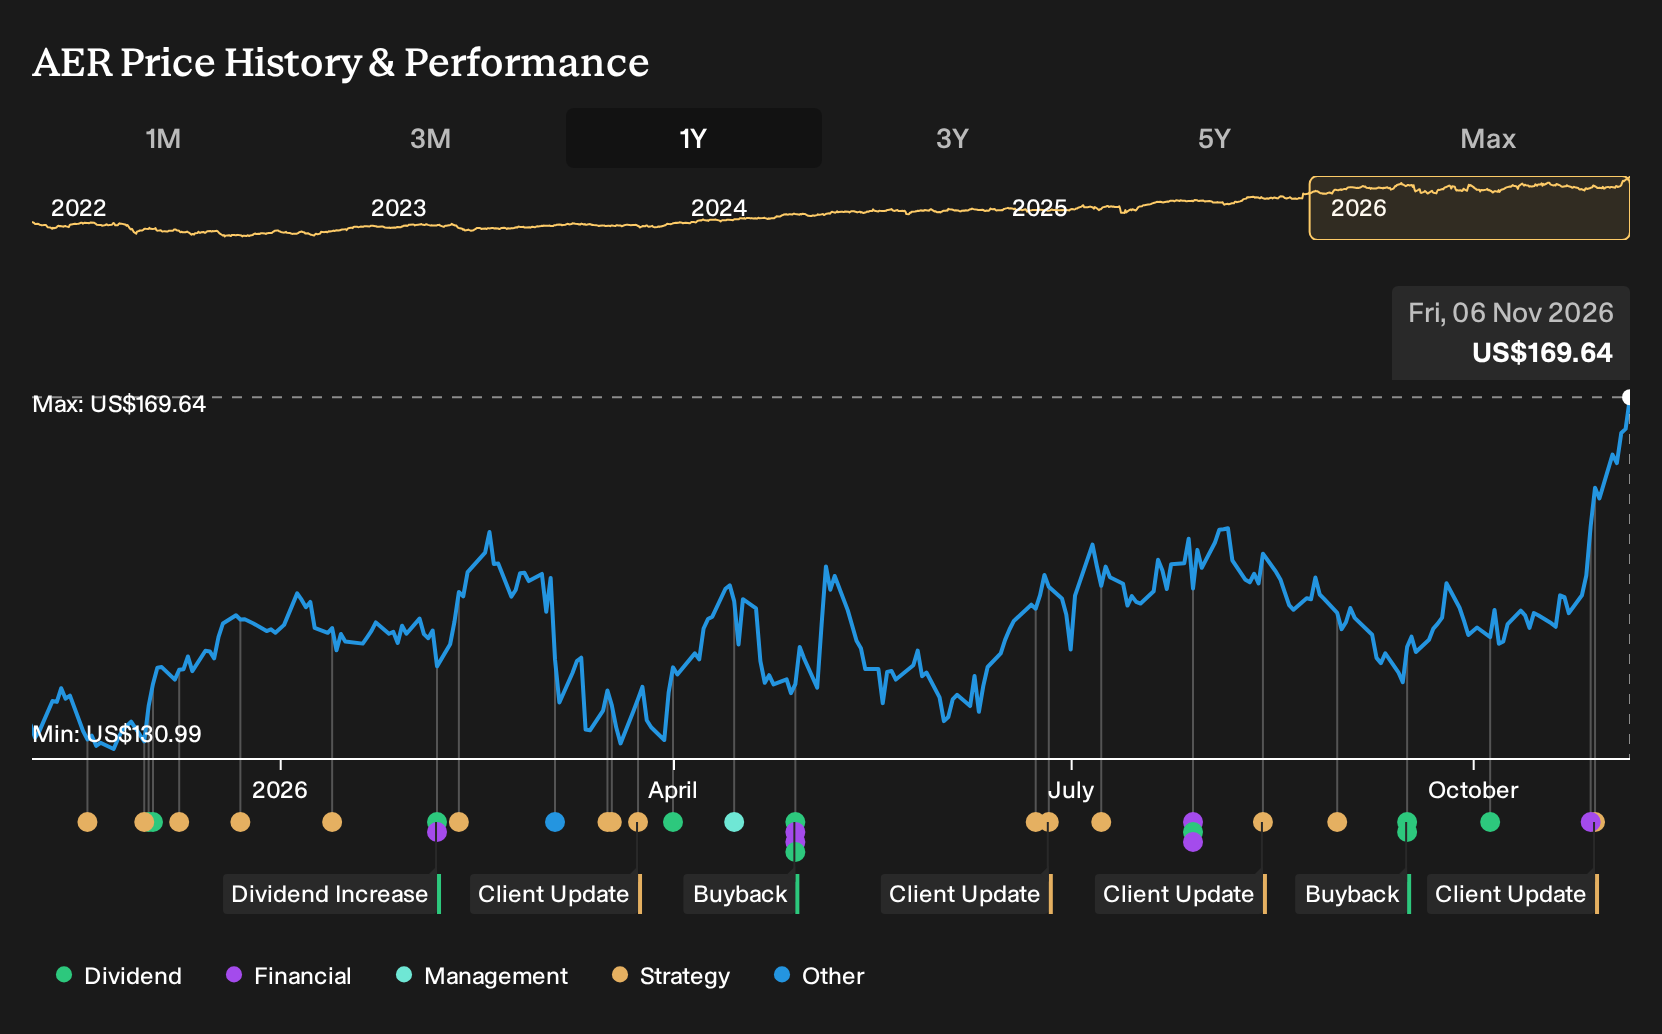
- AerCap Holdings reported third quarter 2026 revenue of US$2,415.33 million and net income of US$948.8 million, alongside new lease agreements with Turkish Airlines for two Boeing 777-300ERSF converted freighters scheduled for delivery in 2027.
- The combination of higher reported revenue, lower earnings and fresh 777-300ERSF leasing activity to Turkish Airlines, following earlier program traction with Kalitta Air, Fly Meta, Ethiopian Airlines and China Southern Group, provides a snapshot of AerCap Holdings freight focused execution in the context of its current profitability profile.
- The focus now turns to how AerCap Holdings investment narrative is influenced by higher revenue together with new 777-300ERSF leases to Turkish Airlines.
Scan beyond AerCap Holdings and see how other aircraft lessors and capital intensive businesses with freight exposure line up in our curated list of solid balance sheet and fundamentals (24 results).
AerCap Holdings Investment Narrative Recap
To own AerCap Holdings, you need to be comfortable with a capital intensive leasing model that leans on tight aircraft supply, high utilization and steady demand for newer, fuel efficient jets and cargo conversions. The most important short term swing factor is execution on lease extensions and asset sales, and the latest quarter shows revenue higher but net income and EPS lower year on year.
The cargo conversion push is an operational bright spot, yet it does not change the biggest current risk. Earnings are forecast by analysts to decline over the next few years and interest costs are flagged as not well covered by earnings, so any pressure on airline profitability or aircraft values could bite faster than before.
The Turkish Airlines 777 300ERSF leases sit in the middle of AerCap Holdings key catalyst: deeper exposure to engines, cargo conversions and helicopters. With deliveries planned for 2027 and conversion at Etihad Engineering in Abu Dhabi, the transaction adds to an already active 777 300ERSF program alongside Kalitta Air, Fly Meta, Ethiopian Airlines and China Southern Group.
This announcement matters because it underlines that cargo conversions are gaining traction while quarterly earnings have softened compared with last year. For you as an investor, the question is whether this freight pipeline and broader diversification can help offset forecast earnings declines and the risk that any stumble in lease rates or gains on sale hits a stock that some independent work already describes as richly valued.
AerCap Holdings is framed by analysts as moving toward about US$8.3b in revenue and US$2.3b in earnings by 2029, based on an assumed yearly revenue decline of 2.9% and a drop in profit from US$3.1b in earnings today. This implies an earnings decrease of US$0.8b by the 2029 forecast year.
Uncover how AerCap Holdings' fair value indicates a 10% potential upside to its current price before that valuation gap closes.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$186.6 to US$301.6 per share, so retail opinions on AerCap Holdings already stretch from cautious to very optimistic. Add in risks around executive share sales and potential valuation reset, and you are looking at a stock where perspectives diverge sharply.
Explore another AerCap Holdings fair value estimate, including one that suggests it could be worth just $186.60.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AerCap Holdings research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for AerCap Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AerCap Holdings' overall financial health at a glance.
Looking for more investment ideas beyond AerCap Holdings?
If the AerCap Holdings story has sharpened your thinking on risk, balance sheets and future cash flows, it can help to line it up against a wider watchlist built from different angles using the Simply Wall St Screener.
- For investors who want potential upside with strict quality filters on financial strength, start by scanning a 19 high quality undiscovered gems that already pass robust fundamental checks.
- If resilience matters more than excitement for your next idea, narrow your focus to a 29 resilient stocks with low risk scores that score well on balance sheet and volatility metrics.
- Income focused readers who prefer cash returns today rather than future optionality can work through a curated set of 8 dividend fortresses that combine higher yields with supporting fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com