


Motorola Solutions (MSI) just delivered third quarter results that topped Wall Street expectations on both revenue and earnings, paired with raised full year guidance and a record order backlog that sharpened investor focus.
That backdrop helps explain why Motorola Solutions’ recent share price momentum has been strong, with a 14.8% 1 month share price return contributing to a 35.0% year to date gain. Total shareholder return over 5 years has reached 117.0%, pointing to sentiment that remains firmly positive rather than fading.
Scan beyond Motorola Solutions and line up other potential breakout candidates with the curated list of 39 high quality undervalued stocks that combine stronger fundamentals with attractive pricing signals.
The share price now sits close to analyst targets, while intrinsic value estimates point to a far lower figure. For Motorola Solutions after this run, which signal deserves more weight?
Preferred P/E of 40.8x: Is it justified?
Motorola Solutions now trades on a rich P/E multiple, and the stock price of $514.51 reflects that investors are paying a premium compared with peers and the wider communications space.
The P/E ratio compares the share price to earnings per share. For a business like Motorola Solutions, which generates profit from public safety communications and security software, this measure captures how much investors are willing to pay for each dollar of current earnings.
Here that willingness is high. The current P/E of 40.8x is well above the US Communications industry average of 25.4x and also ahead of the peer group average of 39.9x. The fair P/E estimate of 26.3x sits much lower, which signals a level that the market could move towards if enthusiasm eases or if profit growth does not keep pace with expectations.
Explore the SWS fair ratio for Motorola Solutions.
The SWS DCF model also points in the same direction. Motorola Solutions is trading at $514.51 while the model’s future cash flow value sits at $395.84, which frames the current quote as expensive relative to that intrinsic estimate. The DCF approach projects future free cash flows and discounts them back to today using a required return, so it is anchored in the cash the business is expected to generate rather than just headline earnings.
For a mature communications and public safety provider with forecast earnings growth of 11.36% per year, that gap between the trading price and the SWS DCF value highlights how much optimism is already embedded. The high reported Return on Equity of 67.73% is described as outstanding but is also flagged as being skewed by leverage, which adds another layer for investors to weigh when judging how much to pay for those earnings.
Look into how the SWS DCF model arrives at its fair value.
Result: Price-to-earnings of 40.8x (OVERVALUED)
Still, any stumble in Motorola Solutions’ public safety spending pipeline, or a reset in market enthusiasm around its 40.8x P/E, could quickly challenge this premium story.
Find out about the key risks to this Motorola Solutions narrative.
Another View on Motorola Solutions’ DCF Value
The P/E looks stretched, and the SWS DCF model also leans the same way. At a share price of $514.51 versus an estimated future cash flow value of $395.84, Motorola Solutions screens as overvalued on cash generation as well. That raises a tougher question: Is this simply the cost of buying a quality franchise, or has enthusiasm moved too far ahead of the math?
Look into how the SWS DCF model arrives at its fair value.
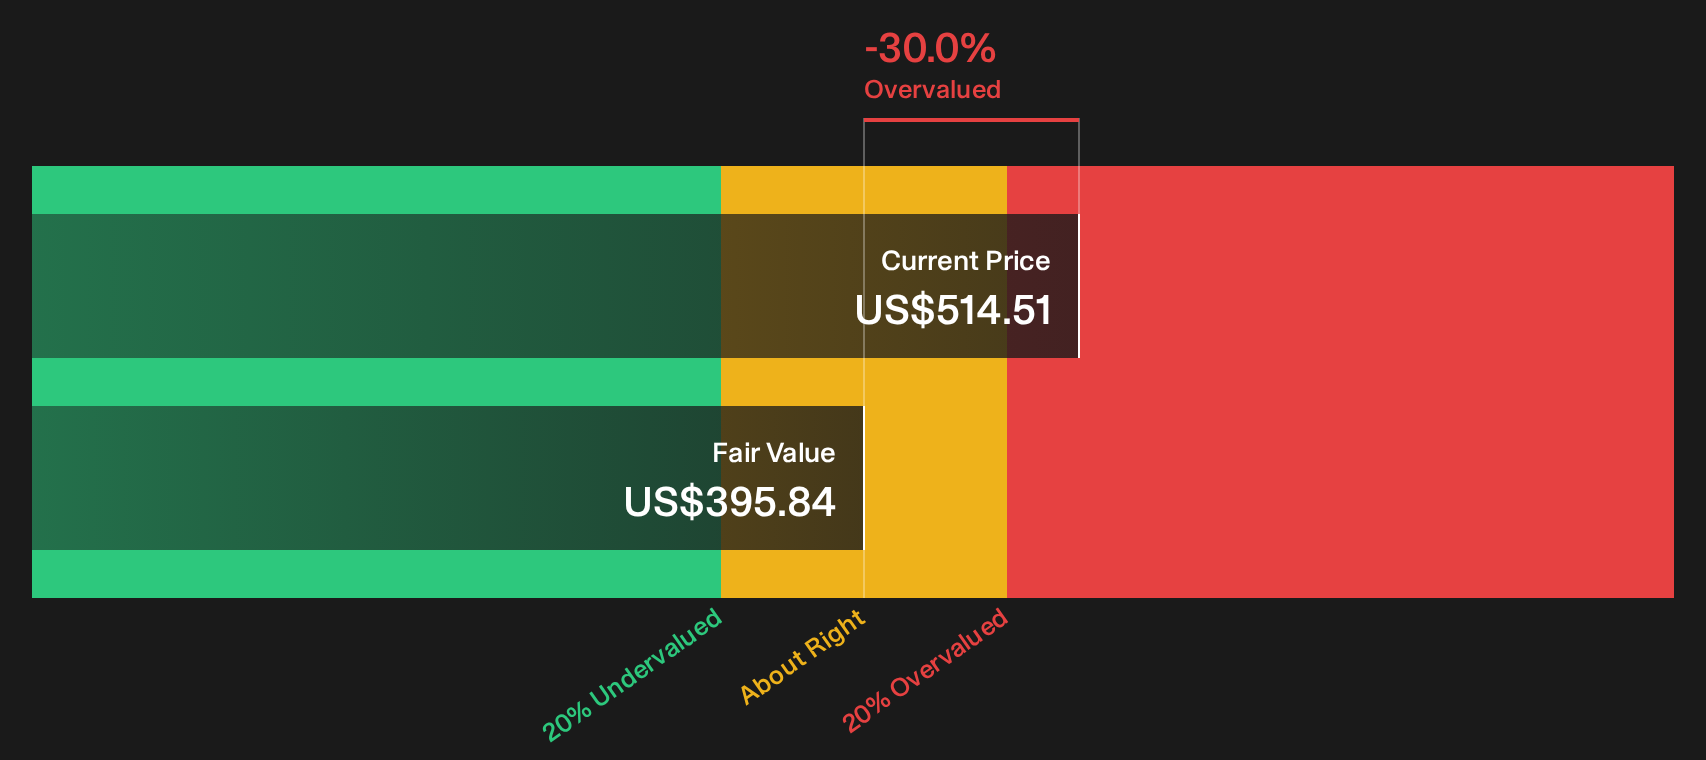
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Motorola Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment clearly mixed around Motorola Solutions’ premium pricing and quality signals, it helps to move fast and stress test the numbers yourself. To weigh the upside against the downside in one place, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Motorola Solutions?
Do not stop your research with Motorola Solutions. Fresh opportunities often emerge where pricing, quality, and risk line up more cleanly for new capital.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results) that can help anchor a more durable portfolio core.
- Hunt for quality at a discount by reviewing the 19 high quality undiscovered gems that pair strong financial foundations with limited current market attention.
- Prioritize sleep-at-night positions by focusing on the 29 resilient stocks with low risk scores that keep overall portfolio volatility in check.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com