


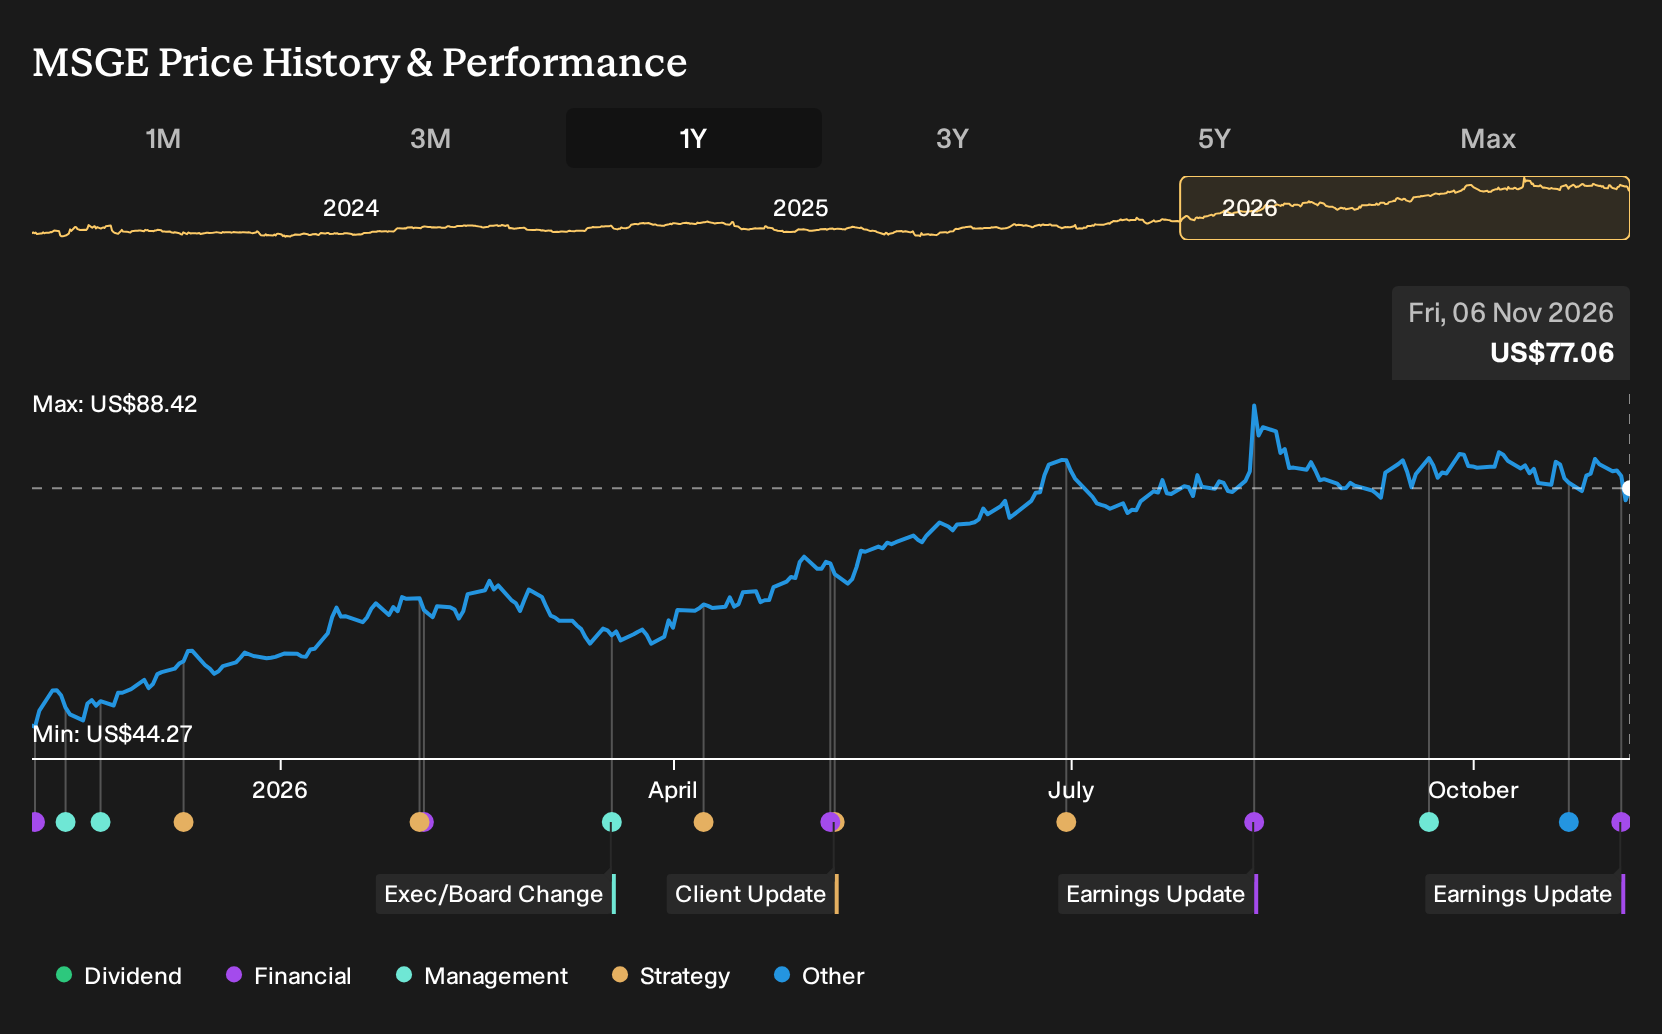
- Madison Square Garden Entertainment reported Q1 fiscal 2027 revenue of US$217.1 million and net income of US$8.9 million, with earnings of US$0.19 per basic and diluted share from continuing operations, compared with a loss a year earlier.
- The quarter reflected record concert attendance at Madison Square Garden, a 30 show Harry Styles residency, over 1.3 million guests across 160 live events, and plans for a record 231 performance Christmas Spectacular season, supported by share repurchases of about US$25 million.
- We will now look at how Madison Square Garden Entertainment's swing back to profitability could influence the broader investment narrative.
Scan how Madison Square Garden Entertainment’s record event slate compares with other live entertainment and consumer experience stocks using our curated list of 19 high quality undiscovered gems.
Madison Square Garden Entertainment Investment Narrative Recap
To own Madison Square Garden Entertainment, you need to believe high venue usage, residency style runs and proprietary shows like the Christmas Spectacular can keep filling the calendar and support earnings despite a high debt load. The Q1 swing to a US$8.9 million profit and 37% revenue uplift gives fresh evidence that event demand is currently there.
The near term swing factor is whether this record event slate converts into consistent, cash generative operations once the Harry Styles residency and holiday peak fade. The biggest risk remains rising operating, legal and data privacy related costs eating into margins even if ticket demand, sponsorships and premium hospitality stay healthy.
The cleanest way to read this quarter is through the November 4 Q1 fiscal 2027 earnings release itself. Revenue of US$217.1 million and earnings of US$0.19 per basic and diluted share from continuing operations, compared with a loss a year earlier, show how a packed Garden and residencies can affect profitability when the schedule cooperates.
For catalysts, that report also flagged record concert attendance, over 1.3 million guests across 160 events and a record 231 show Christmas Spectacular run pacing ahead on advance ticket sales. Execution risk now sits in repeating this intensity of bookings while holding the line on SG&A, legal and data related costs so those headline volumes translate into durable free cash flow.
Madison Square Garden Entertainment's analyst narrative points to revenue of US$1.2b and earnings of US$165.5 million by 2029. This assumes 5.1% yearly revenue growth and an earnings increase of about US$99.3 million from US$66.2 million today.
Uncover how Madison Square Garden Entertainment's fair value indicates a 19% potential upside to its current price before that discount starts to close.
Exploring Other Perspectives
Bullish analysts frame a different angle for Madison Square Garden Entertainment. The big swing factor is premium valuation rather than cost risk. Before this Q1 earnings surprise, the most optimistic forecasts were already baking in roughly US$1.3b of 2029 revenue and about US$206.5 million of earnings. Those higher targets show how far opinions can spread, and this latest report may push some projections to shift again.
Explore 2 other Madison Square Garden Entertainment fair value estimates, including one that suggests up to 19% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Madison Square Garden Entertainment research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Madison Square Garden Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Madison Square Garden Entertainment's overall financial health at a glance.
Looking For More Investment Ideas Beyond Madison Square Garden Entertainment?
Once you have a view on Madison Square Garden Entertainment, it can help to compare it with other opportunities that fit different income, quality and risk profiles. The Simply Wall St Screener lets you quickly scan for stocks that match what you care about most, whether that is income, resilience or potential mispricing.
- For investors who want income first and foremost, you can explore companies offering yields and payout histories through 8 dividend fortresses.
- If capital preservation and balance sheet strength are your priority, you can start with our list of solid balance sheet and fundamentals (24 results) to look for businesses with stronger financial footing.
- When you are looking for opportunities the market might not be fully focused on yet, you can scan the 19 high quality undiscovered gems that pair fundamentals with underfollowed stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com