


Parker-Hannifin has been a powerful long term winner, with the stock up 191.8% over the past 5 years. This naturally raises the question of whether the cash it can generate still lines up with a share price near record territory. With recent news highlighting fresh earnings strength and a larger filtration footprint, the focus now shifts to what the company’s cash flows suggest about today’s valuation.
- A 191.8% gain over 5 years puts a lot of expectation into Parker-Hannifin’s future cash flow stream and makes the current price more sensitive to any change in those expectations.
- Recent results and the Filtration Group acquisition point to potential shifts in revenue mix, margins, and cost savings that can reshape the pattern and durability of Parker-Hannifin’s cash generation over time.
- Prefer to judge Parker-Hannifin on earnings? See what Parker-Hannifin's 31.1x P/E says about the price.
The issue now is whether the stock’s current level is supported by the intrinsic value suggested by Parker-Hannifin’s cash flows when run through a Discounted Cash Flow (DCF) lens.
If you want a wider watchlist of industrial names to compare against Parker-Hannifin while you consider its cash flow story, a focused screen of 42 power grid technology and infrastructure stocks can be a useful next step.
Does Parker-Hannifin Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at what Parker-Hannifin can return to shareholders over time based on projected free cash flows. Latest twelve month free cash flow sits at about $3.9b, and the forecast path assumes that this pool of cash keeps growing steadily rather than swinging sharply up or down.
Those projections call for free cash flow to move into the $6b a year area by 2030, which lines up with the picture of a mature industrial group that is still finding incremental opportunities to expand its cash base. Because the DCF output sits broadly in line with the current share price of $917.79, the market is treating Parker-Hannifin as a business where these future cash streams are largely recognised already. The record Q1 fiscal 2027 results and upgraded guidance after the Filtration Group acquisition help explain why investors appear comfortable paying close to that implied value today. Find out what Parker-Hannifin could be worth using our Discounted Cash Flow (DCF) estimate.
The Parker-Hannifin Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Parker-Hannifin valuation puzzle leaves off and spell out which paths for growth, margins and earnings would need to play out for the stock to end up meaningfully above or below today’s level, all housed on the Community page. Rather than relying on a single multiple or model line, each scenario lays out the assumptions behind its view of fair value so you can test those against future results as they come through.
Community views on Parker-Hannifin split between those who see more cash flow firepower ahead and those who think the premium rating already reflects it.
Bull case: 32% undervalued
"The completion of the Filtration Group acquisition in August 2026, which is expected to create one of the largest global industrial filtration businesses with broader aftermarket exposure and identified synergies..."
Discover why this Narrative puts Parker-Hannifin at 32% undervalued.
Bear case: 7% overvalued
"The numbers indicate that Parker-Hannifin is fairly valued, with the current premium P/E multiple and a discounted cash flow assessment suggesting the shares are roughly 22% above intrinsic value..."
Explore why this Narrative puts Parker-Hannifin at 7% overvalued.
One more Parker-Hannifin signal worth checking before you move on
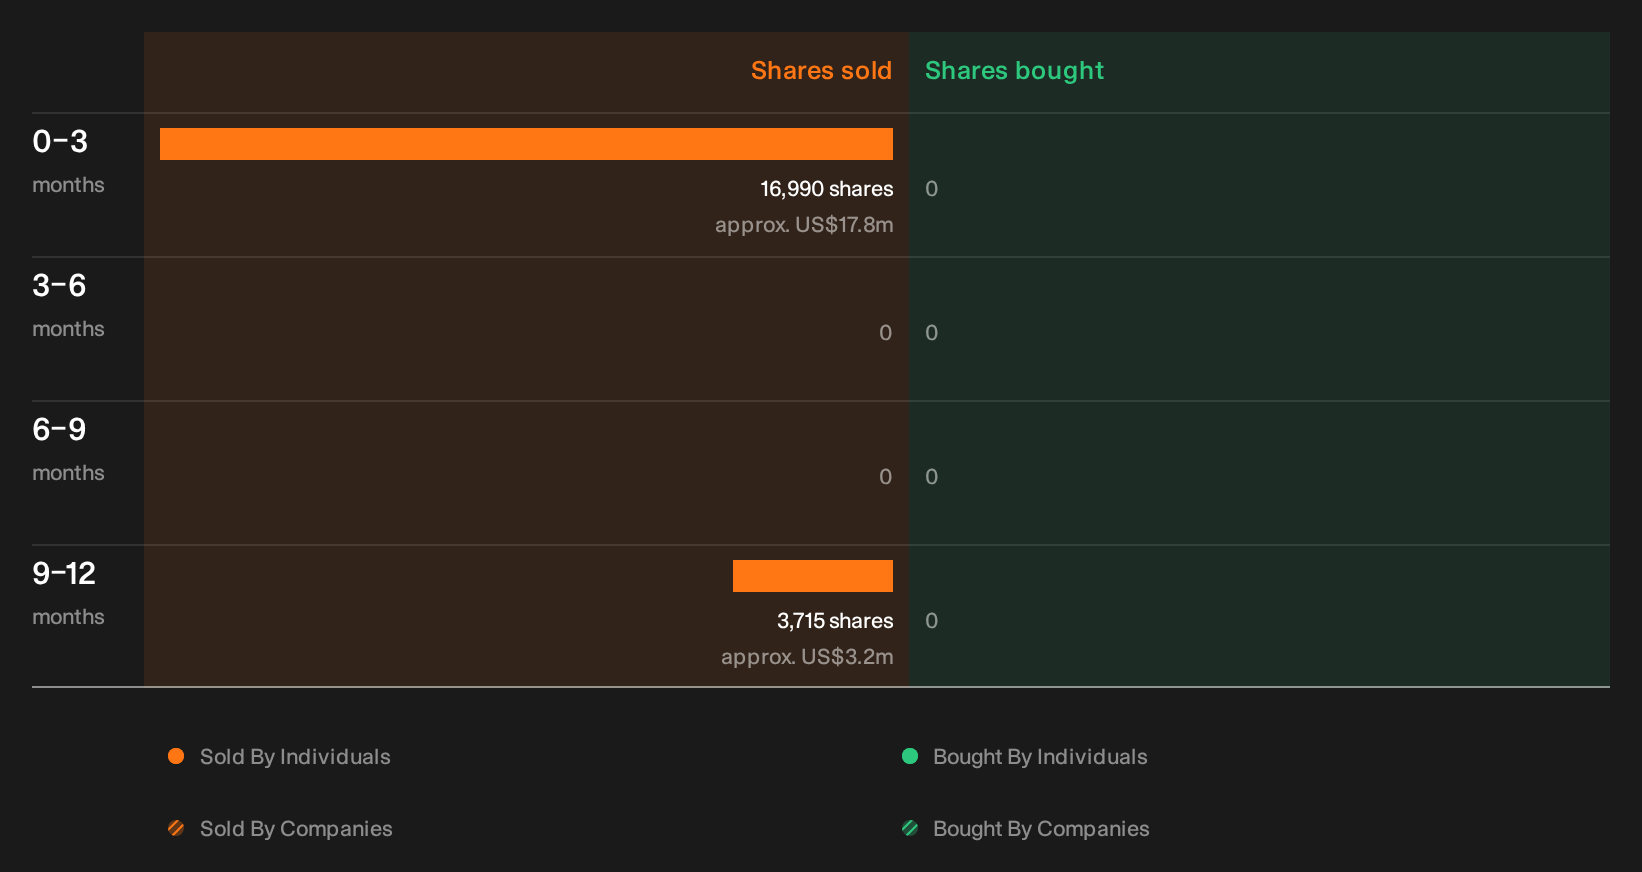
There is one area the valuation work has not touched yet. This is the recent trading activity by Parker-Hannifin insiders that the checks have picked up, and the individuals involved, amounts and possible read throughs sit waiting for a closer look. See the recent insider selling flagged for Parker-Hannifin.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com