


- CoStar Group reported third quarter 2026 revenue of US$952 million and net income of US$74 million, then raised full year revenue guidance to a range of US$3.75 billion to US$3.77 billion despite identified shortfalls in Domain and residential subscription lines.
- The shift from a net loss in the prior year to earnings of US$0.18 per diluted share in the quarter indicates that recent cost and product decisions are now reflected in CoStar Group’s reported profitability.
- Investors can now assess how CoStar Group’s stronger earnings and higher full year revenue guidance may influence the existing investment narrative.
Compare CoStar Group’s guidance shift with a curated set of resilient companies by scanning the 29 resilient stocks with low risk scores that may hold up better when expectations change this quickly.
CoStar Group Investment Narrative Recap
To own CoStar Group, you need to believe the real estate data and marketplaces portfolio can support both healthy revenue and consistent profitability as management tightens costs. The raised full year revenue guidance, even with identified gaps in Domain and residential subscriptions, keeps the short term catalyst focused on execution in Homes.com, Apartments.com and related platforms.
The biggest current risk is that the profit focus, including prior cuts to sales headcount and restructuring within auction operations, slows net new bookings and caps future top line progress. The latest numbers and guidance tweaks do not remove that concern. They simply provide fresher evidence on how that trade off is developing.
The third quarter 2026 results are the clearest anchor for this update. CoStar Group reported US$952 million of revenue and net income of US$74 million, with diluted earnings per share of US$0.18 compared with a loss per share of US$0.07 a year earlier. For the first nine months, revenue reached US$2.774 billion and net income US$132 million.
Those figures sit alongside guidance for fourth quarter 2026 revenue of US$976 million to US$996 million. When you align that with the revised full year outlook, the key question is how durable this more profitable profile is, given pressure in multifamily advertising, the mixed impact of Ten X restructuring and the softer Domain and residential streams.
CoStar Group Consensus Forecasts In Context
CoStar Group's analyst narrative centres on a long runway for expansion in both data subscriptions and marketplaces, supported by a set of explicit revenue and earnings targets that readers can test against their own expectations.
Analysts currently assume that CoStar Group's top line can increase at about 8.4% per year over the next three years, while profit margins are projected to move from 4.9% today to 14.5% over the same period.
On the earnings side, the consensus view points to profit of US$678.0 million by 2029 compared with US$179.0 million today. This works out to roughly a 3.8x uplift in earnings over that span, even with some analysts forecasting as little as US$595.7 million.
To get comfortable with that profile, you would need to judge that Homes.com, Apartments.com, Zonda and the international portals can support that level of scale without eroding the margin targets that underpin these projections.
Valuation assumptions tie directly into these figures, with analysts using the US$678.0 million earnings estimate for 2029 alongside an implied P/E of 23.1x, down from a current multiple of 62.3x and higher than the US Real Estate industry P/E of 14.0x.
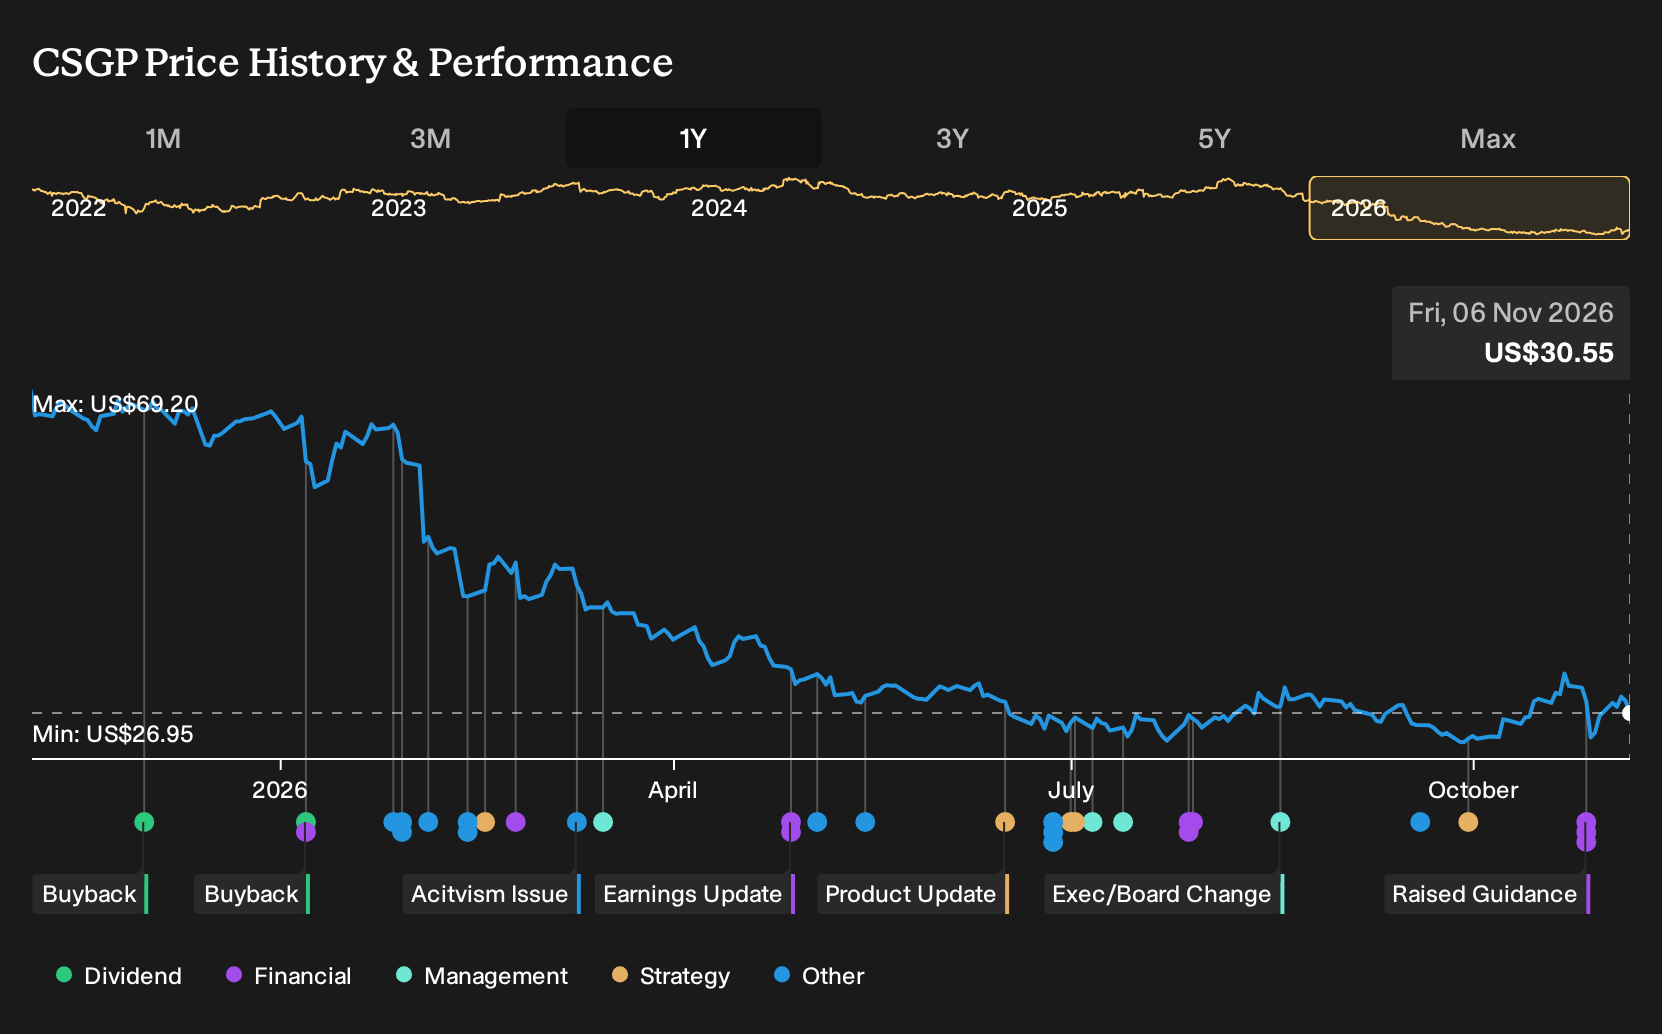
On this framework, the consensus view translates into a price target of US$35.85 per share, framed against a recent share price of US$27.54 and a range of US$26.0 to US$50.0 across individual analyst models. This highlights that views on execution risk and potential upside still vary widely.
CoStar Group's narrative projects US$4.7b revenue and US$678.0 million earnings by 2029, which is built on 8.4% yearly revenue growth and roughly a 3.8x earnings increase from US$179.0 million today.
Discover why CoStar Group's fair value indicates a 17% potential upside to its current price, an opportunity that could narrow quickly.
Exploring Other Perspectives
The lowest analysts care far more about CoStar Group’s margin risk than the headline revenue lift. Before this earnings beat and raised 2026 guidance, they were still pencilling in about US$4.9b of revenue and US$684.9 million of earnings by 2029, yet arguing that even those numbers might not justify today’s share price. That is a very different story to the consensus view, so treat this update as a prompt to compare several narratives rather than accept any single forecast at face value.
Explore 4 other CoStar Group fair value estimates, including one that suggests as much as 18% downside from the current price.
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your CoStar Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for CoStar Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CoStar Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond CoStar Group?
If the CoStar Group story has sharpened your thinking, use that momentum to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener gives you a way to scan the market quickly and then slow down only for the businesses that genuinely match your goals.
- If capital protection is front of mind, focus on companies with steadier profiles by starting with a 29 resilient stocks with low risk scores that may suit a more cautious approach.
- If income is a core part of your plan, filter for reliable payers by reviewing a curated 8 dividend fortresses that might interest yield focused investors.
- If you want to get ahead of the crowd, search for quality businesses that receive less attention by checking a targeted 19 high quality undiscovered gems that could broaden your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com