


Royalty Pharma (RPRX) has just reset the conversation around its stock after third quarter results topped expectations and management raised full year 2026 guidance for the third straight time.
The strong third quarter update has landed on top of a powerful run in Royalty Pharma’s shares, with a 30 day share price return of 18.57% and a year to date share price gain of 73.19%, while total shareholder return over three years has reached 166.92% and 80.44% over five years. This signals that investors have been steadily repricing the stock as confidence in its royalty pipeline and cash generation model has built.
Scan how Royalty Pharma’s royalty driven run compares with other cash generative compounders by reviewing the hand picked 39 high quality undervalued stocks now shaping this corner of the market.
Bulls point to raised guidance, new royalties and a rich pipeline. Bears focus on a premium P/E and earnings pressure. Which side does Royalty Pharma’s current valuation actually reward you for backing?
Most Popular Narrative: 10% Overvalued
On the most followed narrative, Royalty Pharma’s fair value sits at $61, which is below the recent $67.30 close. This suggests a rich valuation that still depends on future execution.
Even with disciplined capital allocation and reported mid-teens return on invested capital and over 20% return on equity, the need to fund larger transactions like the US$2b Revolution Medicines structure risks sustaining the trend of higher capital intensity. This could restrain future free cash flow growth and limit expansion in earnings.
See why 1 investors see Royalty Pharma as 10% overvalued.
Result: Fair Value of $61 (OVERVALUED)
Still, if Royalty Pharma continues to convert its 35 marketed therapies and 20 pipeline assets into stronger royalty receipts, the bearish 10% overvaluation case could soften quickly.
Find out about the key risks to this Royalty Pharma narrative.
Another View: Royalty Pharma Through A Cash Flow Lens
The bearish $61 fair value comes from analyst assumptions. A different tool, the SWS DCF model, points in almost the opposite direction. On that framework Royalty Pharma at $67.30 trades at a steep discount to an estimated future cash flow value of $208.27, which frames the current price as potentially undervalued.
The gap between a premium earnings multiple and a DCF that supports much higher value raises a simple question. Is the risk in Royalty Pharma that investors are paying too much for near term earnings, or that the market is underpricing the durability of its royalty cash flows? Our DCF model suggests the latter and is worth stress testing against your own assumptions with Look into how the SWS DCF model arrives at its fair value.
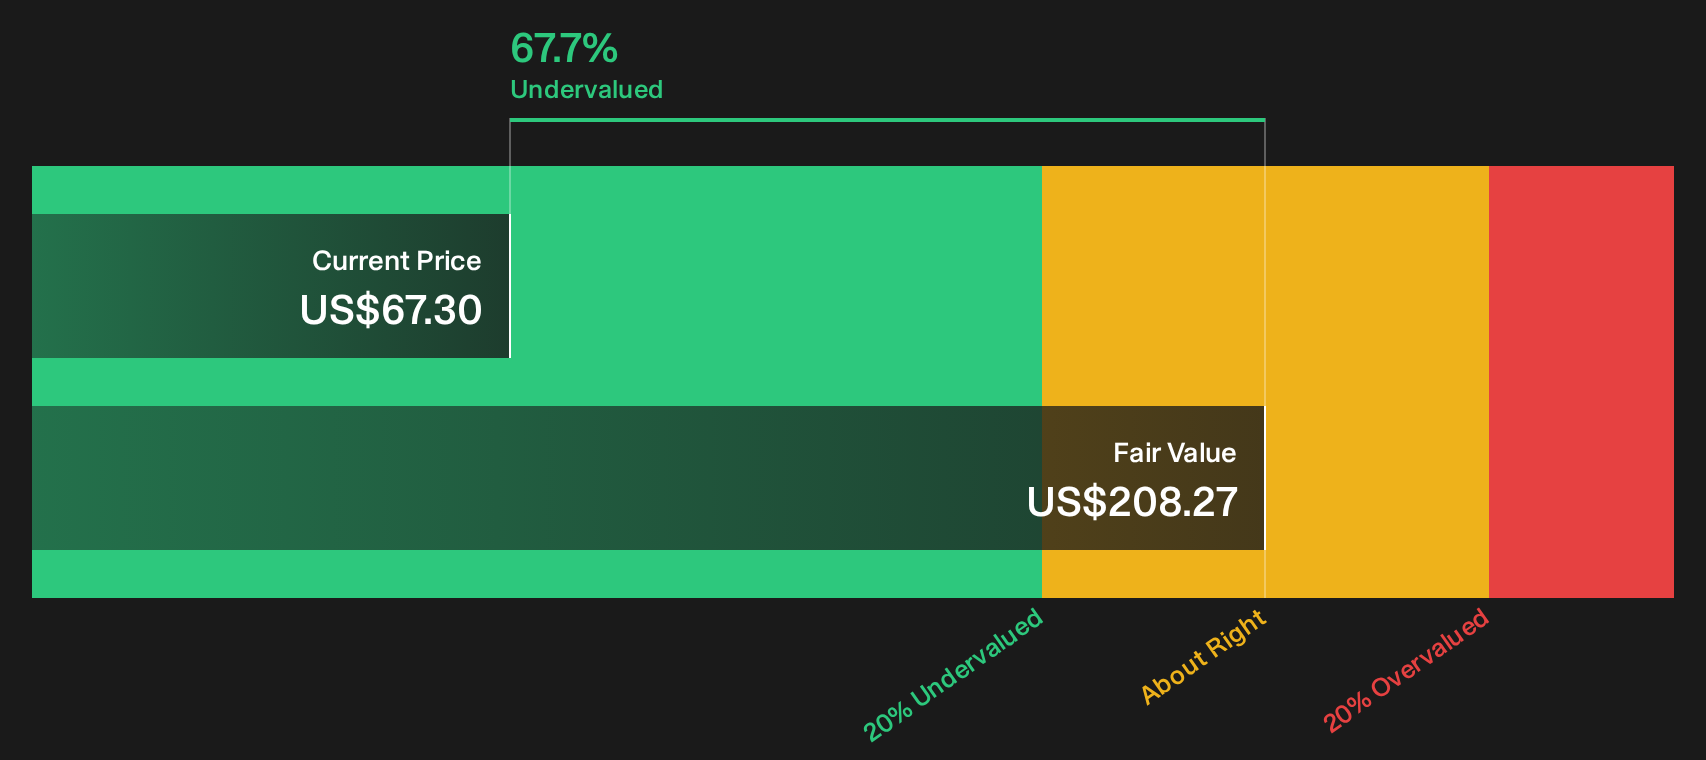
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Royalty Pharma for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big reactions often come with mixed feelings, and Royalty Pharma is no exception. Move quickly from headline impressions to your own judgment by weighing the 2 key rewards and 1 important warning sign.
Looking for more Royalty Pharma style ideas?
Do not stop with Royalty Pharma. Broaden your watchlist now, or risk missing businesses that may fit your return goals even better.
- Target stability first, then returns, by reviewing a 29 resilient stocks with low risk scores that can help you focus on resilience when markets turn choppy.
- Spot strong balance sheets before the crowd by scanning a list of solid balance sheet and fundamentals (24 results) that highlights companies built on firmer financial footing.
- Hunt for potential future winners by checking a 19 high quality undiscovered gems that surfaces quality opportunities still flying under most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com