


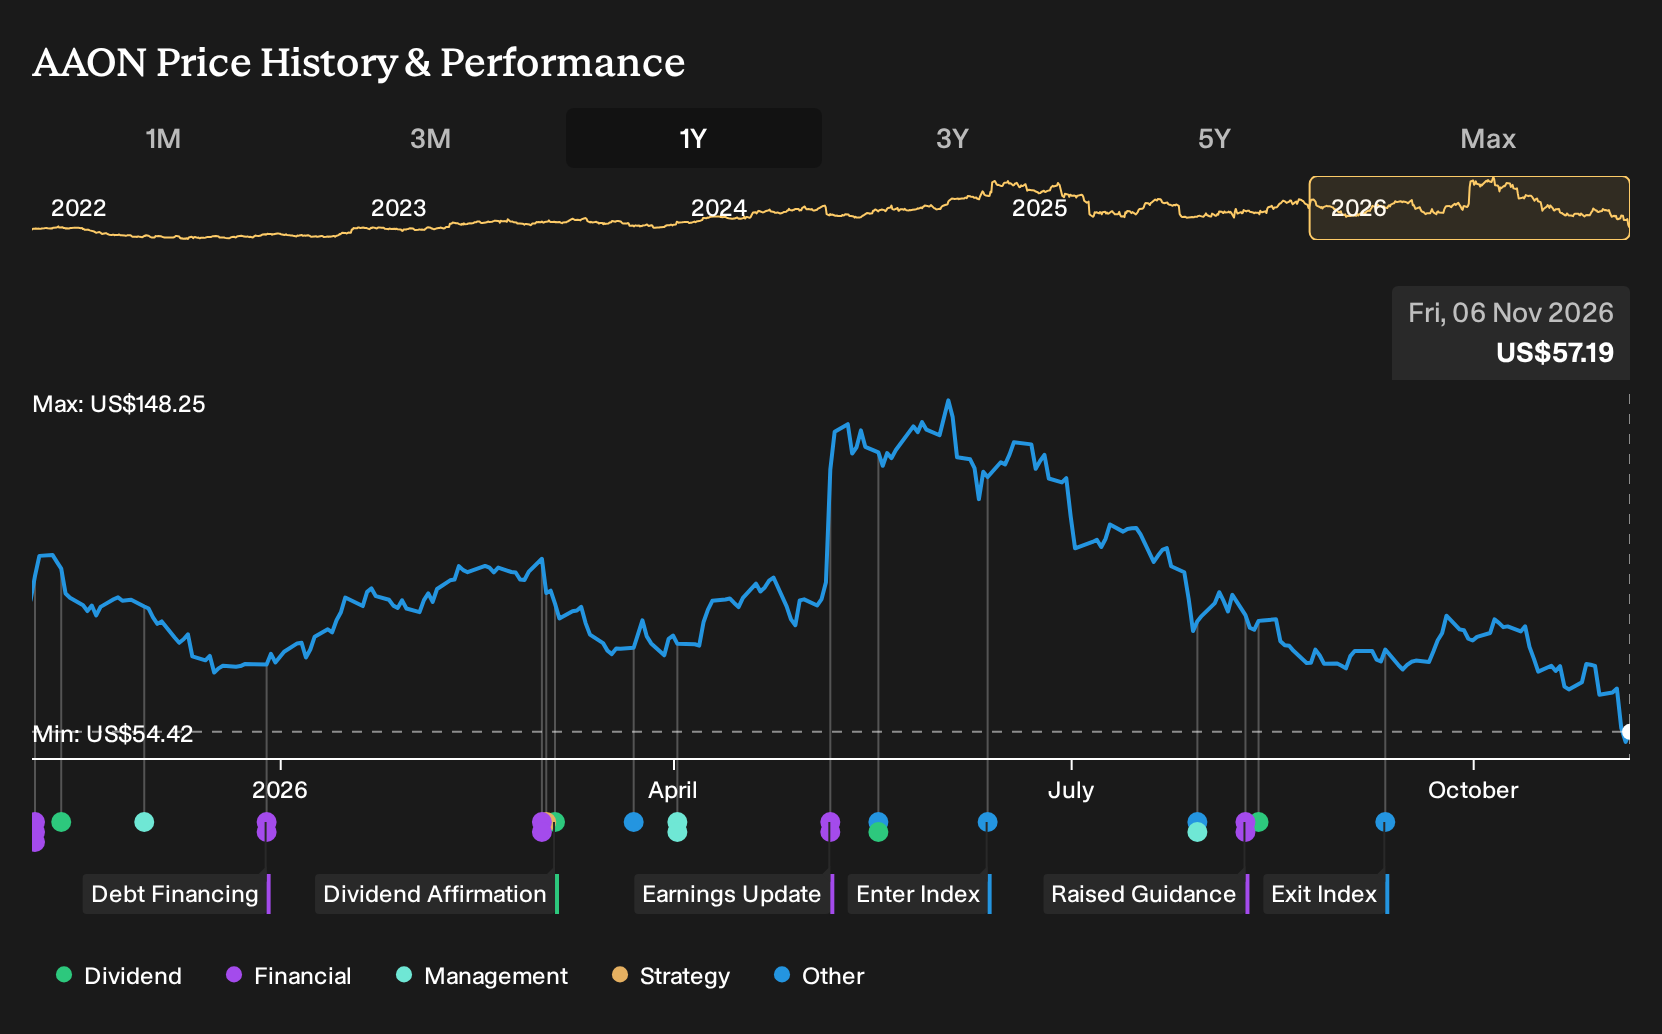
If you had glanced at AAON in late 2025 and decided to give it a miss, that choice has looked very different over the past year. Investors who held AAON over the past year are down 45.6%, including dividends. Fresh headlines in 2026 now talk about record backlogs, raised guidance, insider selling and even a price-fixing lawsuit. The real question is what assumptions and public information back in November 2025 might have warned you that this sort of swing was possible.
AAON has already moved. Pinpoint other ways to investigate the theme among 42 power grid technology and infrastructure stocks.
The Argument AAON Investors Were Really Weighing
The shares cost US$100 at the start of the period, and anyone looking at AAON then had to choose between two very different stories about where the business might reasonably head next.
On the bullish side, the Narrative pointed to a Fair Value of US$125, a price implied by assumptions of rapid revenue expansion as a US$1b backlog converted and high efficiency HVAC and data center cooling demand supported rising margins.
The bearish Narrative argued for a Fair Value of US$90, based on expectations that elevated costs from aggressive capacity expansion and dependence on a concentrated group of North American and data center customers could strain cash generation and keep valuation more restrained.
What The AAON Evidence Actually Tested
Record Q2 2026 results for AAON, with revenue at US$626.976 million and net income at US$56.659 million, lined up squarely with the bullish story that backlog and data center demand could support stronger scale. Revenue, profit and net margin all rose versus Q2 2025, although insider selling and a price-fixing lawsuit kept the cautious case alive. Overall, the evidence cut both ways.
The hinge assumption here was whether high backlog and capacity builds would translate into healthier margins. For another stock with a big order book, track the change in revenue, net income and net margin one year later against the original backlog claims to see if that conversion really showed up.
What AAON's Lower Price Now Really Buys You
AAON trades today at US$57.19, after the share price fell about 46% over the past year. The selected Narrative still places its Fair Value above the current quote, anchored in a belief that recent investment could eventually reshape how efficiently the business converts orders into earnings.
The argument hinges on whether heavy spending on BASX data center capacity and multi site manufacturing can turn backlog and share gains into stronger margins and cash generation. A buyer today would need to believe that margin compression and reinvestment are temporary side effects of building a bigger, more efficient AAON platform.
"The main thing that has to go right is that AAON turns rapid BASX data center growth, AAON brand share gains, and heavy capex into sustained margin expansion and stronger free cash flow, despite recent gross margin pressure and historical negative free cash flow."
One Narrative disagrees with today's price. → See where this Narrative says AAON should trade
AAON And The Data Behind It
AAON leans heavily on data centers and digital infrastructure demand. That focus invites a question about what quietly supports those same customers.
Cooling and air handling only matter if data is actually moving. Behind the scenes, another business builds hardware and software that helps process, connect and secure that flow.
Its chips move information between servers and storage. Its software keeps private clouds, mainframes and security tools working together.
If AI and cloud workloads keep multiplying, that backbone work could matter more. You might find AAON is only one piece of a bigger digital build out.
The argument comes with a number attached. → Uncover the AI infrastructure company trading 55% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com