


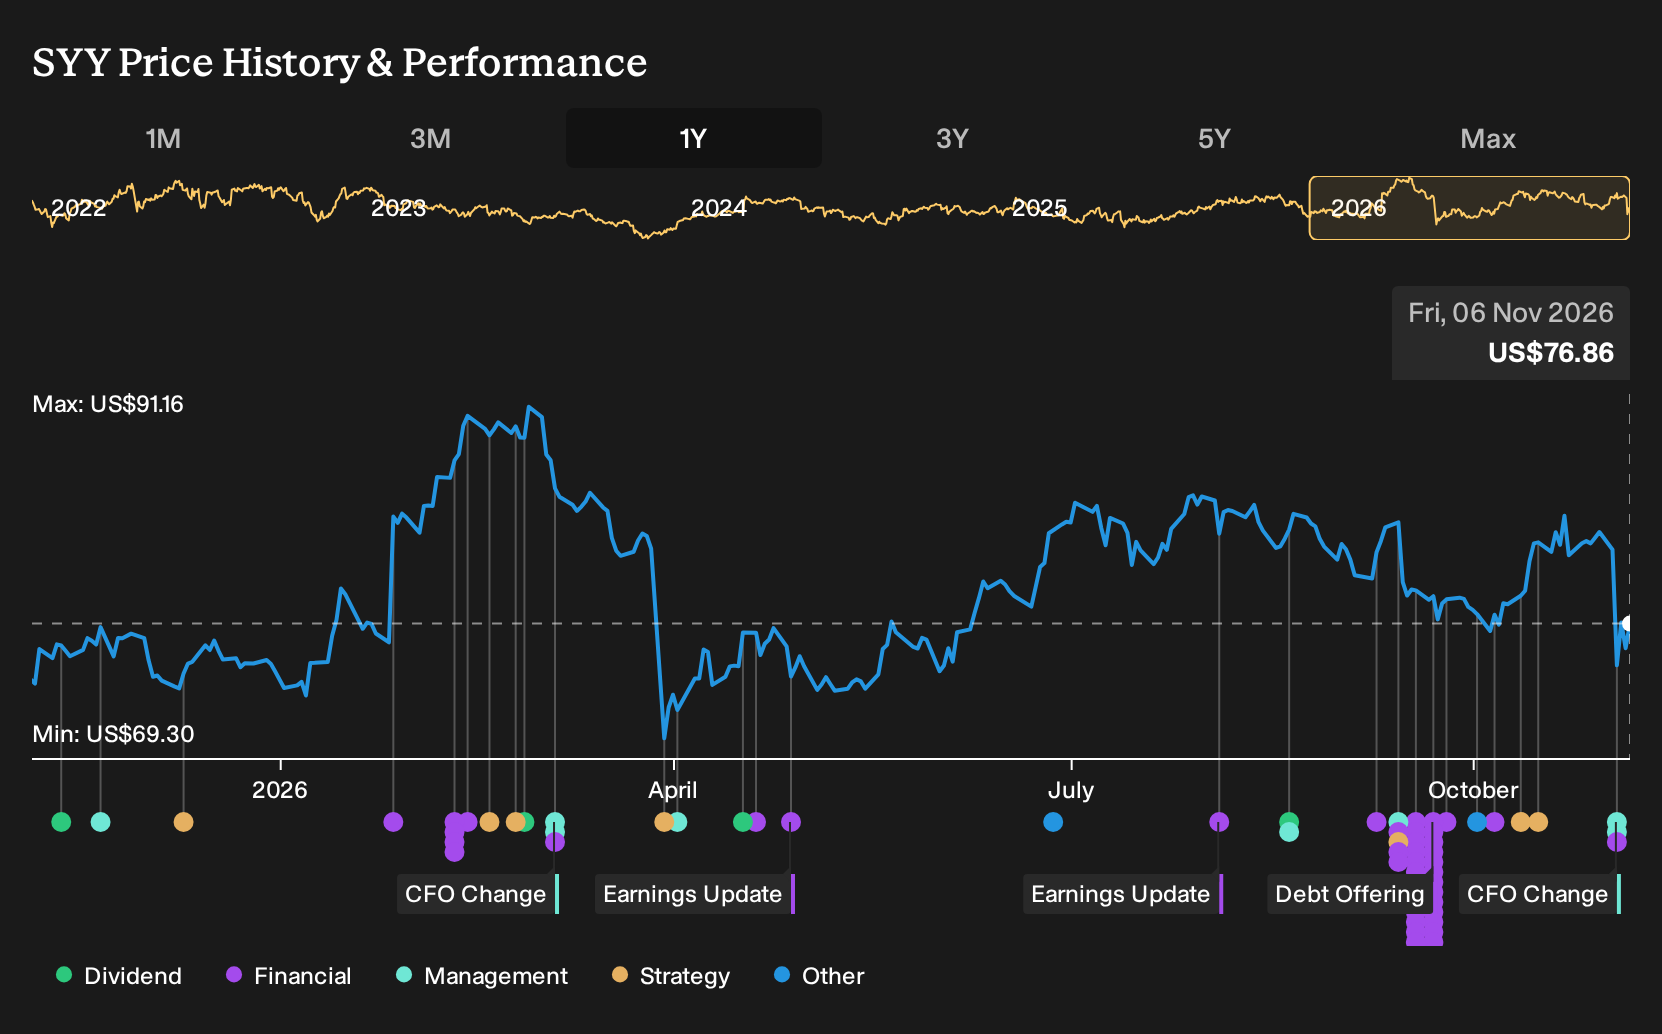
- Sysco reported first quarter 2026 sales of US$21,744 million and net income of US$526 million, and confirmed Brandon Sewell as Executive Vice President and Chief Financial Officer after serving in the role on an interim basis since March 2026.
- The combination of consistent finance leadership from a long-tenured insider and recent earnings progress gives investors a clearer view of how Sysco is running its largest segment and funding AI and technology initiatives.
- We will now see how Sysco's investment narrative could be influenced by the appointment of Brandon Sewell as permanent CFO.
Scan how Sysco compares with other companies where finance leadership is backing big technology upgrades through our hand-picked 52 AI infrastructure stocks.
Sysco Investment Narrative Recap
To own Sysco, you need to be comfortable with a foodservice distributor that is leaning on AI projects, mix initiatives and the planned Jetro Restaurant Depot deal to support future earnings while carrying a higher debt load. The short term swing factor is execution on these technology and integration plans while keeping service levels intact for restaurants and institutional customers.
The biggest near term risk is that higher leverage and the paused buyback leave less room for error if industry traffic or case volumes soften, or if investors grow less comfortable with debt funded expansion. The CFO appointment itself looks more like continuity than a material shift in the operating outlook.
The earnings release for the first quarter of fiscal 2026 is the announcement that ties closest to Brandon Sewell becoming permanent CFO. Sysco reported sales of US$21,744 million and net income of US$526 million, with basic and diluted earnings per share from continuing operations at US$1.09. Those figures give you a snapshot of how the finance team has been running the business while Sewell was in the interim role.
That period also included the launch of a multi year AI and technology modernization and the financing of the Jetro Restaurant Depot acquisition. Taken together, the results and project rollouts under Sewell link directly to the key catalysts investors are watching, such as targeted profit improvement, higher EBITDA from Restaurant Depot and the firm’s ability to manage leverage while keeping cash generation and dividends on track.
What The Sysco Forecasts Assume
Sysco's analyst narrative leans heavily on a clear set of targets that link the current AI rollout and Restaurant Depot deal to specific financial outcomes over the next few years. Instead of just talking about efficiency or scale, the projections spell out where revenue, profit margins and earnings are expected to land and what multiple investors would need to pay for those results.
On the top line, the consensus view assumes that Sysco can deliver revenue growth of about 4.7% each year over the next three years. The same models build in margin expansion from profit margins of 2.1% today to 3.0% in three years, which would mean the business converts a larger share of sales into profit while funding AI projects and integrating Restaurant Depot.
Earnings are central to the story. Analysts expect Sysco's earnings to reach about US$2.9b by around 2029. That compares with earnings of about US$1.8b today, which implies an increase of roughly US$1.1b if the forecasts play out as written and if share count remains broadly stable as assumed in the reports.
Valuation assumptions sit alongside those operating estimates. To match the analyst price targets, Sysco would need to trade at a P/E of 18.7x on the projected 2029 earnings, compared with 22.1x today and modestly above the 18.0x level cited for the wider US Consumer Retailing industry. Those inputs are combined using a discount rate of about 7.5% to 7.55% to bring future cash flows and profits back to a single fair value estimate today.
Sysco's narrative projects about US$96.9b in revenue and roughly US$2.9b in earnings by 2029. This setup assumes yearly revenue growth of 4.7% and an earnings increase of around US$1.1b from about US$1.8b today.
Uncover how Sysco's fair value indicates a 17% potential upside to its current price before that valuation gap closes.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$90 to US$180, so some retail investors see Sysco as close to fully priced, while others model a far richer outcome. When you layer on the Restaurant Depot leverage risk and AI execution as a potential catalyst, you can see how opinions diverge. Explore the different viewpoints before deciding how Sysco fits your portfolio.
Explore 2 other Sysco fair value estimates, including one that suggests it could be worth just $90.31.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sysco research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sysco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sysco's overall financial health at a glance.
Looking for more investment ideas beyond Sysco?
If Sysco has sharpened your focus on what you want from a long term holding, use that same checklist to scan for other stocks that fit your priorities across quality, balance sheet strength and income potential.
- If resilience comes first for you, start by reviewing a 29 resilient stocks with low risk scores that screens for companies with sturdier profiles when it comes to risk scoring and business durability.
- If steady income is the priority, focus on dependable cash payers through a curated 8 dividend fortresses that highlights higher yielding payouts with an emphasis on stability.
- If you want solid finances without overpaying, filter for companies with stronger balance sheets and fundamentals using a targeted list of solid balance sheet and fundamentals (24 results) to broaden your watchlist with options that still pass basic quality checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com