


- UPM-Kymmene Oyj reported third quarter 2026 sales of €2,202 million and net income of €79 million, and issued earnings guidance for second half 2026 comparable EBIT of €375 million to €575 million from continuing operations.
- The combination of higher earnings per share compared with a year earlier and a relatively wide EBIT guidance range gives investors fresh insight into how UPM balances cost pressures, capacity decisions and demand across its pulp, energy, biofuels and paper related activities.
- We will now assess how UPM-Kymmene Oyj’s stronger earnings per share and new EBIT guidance could reshape its broader investment narrative.
UPM-Kymmene Oyj Investment Narrative Recap
To own UPM-Kymmene Oyj, you need to be comfortable with a business that is gradually tilting away from European graphic paper and toward biofuels, biochemicals, clean power and adhesive materials. The key short term swing factor remains how quickly earnings from Energy, Biofuels and specialty materials offset biochemicals start up costs and higher leverage.
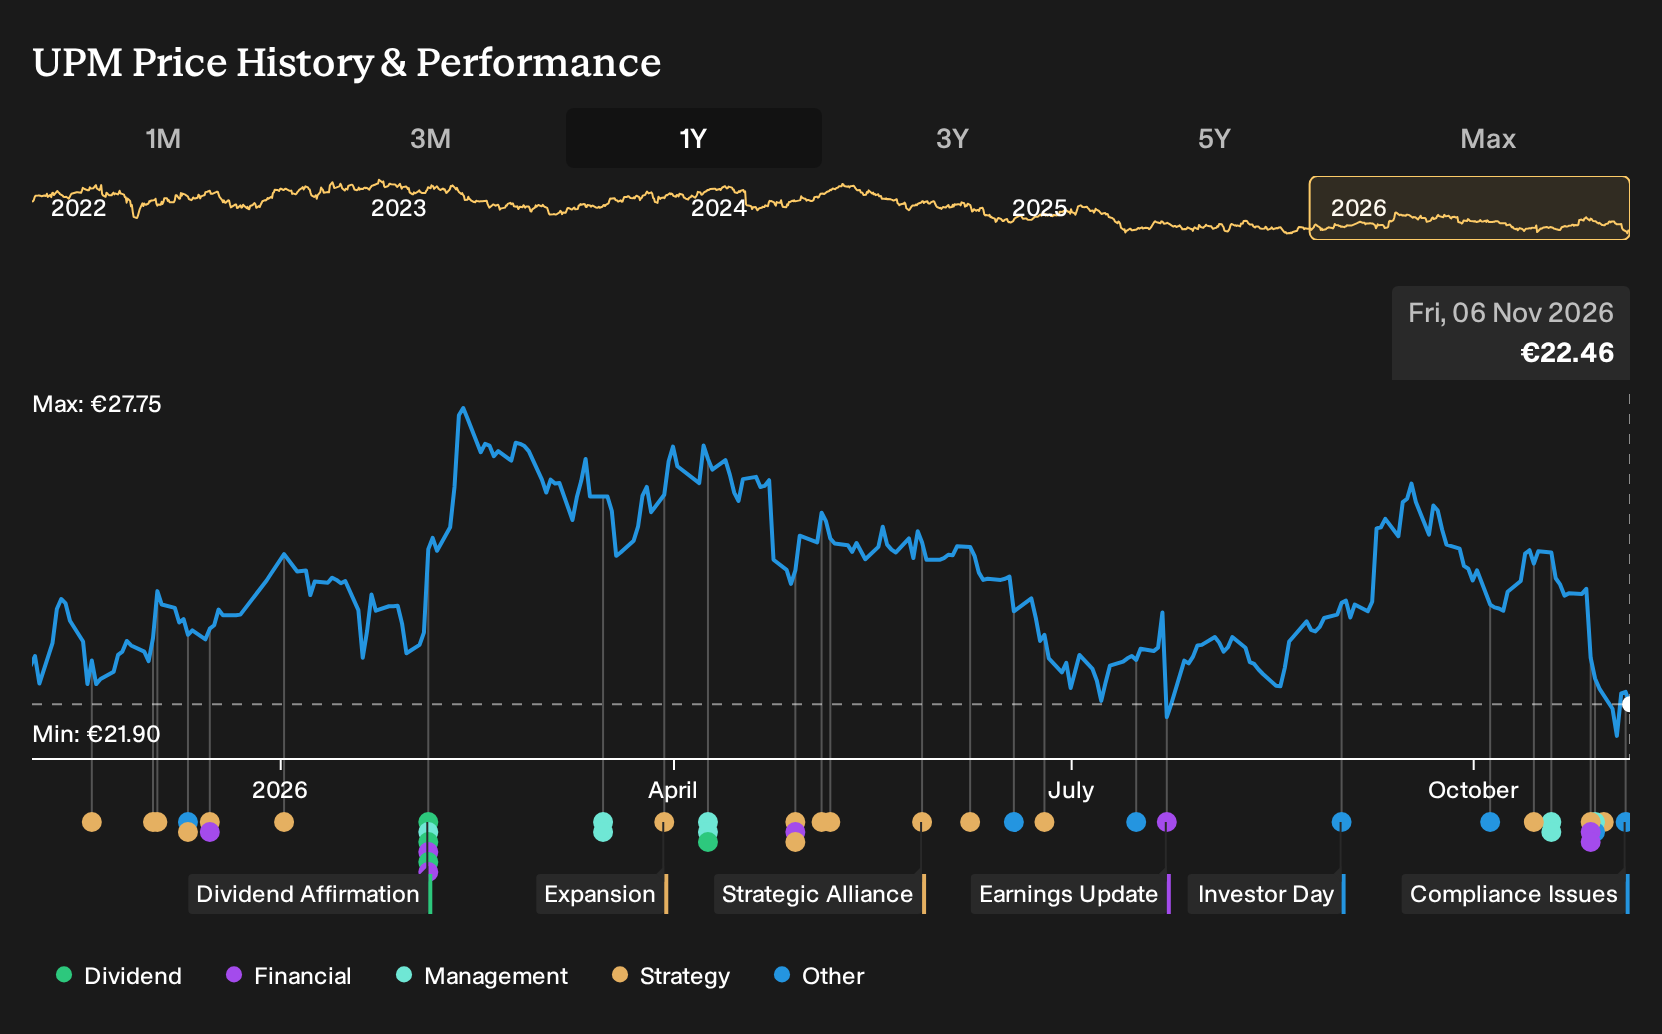
The fresh remedy proposals for the UPM and Sappi graphic paper joint venture do not fundamentally change that near term earnings catalyst. They mainly affect how much and how fast capacity can be adjusted in a market where European graphic paper sales declined 7% in the third quarter of 2026, which keeps execution risk on that portfolio simplification firmly on the table.
The joint venture remedy submission is the clearest operational data point linked to this catalyst. It signals that UPM-Kymmene Oyj is working within the European Commission process to get the Communication Papers exposure into a separate structure, with commitments on capacity optimization, customer safeguards and environmental performance to support a more orderly capacity adjustment.
For you as an investor, the practical question is how this reshaping of the graphic paper footprint interacts with other moving pieces such as Leuna, Biofuels strength and Adhesive Materials expansion in India. The joint venture still hinges on regulatory approval around year end, so regulatory timing and any conditions attached sit alongside project execution and cash flow as the main risks to watch in the near term.
UPM-Kymmene Oyj's current earnings of €686.0 million sit against analyst forecasts for €1.1 billion of earnings and €10.1 billion of revenue by 2029, which implies 1.9% yearly revenue growth and an earnings increase of about €414 million on today's level.
Uncover how UPM-Kymmene Oyj's fair value indicates a 10% potential upside to its current price, which could close sooner than many investors expect.
Exploring Other Perspectives
One alternate view puts the graphic paper joint venture at the center of the UPM-Kymmene Oyj story. The most optimistic analysts were already modeling about €10.9b of revenue and €1.4b of earnings by 2029 before this remedy package. You can treat today’s regulatory news as a fresh test of those upbeat expectations and compare it with your own view.
Explore 2 other UPM-Kymmene Oyj fair value estimates, including one that suggests potential upside of as much as 71% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your UPM-Kymmene Oyj research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for UPM-Kymmene Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate UPM-Kymmene Oyj's overall financial health at a glance.
Looking for more investment ideas beyond UPM-Kymmene Oyj?
If UPM-Kymmene Oyj is on your radar, it can help to line it up against a wider field of opportunities and see where it really earns a place in your portfolio.
- For investors who want potential upside with a margin of safety, compare UPM-Kymmene Oyj with a 224 high quality undervalued stocks that pair solid fundamentals with prices that some might view as attractive relative to their metrics.
- If resilience matters more to you than excitement, weigh UPM-Kymmene Oyj against a 212 resilient stocks with low risk scores that screen for companies with sturdier balance sheets and lower overall risk scores.
- When income is a priority, set UPM-Kymmene Oyj alongside a 232 dividend fortresses that focus on higher yielding payouts that some investors use as a potential source of portfolio cash flow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com