


Energy Fuels (TSX:EFR) has just put several big pieces on the board at once, closing the Australian Strategic Materials acquisition, securing conditional government loan commitments for the Donald project, and greenlighting processing expansions at White Mesa Mill.
Despite these project wins, Energy Fuels’ share price has been under heavy pressure, with a 30 day share price return of down 35.8% and a year to date share price return of down 59%, while the 1 year total shareholder return is down 57.2% as investors weigh larger reported losses against the potential of the rare earth and uranium build out, and react to the Q3 2026 earnings release and board refresh.
Scan how Energy Fuels stacks up against other uranium and rare earth players by checking a curated list of stocks in the 33 best rare earth metal stocks that investors are watching closely.
Energy Fuels is now trading far below both analyst targets and some intrinsic value estimates after this sharp slide. The gap is wide. How much of that discount appears justified once you run through the valuation work?
Most Popular Narrative: 75% Undervalued
Against a last close of CA$9.40, the most followed narrative on Energy Fuels points to a fair value near CA$38.13, implying a large gap that depends on how convincingly management can turn funded projects into future cash flows.
Substantial conditional government backed funding, including a US$725 million loan commitment and other facilities, combined with nearly US$996 million of working capital, can support the capital intensive buildout of White Mesa, the American Metals Plant and related projects in a way that targets long term growth in revenue and potential operating leverage.
See why 63 investors see Energy Fuels as 75% undervalued.
Result: Fair Value of CA$38.13 (UNDERVALUED)
Still, the thesis around Energy Fuels can crack if Donald capex funding falls short, or if the Vacuumschmelze acquisition underdelivers on magnet volumes and pricing.
Find out about the key risks to this Energy Fuels narrative.
Another View: What Multiples Say About Energy Fuels
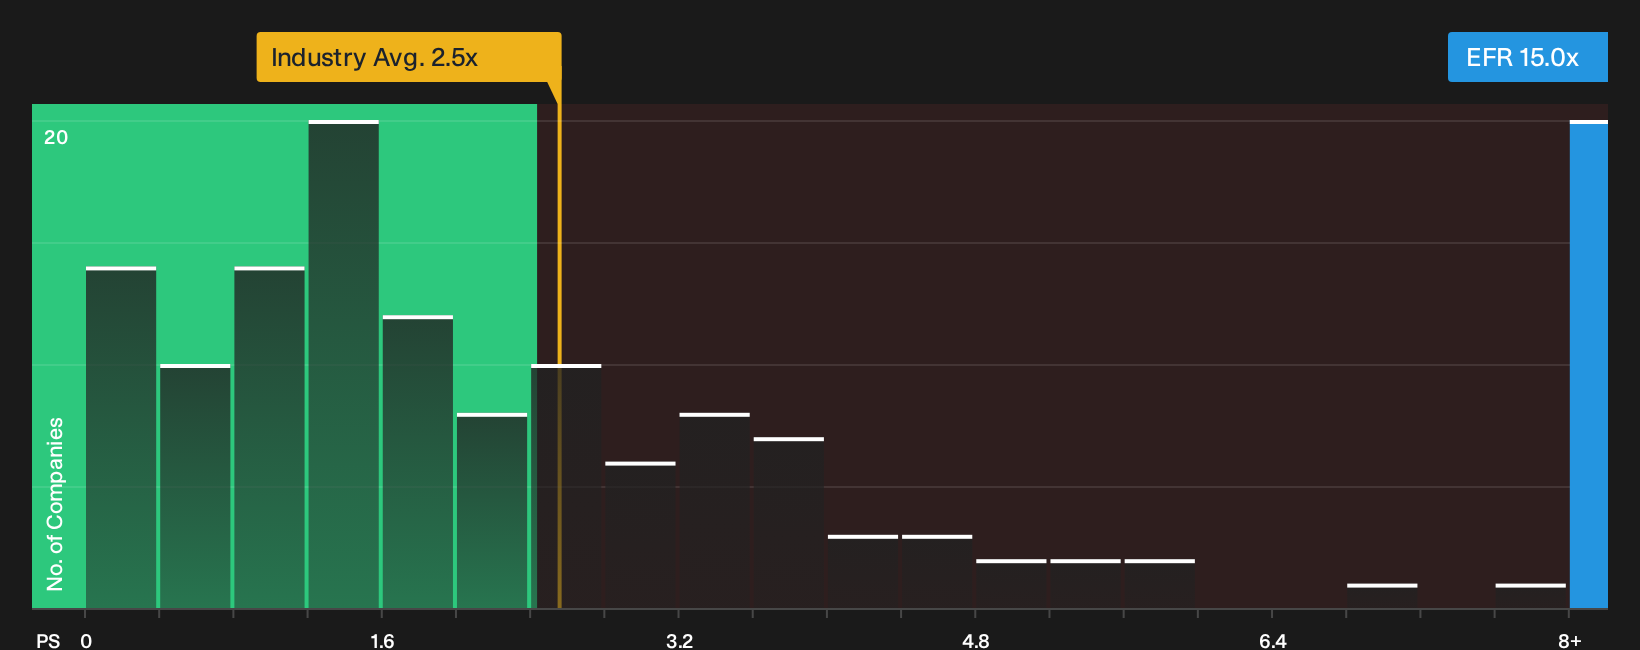
The CA$38.13 fair value narrative presents Energy Fuels as heavily undervalued on future cash flows. On simple sales multiples, the picture is very different. The stock trades on a P/S of 15x, compared with 2.5x for the Canadian Oil and Gas industry, 5.9x for peers, and a fair ratio of 3.7x. If sentiment changes, how comfortable are you owning something this far above what the market has usually paid for similar revenue?
To see how those numbers compare in more detail, including where the fair ratio might influence pricing over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Energy Fuels story so far feels divided between pressure and potential, treat that tension as your cue to inspect the numbers yourself. Before you decide how meaningful those upside drivers really are, review the 2 key rewards.
Looking for more Energy Fuels style investment ideas?
Do not stop with Energy Fuels. Use this moment to widen your watchlist and compare other opportunities side by side using focused Simply Wall Street screeners.
Broaden your hunting ground and review resilient dividend payers that still offer meaningful yield through the 3 dividend fortresses.
Zero in on potential mispricings by scanning a curated 6 high quality undervalued stocks that pair stronger fundamentals with discounted market expectations.
Protect the downside first and sort candidates with healthier finances using a list of solid balance sheet and fundamentals (5 results) before committing fresh capital.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com