


Louisiana-Pacific (LPX) just paired its latest earnings update with a fresh dividend declaration, giving investors new data on both profitability and cash returns as of early November 2026.
Recent trading tells a mixed story for Louisiana-Pacific. The share price has climbed roughly 16.4% over the past month and gained 2.8% over the last week, yet remains down 7.8% year to date. The 3 year total shareholder return of 33.95% points to longer term momentum, which contrasts with the softer 1 year total shareholder return of 2.49% in decline.
Scan how Louisiana-Pacific compares with other building-focused stocks that combine earnings momentum and income potential in our hand picked 8 dividend fortresses.
Bulls point to Louisiana-Pacific’s recent earnings improvement and ongoing dividend, while bears focus on the softer one year return and the earlier nine month earnings drop. Which case does the current valuation lean toward?
Most Popular Narrative: 14% Undervalued
Louisiana-Pacific’s most followed valuation narrative puts fair value at $87.79, above the recent $75.36 close. This frames the current debate around how durable its siding growth story really is.
Accelerated adoption of LP's SmartSide and ExpertFinish trim and siding products, supported by SmartSide volume and revenue compound growth that has outpaced single family housing starts over the past 15 years and by ExpertFinish volumes that grew 35% year over year in Q4 2025, continues to point to potential above market volume growth and stronger long term revenue and gross margin.
See why 13 investors see Louisiana-Pacific as 14% undervalued.
Result: Fair Value of $87.79 (UNDERVALUED)
Still, the story for Louisiana-Pacific can change if housing demand weakens further or if prolonged OSB segment losses continue to weigh on overall profitability.
Find out about the key risks to this Louisiana-Pacific narrative.
Another View: What Multiples Say About Louisiana-Pacific
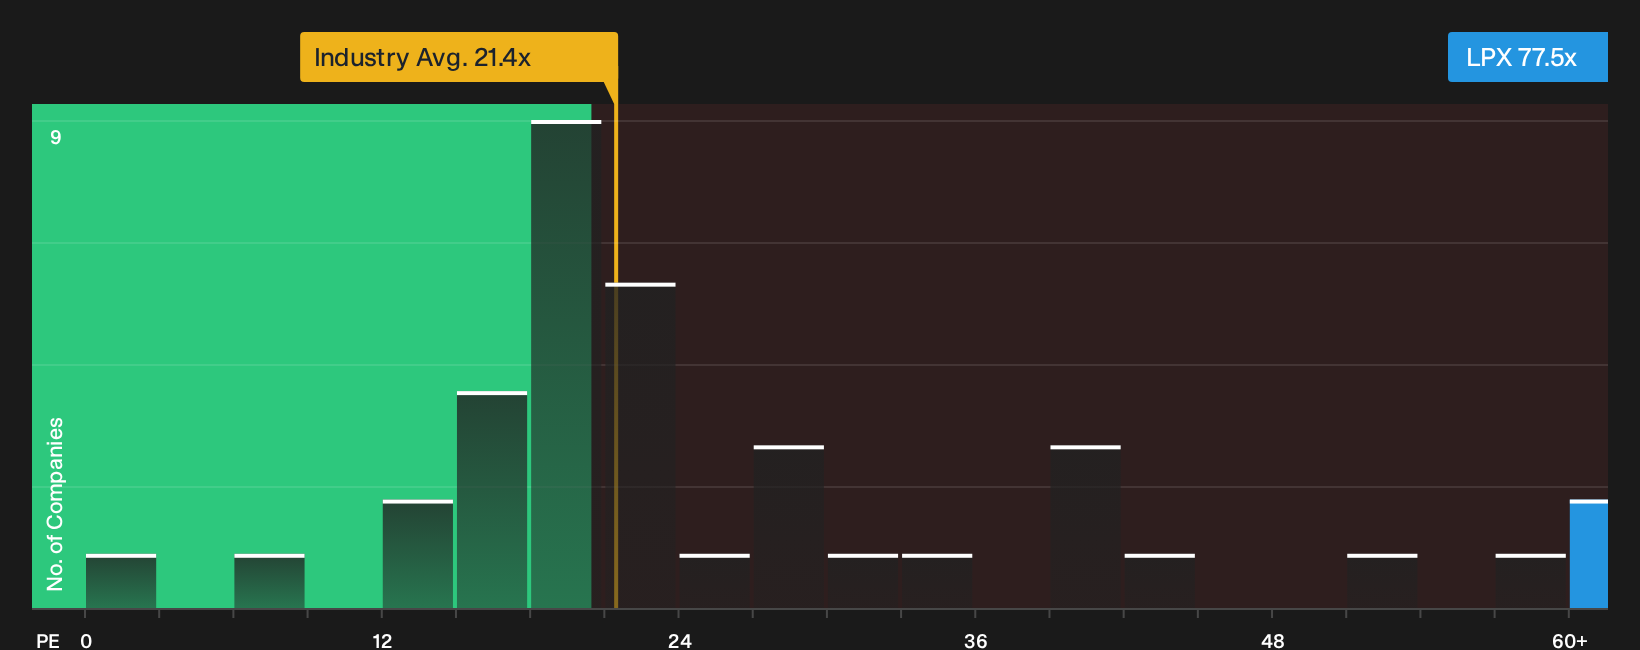
The bullish narrative around Louisiana-Pacific leans on a fair value of $87.79, yet the current P/E of 77.5x tells a very different story. That ratio sits well above the US Building industry at 21.3x, the peer average at 28.9x, and even the fair ratio estimate of 74.1x.
Such a rich earnings multiple can leave little room for disappointment, since any wobble in forecasts or margins can compress the P/E toward industry, peer, or fair ratio levels. The key question is whether you think Louisiana-Pacific has the earnings power to defend that premium, or whether the multiple is doing too much of the heavy lifting.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does this mix of optimism and concern around Louisiana-Pacific match your own read of the situation, or feel a little off? To pressure test that view against both the upside and the red flags, go straight to the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Louisiana-Pacific?
If Louisiana-Pacific has sharpened your focus on quality and valuation, do not stop here. Broader research now can shape much better decisions later.
- Hunt for quality at a discount by scanning companies on our 39 high quality undervalued stocks that combine solid fundamentals with appealing pricing signals.
- Prioritise resilience by checking the list of solid balance sheet and fundamentals (24 results) and zero in on businesses with stronger financial footing.
- Get early to potential future leaders by browsing the 19 high quality undiscovered gems before they land on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com