


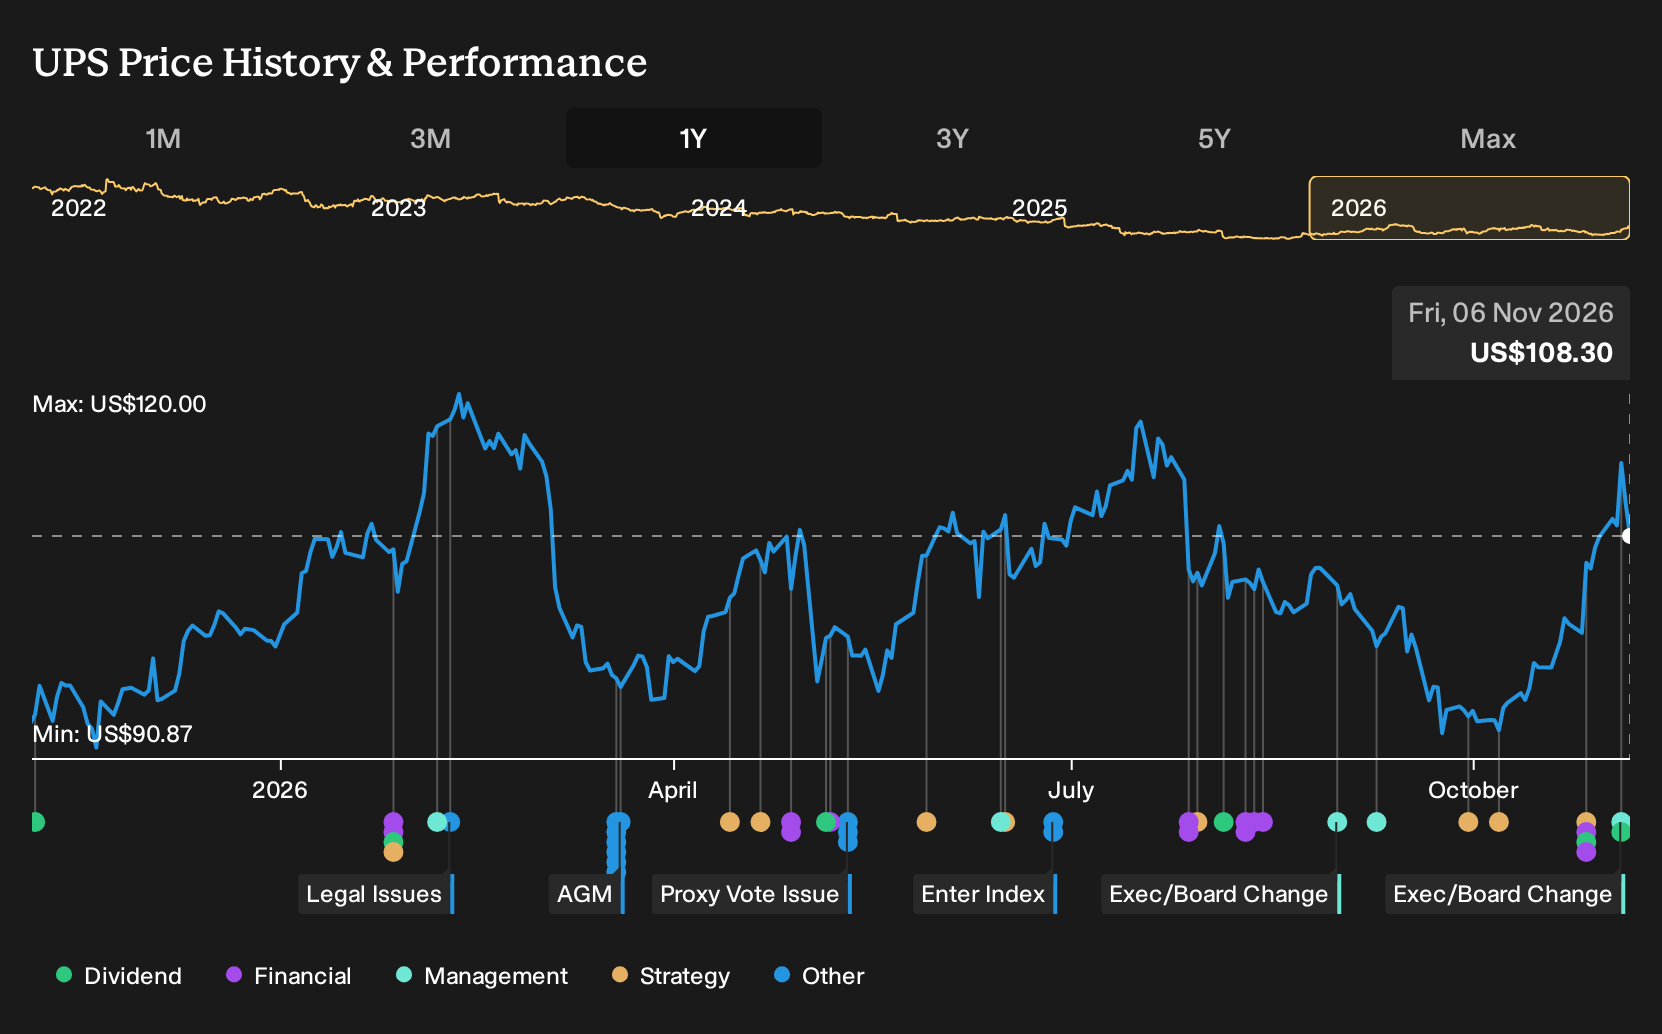
- United Parcel Service reported Q3 2026 revenue of US$22,853 million with lower net income and EPS, raised full year 2026 guidance, confirmed dividend plans of US$1.64 per share for December and outlined US$5.4b in expected 2026 dividend payments, alongside US$182 million of goodwill and asset impairment charges.
- UPS coupled higher revenue guidance and sizeable planned dividends with the appointment of experienced consumer and retail finance leader Shannon Eisenhardt to its board and Audit Committee, signaling a focus on capital discipline and execution while it leans on automation to manage labor, fuel and network cost pressures.
- We will now look at how UPS's raised 2026 guidance and confirmed dividend plans affect the broader investment narrative around the stock.
Scan how UPS compares on dividends, cash flows, and balance sheet strength with other logistics and industrial names using our hand picked list of solid balance sheet and fundamentals (24 results)
United Parcel Service Investment Narrative Recap
To stay invested in United Parcel Service, you need to believe the shift toward higher yielding small and medium business, B2B and healthcare volumes, plus heavier automation, can steadily repair earnings after a period of weaker margins. The raised 2026 guidance and Q3 revenue of US$22,853 million point to management leaning into that efficiency story, even as impairment charges muddy near term optics.
Right now the key short term swing factor is execution on cost per piece and network consolidation while avoiding service issues or labor flare ups. The biggest risk is that elevated labor pressure, building closures and a high dividend commitment restrict flexibility, so automation and mix upgrades fail to translate into cleaner cash generation.
The dividend confirmations are the announcement that matters most for this set of updates. UPS not only declared the regular US$1.64 per share payout for December 3, 2026, it also reiterated expectations of around US$5.4b in dividends for the full year, subject to board approval, alongside higher full year revenue and profit guidance.
For you, that keeps the focus squarely on payout sustainability as a core part of the UPS thesis. A high dividend, combined with sizeable growth and automation investments and Q3 goodwill and asset impairments, tightens the room for error. Any stumble in mix improvement or cost savings could quickly turn the dividend from supporting the story to amplifying balance sheet and execution risk.
United Parcel Service is currently reported to earn US$4.4b, and analysts project earnings of US$7.3b by 2029 on forecast revenue of US$101.8b. This reflects annual top line growth expectations of 3.7% and an earnings increase of about US$2.9b from today.
Uncover why United Parcel Service's fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the UPS story very differently. You see the new director appointment and dividend reaffirmation as signals on governance and cash discipline, while their alternate view leans on faster mix shift and margin expansion. Before this news, they were penciling in US$106.0b of 2029 revenue and US$8.5b of earnings. As a result, those upbeat assumptions may now be tested. Use that spread between consensus and the bullish camp as a prompt to explore several contrasting forecasts before deciding how UPS fits your own plan.
Explore 8 other United Parcel Service fair value estimates, including one that suggests as much as 90% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your United Parcel Service research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for United Parcel Service. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Parcel Service's overall financial health at a glance.
Looking for more investment ideas beyond United Parcel Service?
Once you have a handle on United Parcel Service, it can help to compare its profile with other listed companies that offer different mixes of income, resilience, and upside potential. The Simply Wall St Screener lets you scan for those contrasts quickly so you can pressure test your UPS thesis against a wider watchlist.
- If you want compounding potential with balance sheet support, review companies flagged in our 19 high quality undiscovered gems to see where quality and underfollowed stories meet.
- For investors who care most about resilience and capital protection, filter for businesses in the 29 resilient stocks with low risk scores that pair lower risk scores with more durable fundamentals.
- If income is a key part of your plan, compare UPS against the higher yielding stocks in our 8 dividend fortresses to gauge how its payout stacks up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com