


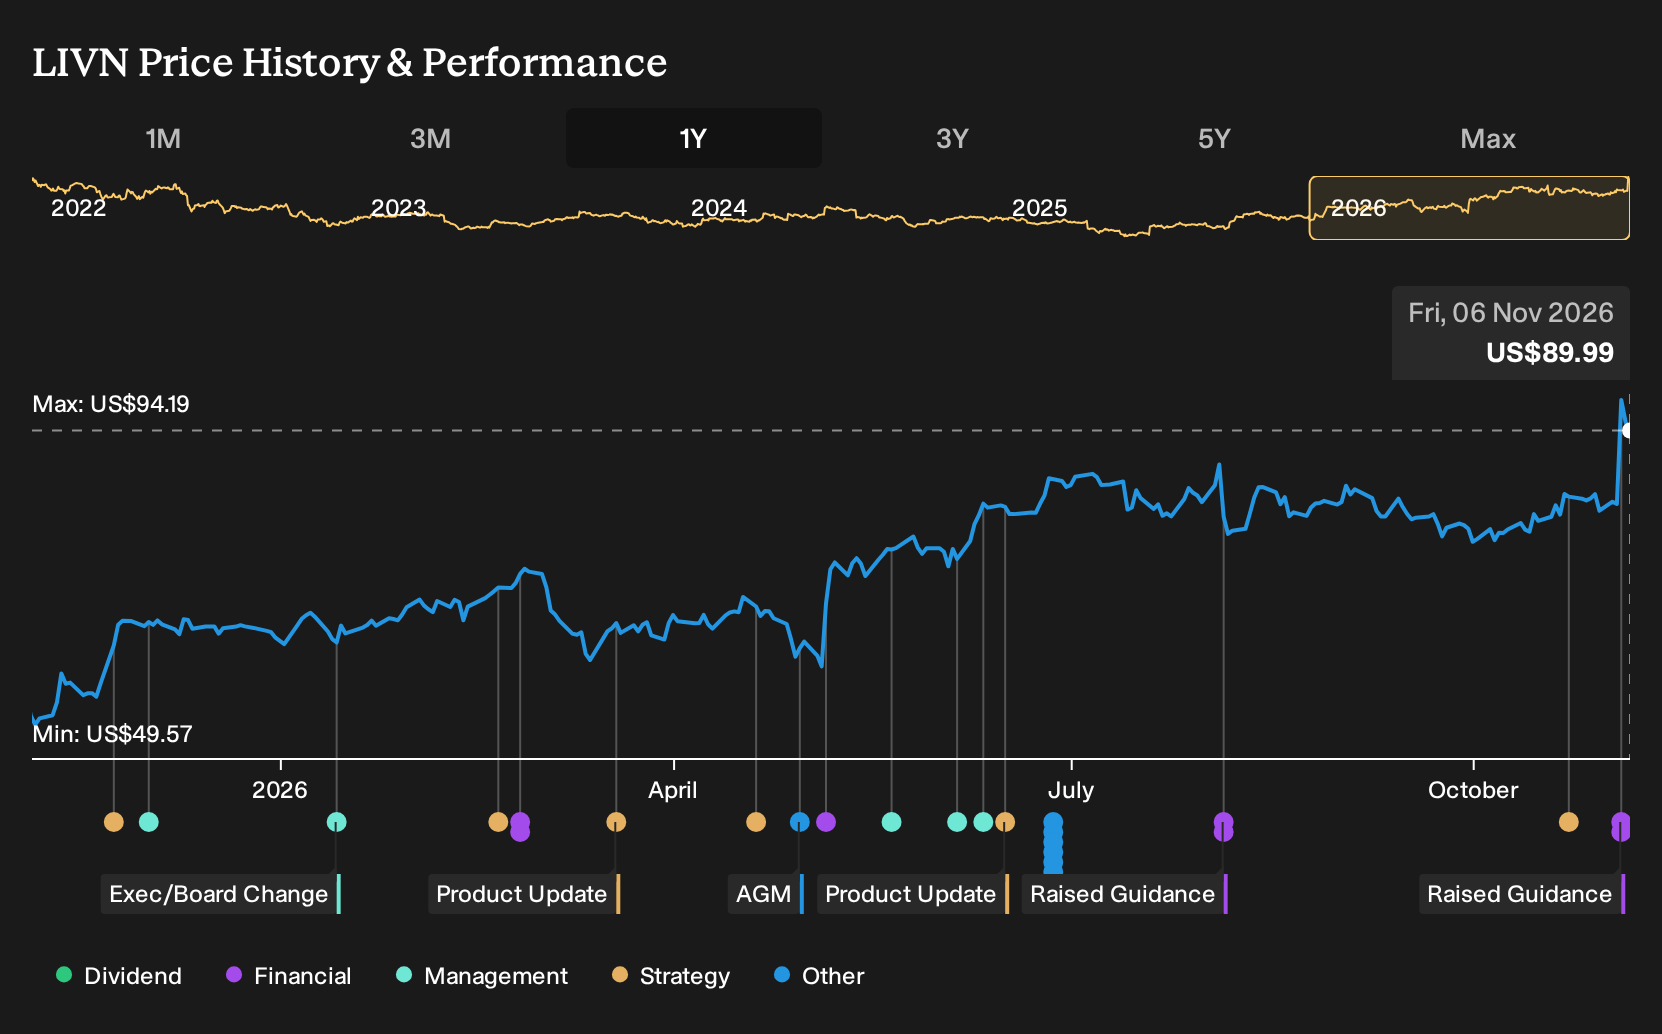
- LivaNova reported third quarter 2026 sales of US$393.15 million and higher net income, raised full year 2026 revenue guidance to 9% to 10% growth on a constant currency basis, and kept foreign exchange tailwinds at about 1% based on current rates.
- The release of multi year CORE VNS data linking LivaNova's neuromodulation therapy to seizure reduction and fewer hospitalizations gave investors a clearer view of how clinical outcomes, capacity investments and pipeline launches like aura6000 could interact with updated earnings guidance.
- We will now look at how LivaNova's raised 2026 revenue and earnings guidance may shift the investment narrative analysts outlined previously.
Scan beyond LivaNova and compare this guidance-driven story with 35 healthcare AI stocks that are also tying medical technology to real-world clinical outcomes.
LivaNova Investment Narrative Recap
LivaNova appeals most if you believe its heavy investment phase can translate into durable growth across cardiopulmonary and neuromodulation. The raised 2026 revenue and earnings guidance points to management seeing enough operational traction to justify higher expectations, but the near term story still hinges on converting capacity, digital and therapy launches into efficient volume.
The key near term swing factor remains execution on elevated capital expenditure and the new oxygenator line rather than this single guidance move. The biggest risk stays the same, VNS exposure to government reimbursement and external cost pressures, so this update refines the outlook but does not fundamentally change the near term thesis.
The third quarter 2026 report is the most relevant event here. Sales of US$393.15 million, higher net income and updated adjusted EPS guidance to US$4.40 to US$4.50 frame the guidance raise inside a very specific operating context rather than as a purely aspirational target.
For you as a shareholder, that link between delivered results, the now operational oxygenator line and tighter earnings guidance matters for assessing near term catalysts. It suggests the main questions now sit around pacing of cardiopulmonary throughput, VNS volume supported by CORE data and how these offset any sustained logistics or tariff headwinds.
LivaNova Forecasts and Valuation Anchors
LivaNova's narrative projects US$1.8b revenue and US$242.2 million earnings by 2029. This assumes 7.7% yearly revenue growth and an earnings increase of about US$53.6 million from US$188.6 million today.
Uncover why LivaNova's fair value indicates alignment with its current price.
Exploring Other Perspectives
Bullish analysts were already banking on a stronger LivaNova neuromodulation story, with revenue growth assumptions of 10.4% a year and earnings near US$255.6 million by 2029, before this guidance hike. You can treat the raised 2026 outlook as a possible catalyst that might push that already optimistic narrative even further, or prompt fresh skepticism.
Explore another LivaNova fair value estimate, including one that suggests as much as 56% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your LivaNova research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for LivaNova. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LivaNova's overall financial health at a glance.
Looking For More Ideas Beyond LivaNova?
If LivaNova has sharpened your thinking about where to deploy capital next, it can help to line it up against other stocks with very different risk and return profiles.
- For investors focused on income resilience, start with companies that aim to pair sturdy cash flows with higher yields through the 8 dividend fortresses.
- If capital preservation and balance sheet strength matter most to you, narrow your universe to businesses with cleaner finances using the list of solid balance sheet and fundamentals (24 results).
- Those hunting for less crowded opportunities can widen their funnel with a 19 high quality undiscovered gems that screens for quality first, then looks at how widely followed each stock is.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com