


Silgan Holdings has climbed 17.2% over the past month, which puts fresh focus on whether the current share price is in line with what its earnings can reasonably support. After a move like that, the key issue for you is whether the recent strength simply reflects the underlying profit power of the business or leans on more optimistic assumptions.
- The 17.2% gain over the last 30 days puts recent momentum front and center, since any further upside from here increasingly depends on how firmly Silgan Holdings' earnings can underpin the new level.
- The group relies heavily on consistent packaging demand and its ability to convert that into steady profits, so the durability of those earnings streams may shape how comfortable investors feel with the current valuation.
- Your read on Silgan Holdings is one view; the desks covering it have another. See what analysts think Silgan Holdings's shares could be worth.
The issue now is whether Silgan Holdings' earnings are strong enough, and reliable enough, to justify where the stock trades today.
If you want to pressure test Silgan Holdings' recent move against other companies on earnings support, compare it with 39 high quality undervalued stocks.
Does Silgan Holdings Look Undervalued on Earnings?
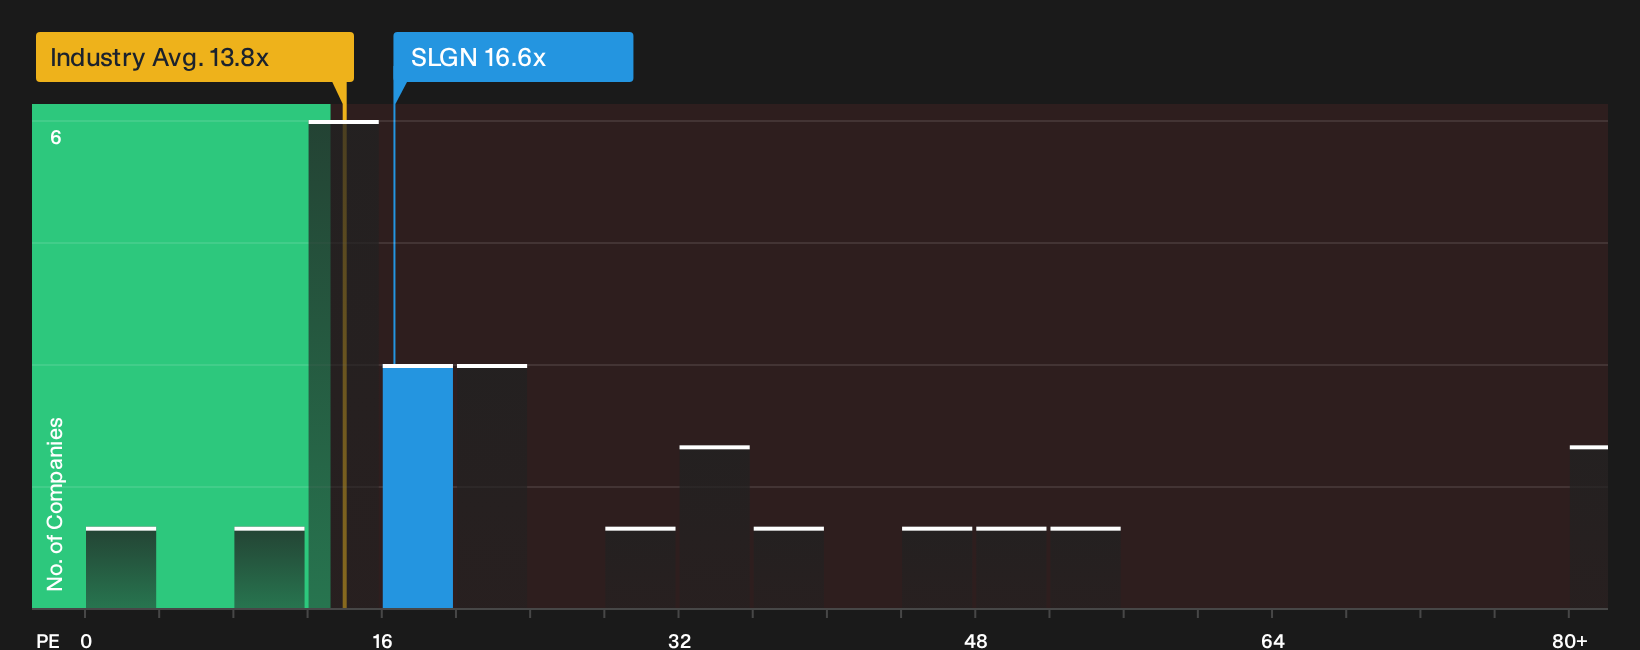
The P/E ratio suits Silgan Holdings because earnings remain the main lens investors use for a mature packaging group with established cash generation. The stock trades on a P/E of 16.6x, which is above the packaging industry average of roughly 13.8x yet below the wider peer group average of about 29.5x. That puts the shares in an interesting middle ground where the market is asking for some quality premium over the sector, but not paying up at the richer levels seen for other comparables.
The fair value framework, which adjusts the P/E you might expect for Silgan Holdings based on its margins, risk profile and scale, points to a higher ratio than where the stock trades today. On this yardstick the current P/E suggests the shares screen undervalued rather than expensive, even after the recent move. The key question for you is whether the earnings profile you see is strong enough to close that gap over time. Explore the numbers behind Silgan Holdings's P/E valuation.
The Silgan Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Silgan Holdings leaves off by spelling out which earnings, margin and growth paths would need to play out for the stock to be worth materially more or less than it is today on the market. Each idea links its implied value to a clear view on how Silgan Holdings' growth, profitability and risk profile might evolve, giving you a reference point you can revisit as fresh information arrives on the Community page.
Silgan Holdings splits opinion between those who see contracted, higher margin packaging projects as underappreciated and those who think cost pressure and weaker volumes still bite.
Bull case: 21% undervalued
"Contracted growth in fine fragrance and beauty dispensing, including recent double-digit organic volume growth and much of the 2027 business already secured, points to a multi-year pipeline..."
Discover why this Narrative puts Silgan Holdings at 21% undervalued.
Bear case: 7% overvalued
"A 15% volume decline in Brazil in Q2 2026 that reduced segment EBIT by about US$5 million shows how weakness in a single regional market can offset growth projects..."
Explore why this Narrative puts Silgan Holdings at 7% overvalued.
One more angle on Silgan Holdings that could shift how you see it
Valuation only tells part of the story for Silgan Holdings, because the people directing capital and how they are rewarded can shape outcomes just as much as the multiples you see today. See who runs Silgan Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com