


- Amazon replaced Grubhub with Uber Eats as the restaurant delivery partner for Prime members, offering $0 delivery fees on eligible Uber Eats orders for subscribers.
- This shift deepens the integration between Amazon and Uber and raises fresh competitive pressure on DoorDash’s U.S. restaurant business, particularly among high frequency Prime diners.
- We will examine how DoorDash’s investment narrative holds up against Amazon’s new $0 fee Uber Eats benefit for Prime members.
DoorDash Investment Narrative Recap
For someone holding DoorDash, the big belief is that food delivery, grocery and other new verticals, plus subscriptions and advertising, can turn a large user base into a broader profit pool. The Amazon and Uber Eats partnership tests that thesis in restaurants, although DoorDash still carries significant app spend share and just reported higher quarterly sales and net income, which anchors the near term story.
The near term catalyst sits in execution on grocery, retail, international and advertising, where management has flagged progress toward gross profit positivity. The biggest risk remains regulatory and affordability pressure that could raise Dasher and compliance costs or limit pricing power, especially as promotions from Amazon and Uber sharpen consumer price sensitivity.
The Lyft Go launch with DashPass looks especially relevant right now. Amazon tied Prime to Uber Eats, and Lyft responded by tying its riders to DoorDash. For US$9.99 a month, Lyft Go with DashPass gives members 8% credits on rides, redeemable on Lyft rides or DoorDash orders, plus full DashPass delivery perks.
This matters for the catalyst around subscriptions and higher margin revenue. DashPass already contributes recurring, stickier demand, and Lyft Go effectively turns frequent Lyft users into a warm funnel for DoorDash without DoorDash running its own rideshare service. The risk is that aggressive credits and benefits add churn in promotions and weigh on unit economics if not managed carefully.
DoorDash Forecasts Versus Analyst Assumptions
DoorDash's narrative projects US$28.0b revenue and US$3.8b earnings by 2029. That outlook aligns with analyst assumptions of 20.8% yearly revenue growth and an earnings increase of roughly US$3.0b from US$841.0m today.
Uncover why DoorDash's fair value indicates a 43% potential upside to its current price before that discount gap closes.
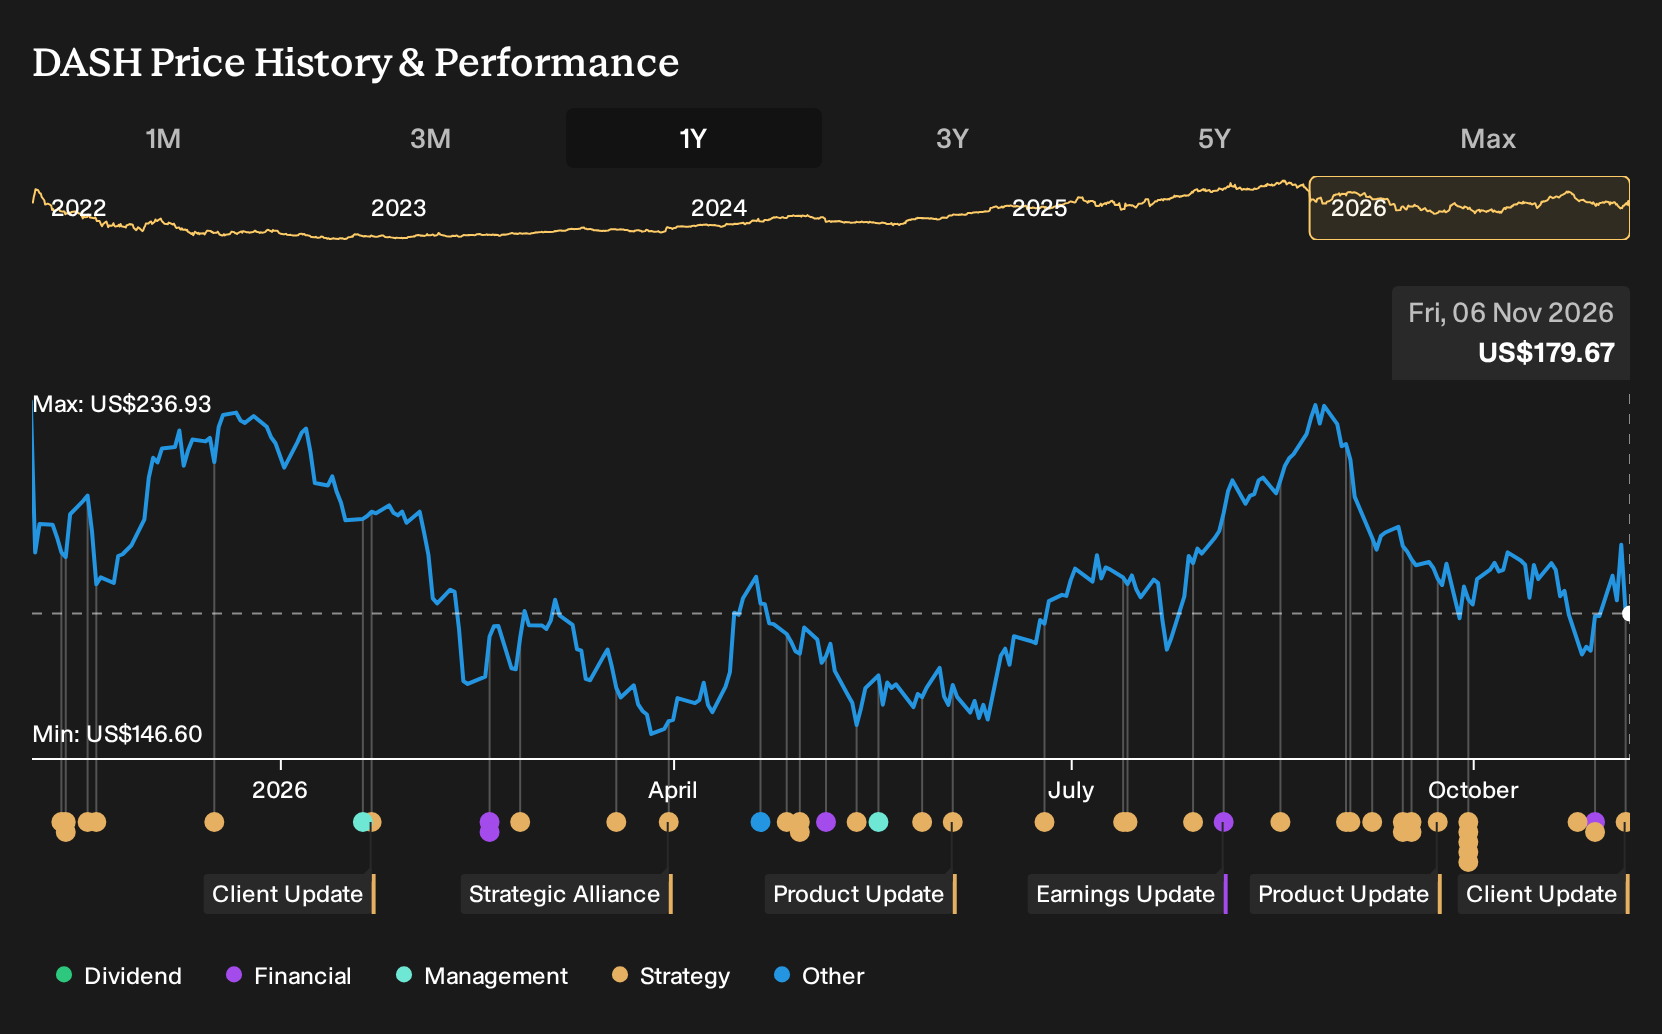
Exploring Other Perspectives
One alternate view focuses on margin pressure rather than subscriber growth. The most bearish DoorDash analysts were only modeling revenue of about US$27.9b and earnings of roughly US$2.9b by 2029 before the Amazon and Uber Eats news. That is a far more cautious story. Use this Lyft Go moment to compare those forecasts and decide which narrative feels closer to your own expectations.
Explore 6 other DoorDash fair value estimates, including one that suggests it could be worth just $226.02!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your DoorDash research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DoorDash. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DoorDash's overall financial health at a glance.
Looking for more investment ideas beyond DoorDash?
If this DoorDash story has you rethinking where you want exposure in your portfolio, it can help to broaden the radar and line up a few different types of opportunities side by side.
- Prefer resilient businesses that aim to limit downside risk and smooth the ride? Filter for those profiles with the 29 resilient stocks with low risk scores.
- Want to focus on quality plus valuation discipline? Sort through a 39 high quality undervalued stocks that may combine stronger balance sheets with attractive pricing.
- Income is more your style and you care about cash coming back to you? Scan a 8 dividend fortresses that prioritises higher yielding payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com