


Dorman Products (DORM) has investors weighing two different signals. Updated guidance points to more modest full year expectations, while a new OE FIX oil filter housing underlines ongoing product expansion.
The guidance revision in late October and the fresh OE FIX launch now sit against a mixed tape for Dorman Products, with the share price up 11.26% over 30 days but down 2.99% over 90 days, while the 3 year total shareholder return of 104.37% contrasts with a far more modest 1 year total shareholder return of 1.79%. This suggests that long term momentum has cooled even as shorter term interest has picked up again.
Spot opportunities that mirror Dorman Products' balance between tempered guidance and product expansion by scanning our hand picked 19 high quality undiscovered gems in the auto and industrial space.The recent bounce in Dorman Products after softer guidance and solid product news raises a simple puzzle. Are investors rerating the business, or just swinging with sentiment as the valuation shifts?
Most Popular Narrative: 15.4% Undervalued
The most followed narrative on Dorman Products pegs fair value at $161.63, above the last close at $136.70. This frames the recent share swings against a still supportive long term thesis built around margins, balance sheet strength and aftermarket demand.
A strong balance sheet with net leverage of 0.69x adjusted EBITDA, total liquidity of US$931m, and ongoing share repurchases with more than US$300m of authorization remaining through 2027 gives Dorman Products room to pursue M&A and retire shares, which can support revenue scale and earnings per share growth.
See why 7 investors see Dorman Products as 15% undervalued.
Result: Fair Value of $161.63 (UNDERVALUED)
Still, the bullish Dorman Products storyline can crack if softer 2026 sales guidance and any renewed tariff cost shock persist longer than analysts currently model.
Find out about the key risks to this Dorman Products narrative.
Another View: Multiples Paint A Richer Picture For Dorman Products
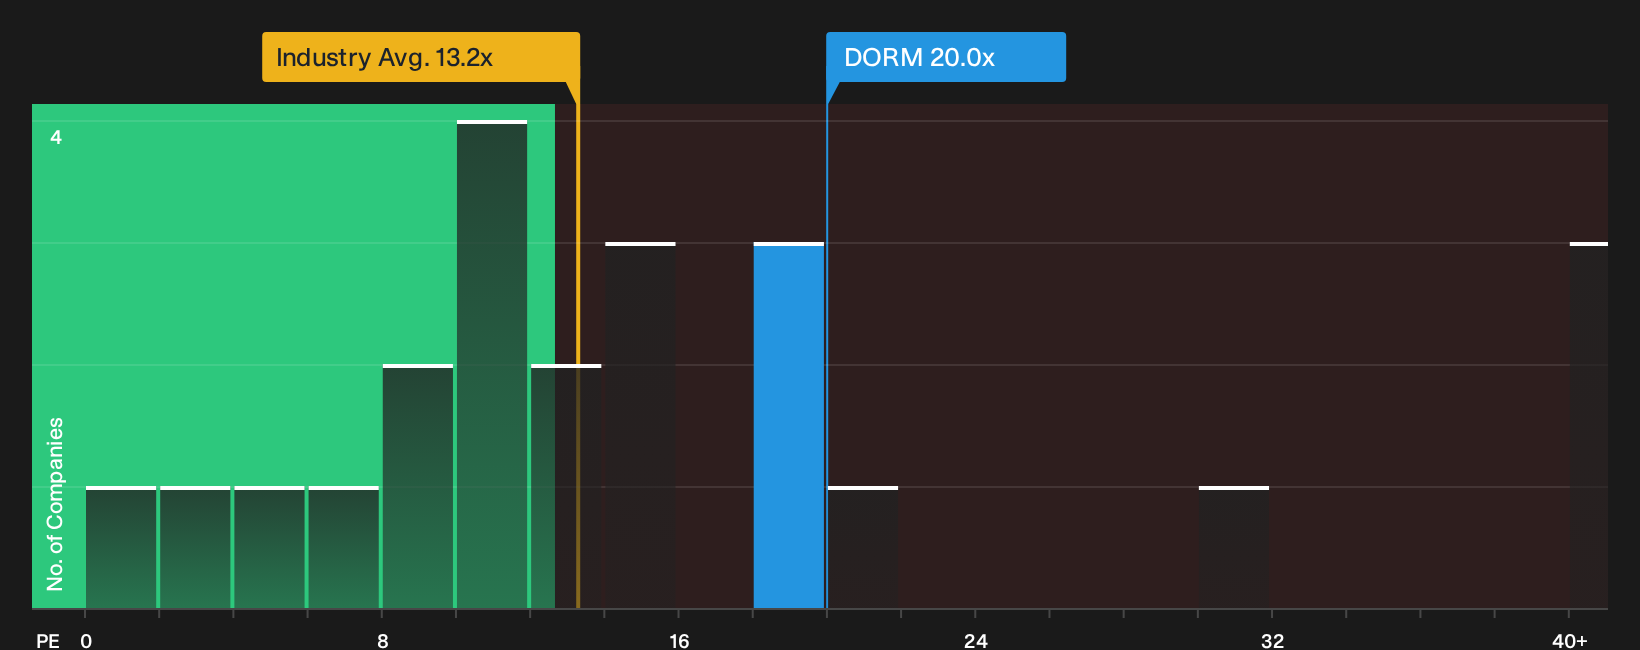
The bullish fair value story on Dorman Products runs into a very different signal once the focus shifts to the current P/E. The stock trades at about 20x earnings, compared with 13.7x for the US Auto Components group, peers at 8.8x and a fair ratio estimate of 13.3x. That kind of premium can mean investors are paying upfront for a lot of good news, so the key question is how comfortable you are with that valuation gap if execution wobbles again.
For a closer look at how this pricing compares and what the fair ratio gap could mean in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Dorman Products is split, so this is the moment to move quickly, review the numbers yourself, and pressure test every story. To see which potential upsides are driving optimism and weigh them against your own thesis, check out the 2 key rewards.
Looking For More Investment Ideas Beyond Dorman Products?
If you stop with Dorman Products, you risk missing other setups where the numbers, balance sheets, and cash flows line up just as cleanly for your watchlist.
- Target resilient cash generators by scanning the 39 high quality undervalued stocks that pair quality fundamentals with prices that still look reasonable on the numbers.
- Strengthen your income stream by reviewing the 8 dividend fortresses that focus on higher yielding payouts backed by robust financial profiles.
- Dial down portfolio stress by filtering for the 29 resilient stocks with low risk scores that score well on balance sheet strength and lower volatility traits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com