


- Oxford Instruments has seen its Severn Beach compound semiconductor facility move to full operation, supporting significant order intake and new high volume commercial wins in its Advanced Technologies division.
- The news points to Oxford Instruments increasingly tying its equipment to multi year production programs for compound semiconductors used in datacom and AI related applications. This concentrates execution risk around capacity ramp up and operational efficiency.
- We will now explore how Oxford Instruments' fully operational Severn Beach compound semiconductor facility could influence the broader investment narrative around the business.
Scan beyond Oxford Instruments and compare this AI and datacom capacity story with 52 AI infrastructure stocks.
Oxford Instruments Investment Narrative Recap
To hold Oxford Instruments, you need to be comfortable with a business that is skewing toward commercial compound semiconductor and AI related datacom programs, and relies on turning a strong order book into clean execution. The fully operational Severn Beach facility supports that story by giving Advanced Technologies more room to serve multi year volume commitments.
In the near term, the key swing factor is how efficiently Severn Beach ramps, because any bottlenecks could push revenue and margin contribution into later periods. The biggest risk remains a slowdown or cancellation in customer programs, which would test how quickly current contracted work converts into cash and reported earnings.
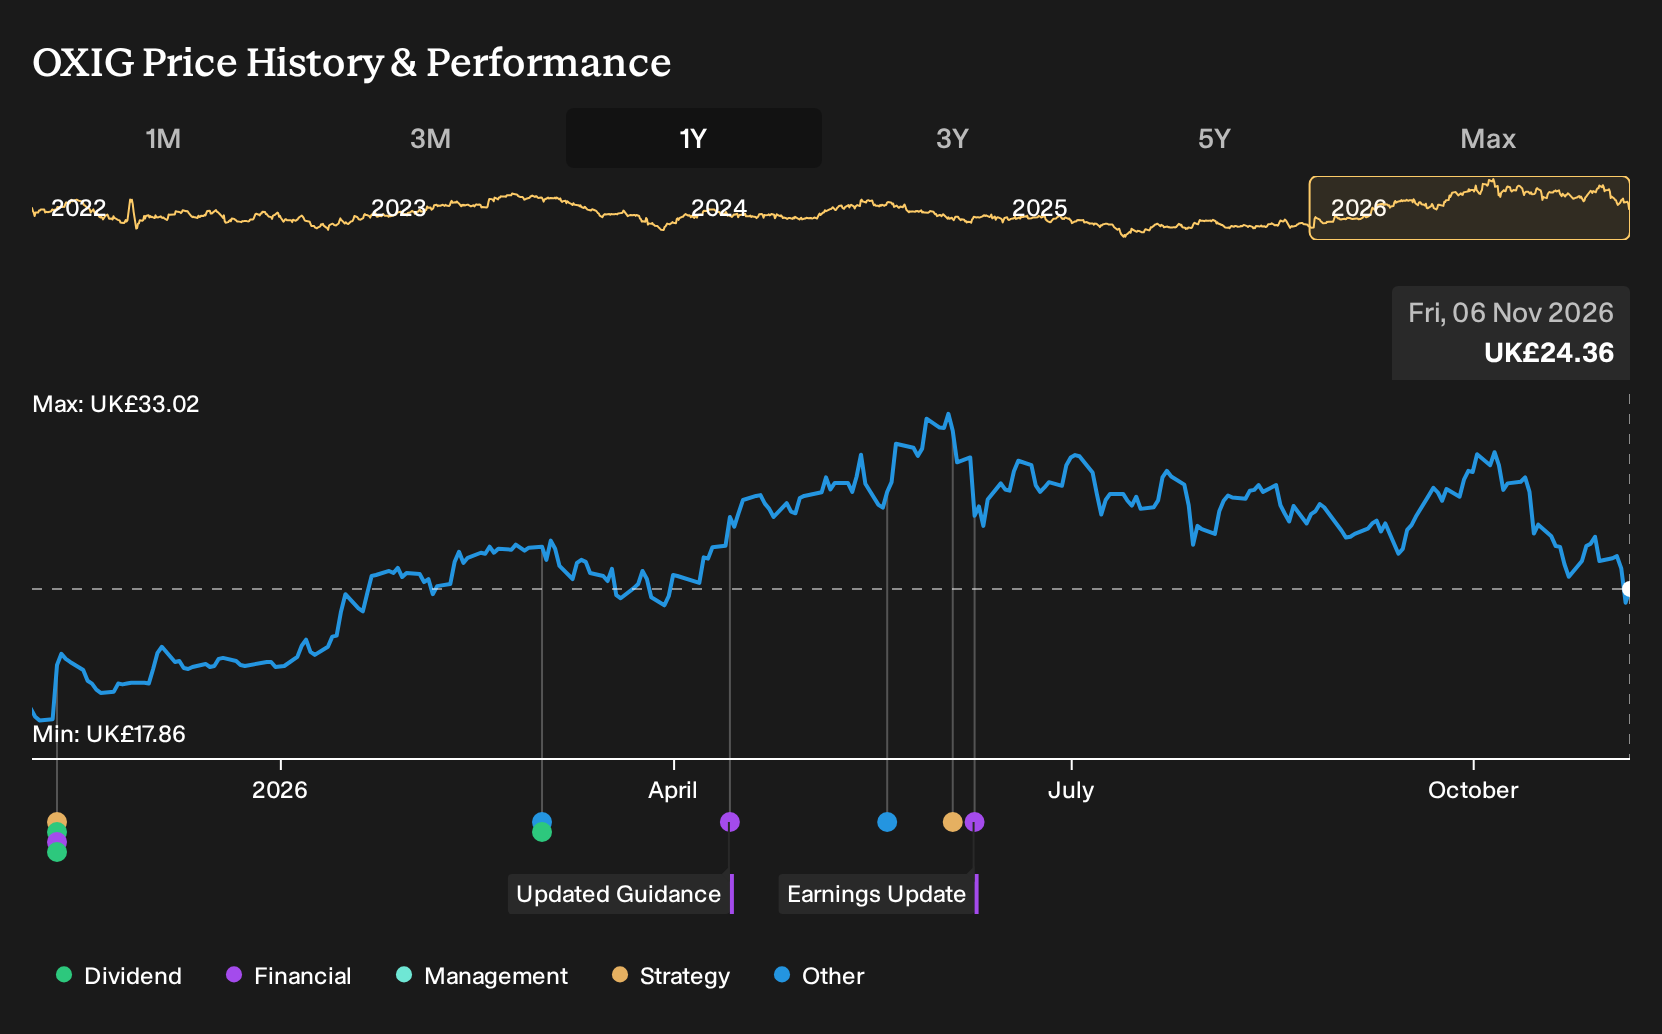
The most relevant recent data point is that Oxford Instruments’ share price has risen 37.7% over the past year, while a Discounted Cash Flow model indicates the stock trades broadly in line with estimated intrinsic value. That suggests the market has already acknowledged the stronger operational footprint, including Severn Beach, without stretching the valuation beyond modelled cash flows.
For you as an investor, that combination puts the spotlight firmly on delivery. The Severn Beach driven order growth and high volume commercial wins make operational execution, margin discipline and order conversion speed the practical catalysts to watch, rather than multiple expansion or fresh announcements in the short run.
What The Oxford Instruments Consensus Is Pricing In
Oxford Instruments' narrative projects £506.8 million revenue and £73.1 million earnings by 2029. Analysts are assuming 6.2% yearly revenue growth and an earnings increase of about £28.6 million, from £44.5 million today to reach that forecast level.
Uncover how Oxford Instruments' fair value indicates a 32% potential upside to its current price, which could narrow quickly if Oxford Instruments keeps delivering against current expectations.
Exploring Other Perspectives
Some of the most optimistic analysts frame Severn Beach as a potential earnings accelerator for Oxford Instruments rather than a bottleneck risk. Before this news, the bullish camp was already pencilling in about £551.9 million of revenue and £78.4 million of earnings by 2029. You can read that as a more aggressive take on how fully utilised capacity and richer service income might reshape the story. Those views were set before Severn Beach moved to full operation, so opinions may evolve as fresh data comes through. Make sure you compare several narratives before deciding how this fits into your own thesis.
Explore 3 other Oxford Instruments fair value estimates, including one that suggests as much as 44% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and approach decisions carefully.
- A great starting point for your Oxford Instruments research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Oxford Instruments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Oxford Instruments' overall financial health at a glance.
Looking For More Investment Ideas Beyond Oxford Instruments?
If the Oxford Instruments story has sharpened your focus on quality and execution, it can be worth widening the lens and comparing it with other opportunities that share similar strengths or offer different types of risk and reward. The Simply Wall St Screener gives you curated sets of companies that match specific filters so you can pressure test your thesis across a wider watchlist.
- If capital preservation and steady compounding matter most to you, consider starting with a basket of 4 resilient stocks with low risk scores that score well on resilience and financial stability.
- For investors who want quality but still care about price discipline, a good next step can be scanning a 15 high quality undervalued stocks that combine solid fundamentals with more modest expectations baked into the share price.
- Those hunting for mispriced quality stories off the beaten track might prefer to comb through a 5 high quality undiscovered gems that pair strong business metrics with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com