


First Mid Bancshares (FMBH) just paired a regular quarterly dividend of $0.26 per share with third quarter results that showed higher net interest income and net income than the same period last year.
First Mid Bancshares shares trade at US$50.61 after a mild pullback over the past quarter, yet the 31.01% year to date share price return and 40.72% 1 year total shareholder return suggest momentum has been building as investors respond to stronger earnings, reduced net charge offs, and a maintained dividend stream.
Compare First Mid Bancshares’ momentum and dividend profile with a curated group of resilient bank and finance stocks using the 29 resilient stocks with low risk scores for ideas with lower risk scores.
After a strong run and a modest recent pullback, First Mid Bancshares now forces a familiar decision. Is this a fair entry after the earnings jump, or does patience for a cheaper valuation make more sense?
Price-to-Earnings of 12.1x: Is it justified for First Mid Bancshares?
On simple earnings terms, First Mid Bancshares trades on a P/E of 12.1x, which is slightly higher than the 11.3x average for US banks but below the 13.6x peer group level. That puts the stock in an in-between zone where investors are paying a small premium to the broader sector while still getting a discount to closer peers.
The P/E ratio measures how much investors are willing to pay today for each dollar of earnings generated by the business. For a regional bank like First Mid Bancshares with community banking, lending, wealth management, and insurance operations, this multiple often reflects expectations around earnings stability, credit quality, and how management steers growth without stretching the balance sheet.
Recent fundamentals give some context to that 12.1x figure. Earnings grew 27.3% over the past year and have compounded at 11.4% per year over the past 5 years. Net profit margins sit at 28.2%, which is higher than last year’s 26%. Forecasts point to earnings growth of 15.1% per year, which is slower than the broader US market but still positive, and revenue is projected to rise 2.1% annually. Against that backdrop, the current multiple suggests the market is willing to pay a modest premium to the wider US Banks industry, and the fair P/E estimate of 13x indicates investors could justify a slightly higher level if these profit trends hold.
The comparison is clear. The stock is priced richer than the broad US Banks industry on P/E, yet cheaper than its peer average and below the 13x fair ratio that the SWS fair value model suggests the market could gravitate toward if confidence in the earnings profile remains steady.
Explore the SWS fair ratio for First Mid Bancshares.
Result: Price-to-Earnings of 12.1x (ABOUT RIGHT)
Still, the First Mid Bancshares story could be knocked off course by credit quality setbacks or weaker loan demand that pressures earnings and challenges the current valuation.
Find out about the key risks to this First Mid Bancshares narrative.
Another View on First Mid Bancshares Valuation
The P/E work suggests First Mid Bancshares is roughly fairly priced, yet the SWS DCF model paints a very different picture. With the shares at $50.61 and an estimated future cash flow value of $100.43, the model points to the stock trading at a 49.6% discount. Which signal do you trust more for your own process?
Look into how the SWS DCF model arrives at its fair value.
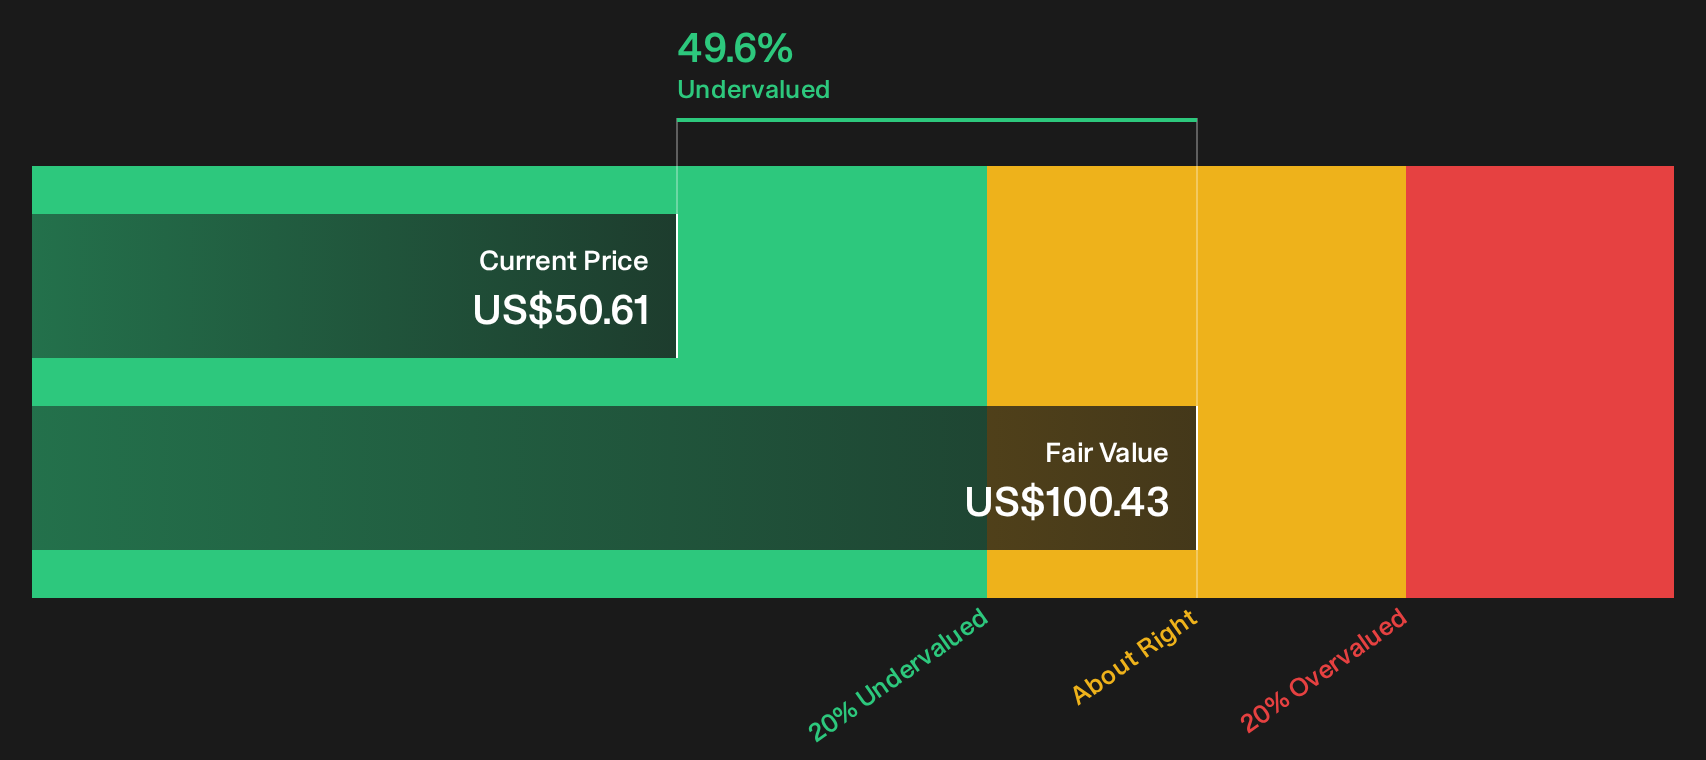
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Mid Bancshares for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 39 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on First Mid Bancshares is mixed, with both bright spots and pressure points in view. Consider moving quickly, study the numbers yourself, and weigh the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond First Mid Bancshares?
If First Mid Bancshares has your attention, do not stop here. Cast the net wider so you are not relying on a single opportunity.
Use the Simply Wall St Screener to hunt for fresh ideas that fit different roles in your portfolio and spot candidates you might otherwise miss.
- Target quality at a discount and scan a curated pool of potential value opportunities through the 39 high quality undervalued stocks.
- Strengthen your income stream by reviewing companies with robust payouts using the focused 8 dividend fortresses.
- Prioritize financial resilience and seek out businesses with healthier balance sheets through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com