


- Intuitive Surgical appointed Aaron Martin, currently President of Insurance at Humana and former Amazon healthcare executive, to its board effective January 1, 2027. This expands the board from 10 to 11 directors and adds deep experience across payer, provider and digital health businesses.
- Martin’s track record building telehealth platforms, health system digital tools and a corporate venture fund gives Intuitive Surgical added insight into how hospitals, payers and technology partners think about affordability, workflow and data, which are central to long term demand for robotic procedures.
- We will look at how Intuitive Surgical’s earnings driven investment narrative is influenced by a stronger procedure outlook and refreshed board expertise.
Scan beyond Intuitive Surgical and size up other robotics and automation players showing fresh momentum with our curated 89 robotics and automation stocks list.
Intuitive Surgical Investment Narrative Recap
For Intuitive Surgical, the big picture to consider is that robotic procedures keep expanding across more hospitals, specialties and geographies. This supports recurring instruments, accessories and service revenue. The main near term swing factor remains procedure growth on da Vinci and Ion, including how quickly newer systems and cost per procedure initiatives are adopted by budget constrained hospitals.
Aaron Martin’s appointment looks incremental rather than a catalyst that shifts the next few quarters on its own. The near term risk profile still leans heavily on capital spending pressure in markets such as China and Europe, and on how aggressively new soft tissue competitors and third party instrument providers influence pricing and system purchase decisions.
The most relevant recent datapoint alongside this governance change is Intuitive Surgical’s expectation for da Vinci procedure growth of 14% to 15% for full year 2026 and a 15% revenue increase targeted for Q4 2026. That is where short term investor attention is likely to sit, because utilization and procedure throughput feed directly into the high margin recurring stream.
Viewed through that lens, adding Martin’s payer, provider and telehealth background appears tied to sharpening execution around affordability, workflow and digital tools, rather than changing core product priorities. Delivery against the upcoming Q4 2026 report and any update on operating expenses, China trends and the broader soft tissue surgery opportunity still appear to be the key operational markers to watch.
What The Current Intuitive Surgical Forecasts Assume
Intuitive Surgical's narrative projects US$15.5b revenue and US$4.8b earnings by 2029. This implies 11.9% yearly revenue growth and an earnings increase of about US$1.7b from US$3.1b today.
Analysts are effectively sketching a picture where Intuitive Surgical grows into a much larger surgical platform business over the next few years, without relying on dramatic shifts in its current playbook. Revenue is modeled to compound at 11.9% a year, which implies a steady lift in procedure volume, system placements and related services rather than a one off spike. The forecast for profit margins to move from 28.4% today to 30.7% by 2029 also assumes Intuitive Surgical can keep cost per procedure initiatives, manufacturing efficiency and mix improvements working in its favor.
The earnings bridge from US$3.1b today to a US$4.8b consensus target by 2029 represents roughly a US$1.7b step up in annual profits. That jump is tied not only to the topline growth assumption but also to the expectation that higher margin recurring items, including instruments, accessories and digital offerings, keep taking a larger share of the total. The forecast also bakes in a modest reduction in share count, with analysts assuming outstanding shares decline by 0.34% per year, which would give a small lift to earnings per share if it plays out.
On these inputs, the implied P/E story matters as much as the growth story. Analysts are anchoring on Intuitive Surgical trading at about 43.5x those 2029 earnings, slightly lower than the 44.3x multiple referenced for today but still well above the 24.8x cited for the broader US medical equipment group. That gap suggests the current model rests on Intuitive Surgical preserving a premium valuation that reflects its recurring revenue mix, margin structure and perceived durability of its procedure ecosystem.
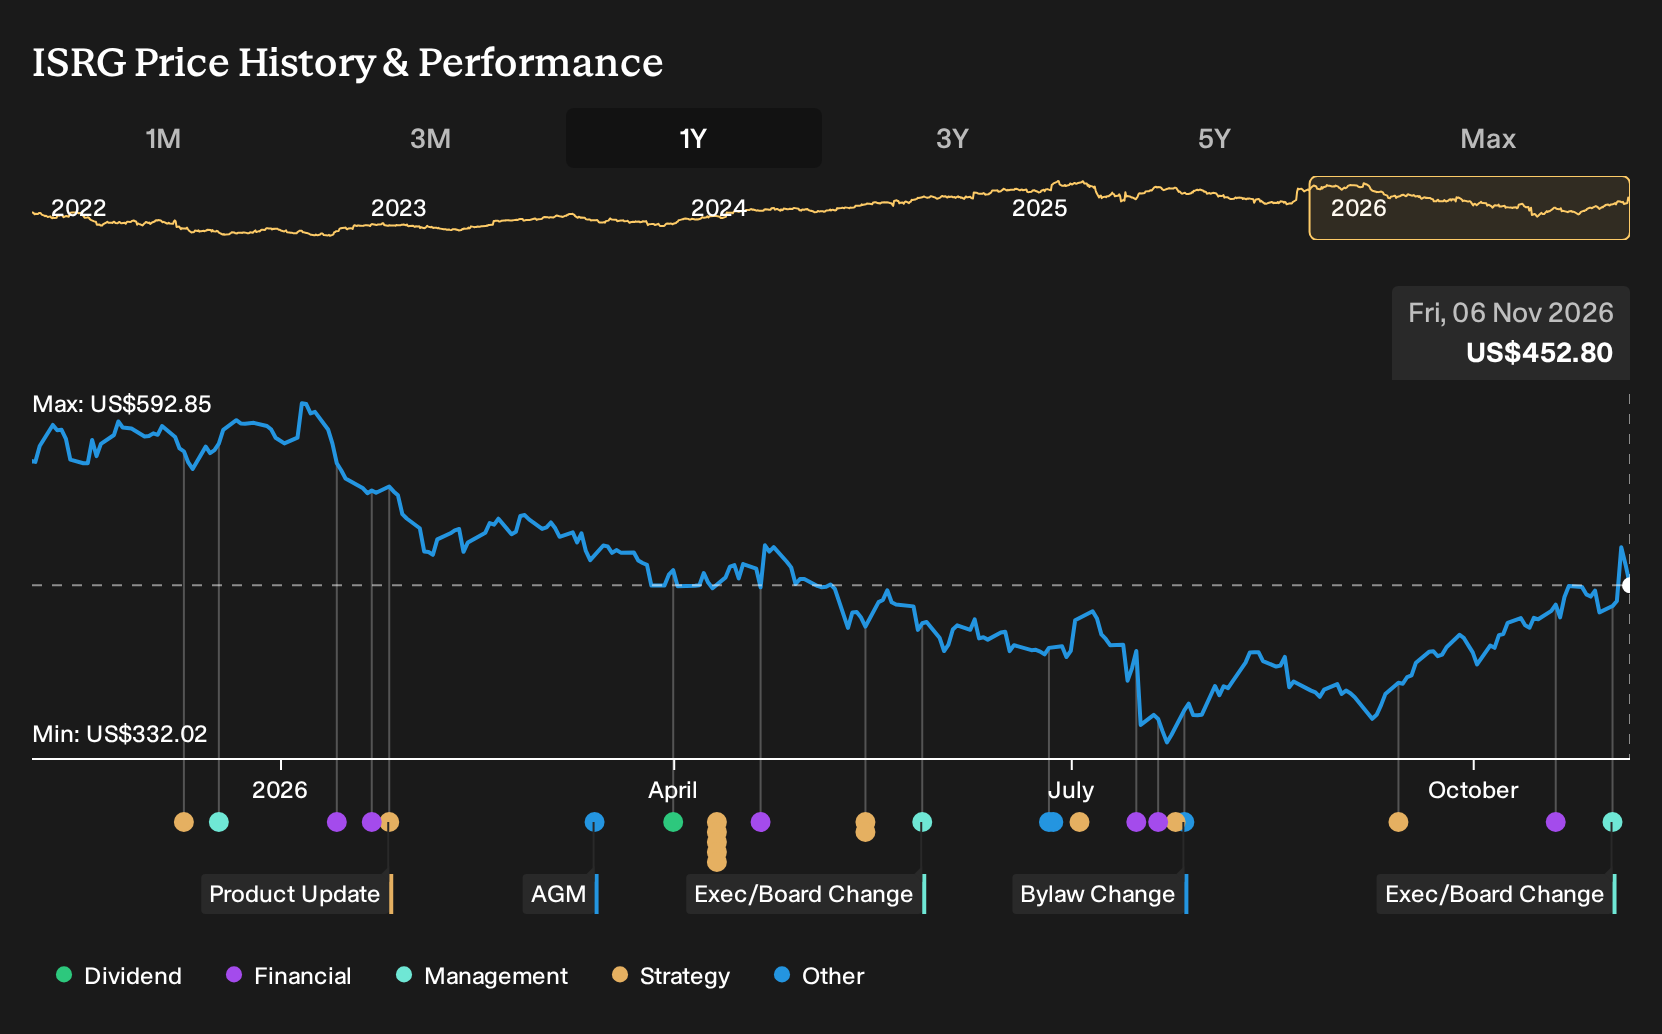
Consensus targets then roll these building blocks into a headline price objective of US$476.34 per share. Compared with the quoted US$393.33 level in the report, that target sits 17.4% higher, although forecast dispersion is wide, with bearish analysts at US$324 and bullish estimates up at US$685. For investors tracking Intuitive Surgical, the practical question is whether an 11.9% growth trajectory, US$15.5b in sales, US$4.8b in earnings and a 43.5x P/E in 2029 feel reasonable given the competitive, regulatory and hospital budget pressures already visible today.
Uncover why Intuitive Surgical's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view puts Intuitive Surgical’s digital tools at the center of the story. Some analysts were already modeling about US$17.4b of revenue and US$5.1b of earnings by 2029, with a 53.7x P/E, on the idea that MI+ subscriptions and software turn the ecosystem into a higher margin “operating system.” Aaron Martin’s telehealth and data background could push that debate further in either direction, so treat this board change as a cue to compare several narratives rather than rely on a single forecast.
Explore 8 other Intuitive Surgical fair value estimates, including one that suggests as much as 39% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Intuitive Surgical research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Intuitive Surgical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Intuitive Surgical's overall financial health at a glance.
Looking For More Ideas Beyond Intuitive Surgical?
If you want to balance your view on Intuitive Surgical with opportunities in other areas of the market, the Simply Wall St Screener can help you quickly filter for businesses that fit your risk level, income needs and return goals.
- If capital preservation comes first for you, start with companies that score well on stability and financial resilience through the 29 resilient stocks with low risk scores.
- For readers hunting for quality at a reasonable price, focus on established businesses that still look attractively priced using the 39 high quality undervalued stocks.
- Those looking to get in early on under-followed opportunities can scan for strong fundamentals in lesser known stocks through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com