


- Labcorp Holdings reported third quarter 2026 sales of US$3,810 million and net income of US$262.8 million, with both basic and diluted EPS from continuing operations higher than a year earlier. The company also provided nine month figures showing higher sales and earnings compared with the prior period.
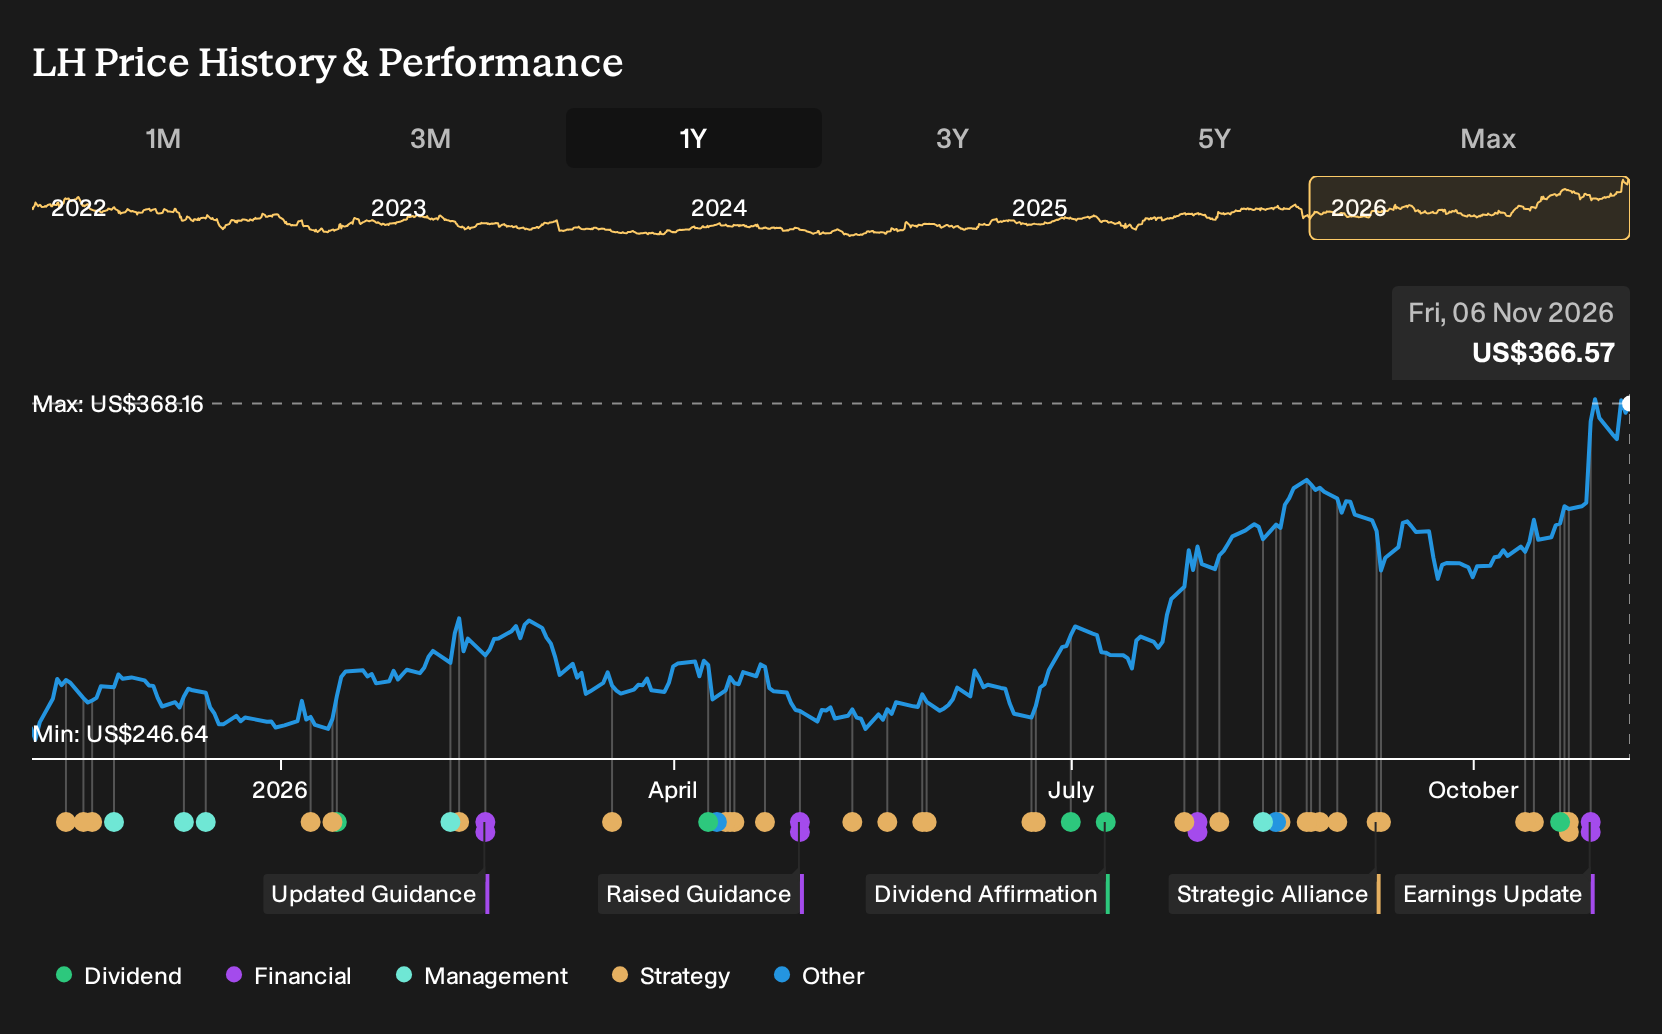
- The company raised its 2026 full year revenue growth guidance to a range of 5.9% to 6.7%. This reflects management’s stated view of current testing demand, productivity efforts and the biopharma services pipeline at Labcorp Holdings.
- We will now assess how Labcorp Holdings’ raised full year revenue growth guidance may reshape the existing investment narrative around the business.
Scan beyond Labcorp Holdings and see how other healthcare and diagnostics stocks with solid fundamentals stack up using our hand picked list of solid balance sheet and fundamentals (24 results)
Labcorp Holdings Investment Narrative Recap
To own Labcorp Holdings, you need to be comfortable with a story built around steady test volumes, higher value specialty diagnostics and long duration biopharma lab contracts. The raised 2026 revenue growth guidance to 5.9% to 6.7% points to management seeing enough demand and internal efficiency to support its current operating plans.
The key short term swing factor remains execution on productivity and mix shift, so that higher volumes and AI or automation savings offset reimbursement pressure and PAMA risk. The main concern still sits with potential US$100 million PAMA impacts on both revenue and operating income, which the latest results do not remove.
The most relevant update for that thesis is the third quarter and nine month 2026 earnings report. Sales reached US$3,810 million for the quarter and US$11,078.7 million for the nine months, while net income came in at US$262.8 million and US$839.3 million respectively, with higher basic and diluted EPS from continuing operations in both periods versus a year earlier.
Those figures give you a current snapshot of how Labcorp Holdings is handling reimbursement headwinds, higher debt and its investment in technology and acquisitions. They also frame the raised revenue outlook, since sustained mid single digit top line progress and EPS growth can help fund further AI and automation projects and support the diagnostics and biopharma services catalysts already in motion.
Labcorp Holdings' current analyst framework points to revenues of US$16.8b and earnings of US$1.4b by 2029. This outlook is built on an assumed 4.7% yearly revenue growth rate and an earnings increase of about US$400m from US$1.0b today.
Uncover why Labcorp Holdings' fair value indicates a 3% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
Two fair value submissions from the Simply Wall St Community span roughly US$355 to US$979 per share, which shows how far opinions on Labcorp Holdings can stretch. Before the latest earnings and guidance raise, some members were already baking in strong specialty testing, AI driven productivity and the biopharma backlog, while others flagged PAMA cuts as a potential drag. That gap in expectations is wide, so it makes sense to review several of these viewpoints yourself.
Explore another Labcorp Holdings fair value estimate, including one that suggests it could be worth just $354.50.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Labcorp Holdings research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Labcorp Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Labcorp Holdings' overall financial health at a glance.
Looking for more Labcorp Holdings sized investment ideas?
If the Labcorp Holdings story has sharpened your thinking, use that same lens to hunt for other opportunities that better match your risk tolerance, time horizon and income needs.
- For investors focused on quality at a reasonable entry point, review 39 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into the price.
- If resilience matters most to you, scan through 29 resilient stocks with low risk scores that score well on financial strength and business stability.
- For those looking to back companies early in their journey, sift through 9 elite penny stocks with strong financials that still pair smaller market caps with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com