


Kennametal has seen its share price fall to US$23.00 after a tough spell, and that slide puts a spotlight on a simple question for investors who focus on cash flows. Is the current valuation supported by what the business is expected to generate in hard cash over time, or is the market pricing in something different from its underlying economics?
- The stock has declined 32.7% over the past 5 years, which puts long term cash flow prospects at the center of the discussion around what this move really means.
- Recent updates on stronger Metal Cutting volumes, improved pricing and an ambition to sustain a 16% to 19% adjusted EBITDA margin suggest future cash generation can matter more than near term share price swings for anyone assessing value.
- What if you looked at Kennametal through its earnings instead? See what Kennametal's 3.0x P/E says about the price.
The issue now is whether the cash flows implied by a Discounted Cash Flow (DCF) view line up with where Kennametal shares change hands today.
If you are weighing Kennametal on its cash flows after this share price slide, it can help to compare it with other companies screened for 39 high quality undervalued stocks
Does Kennametal Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) approach values Kennametal based on the cash it could return to shareholders over time, adjusted back to today. Recent figures show the business reported a free cash flow loss of $322.5 million over the latest twelve months, followed by projections that swing to positive territory with analyst estimates and modelled cash flows in the coming years. That shift implies the DCF hinges on a recovery profile rather than a steady state, with free cash flow expected to normalise and then ease into slower growth.
The projections used here assume Kennametal’s cash generation improves from current levels and then tapers, which fits a company that already has meaningful scale rather than one chasing hypergrowth. Because stronger Metal Cutting volumes and record EPS in fiscal 2027 are already in the rear-view mirror, the model effectively asks whether those conditions can feed into durable free cash flow instead of just earnings optics. Despite that fiscal 2027 update, the DCF output in this analysis indicates an estimated intrinsic value above the current share price of $23.00. Find out what Kennametal could be worth using our Discounted Cash Flow (DCF) estimate.
The Kennametal Narrative: What Would Justify Today's Price?
Narratives pick up where the DCF question on Kennametal leaves off by spelling out which specific paths for growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than today’s price on Simply Wall St’s Community page. Each one ties a fair value to a single, coherent story about Kennametal’s potential catalysts and key risks, so you can track over time which version of events is actually unfolding.
One of the top community narratives on Kennametal: 29% undervalued
"The company is actively rightsizing capacity and executing structural cost reductions including plant closures and workforce optimization..."
Discover why this Narrative puts Kennametal at 29% undervalued.
Kennametal's valuation still leaves one more puzzle to solve
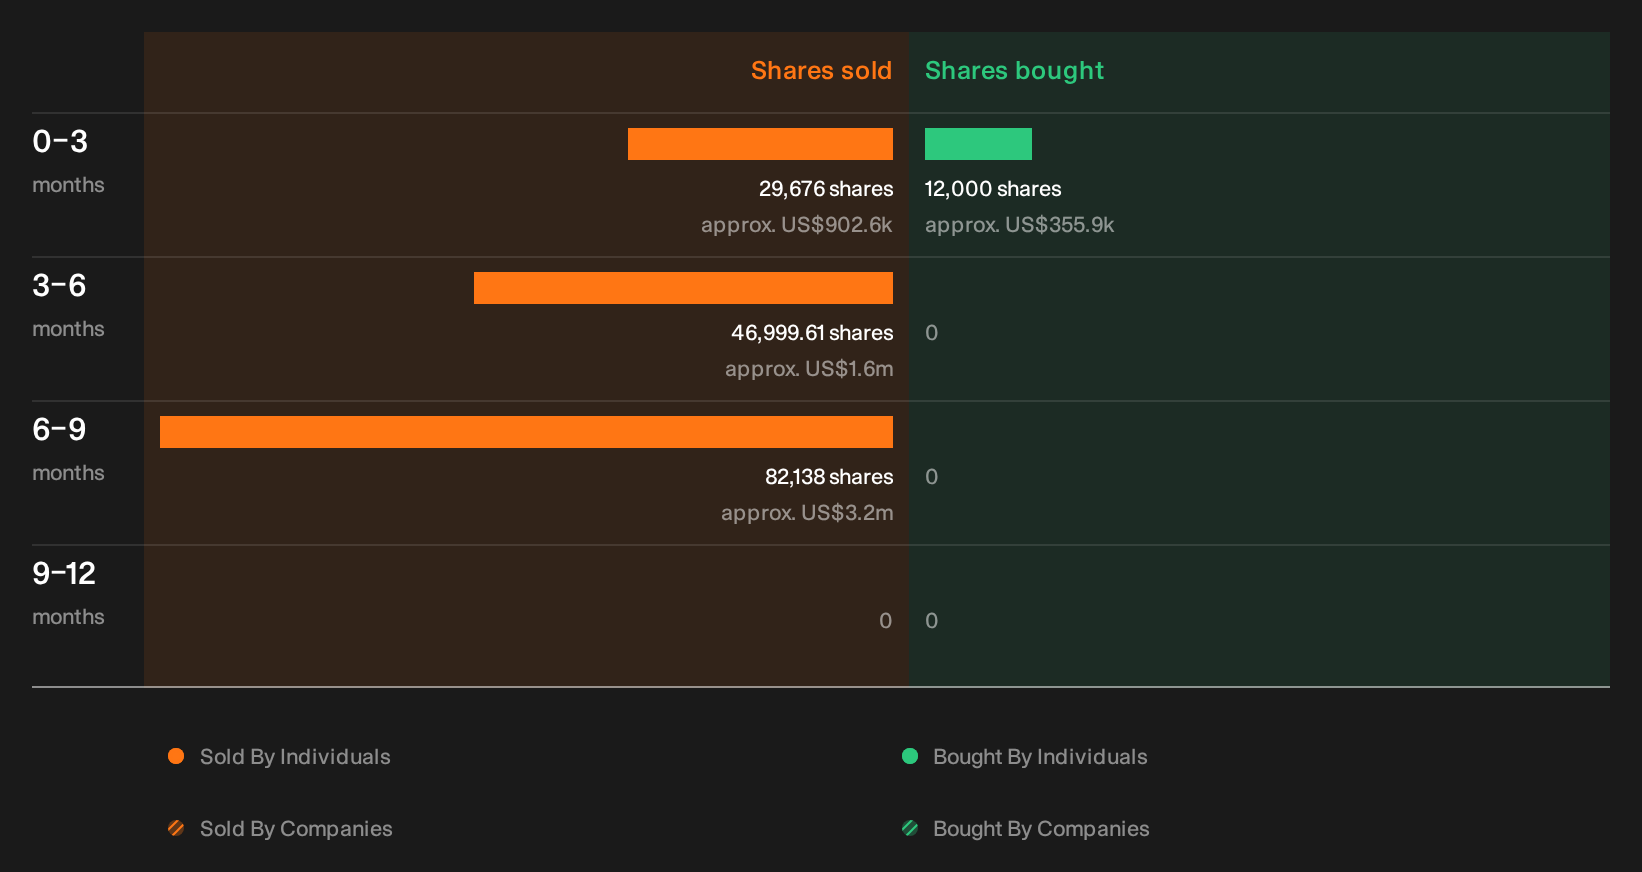
Price and cash flow only tell part of the story for Kennametal, because recent insider share sales flagged by our checks raise a separate question about behaviour inside the boardroom that deserves a closer look. See the recent insider selling flagged for Kennametal.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com