


SL Green Realty (SLG) has been drawing attention after recent price moves, with the stock last closing at $50.78. Investors are weighing that level against the REIT’s reported loss of $145.171 million.
Recent trading paints a mixed picture for SL Green Realty, with a 30 day share price return of 4.49% but a 90 day share price decline of 9.9%. The year to date share price gain of 8.13% and 3 year total shareholder return of 91.24% suggest that longer term holders have seen stronger momentum than shorter term traders.
Scan beyond SL Green Realty by comparing it with a curated 39 high quality undervalued stocks list that currently shows stronger balance sheets and cash flows on Simply Wall St.
After a short term rebound yet a recent quarterly loss of $145.171 million still on the books, SL Green Realty now sits in a grey zone. Is this a fair entry today, or is it worth waiting for a cheaper tag before stepping in?
Most Popular Narrative: 9% Undervalued
At a last close of $50.78 versus a narrative fair value of $55.65, SL Green Realty is framed as modestly undervalued, with that gap hinging on how its Manhattan footprint and fee platforms play out over time.
The scarcity of new Midtown office deliveries, combined with office to residential conversions such as 750 Third Avenue, is expected to keep high quality space tight, which can support higher effective rents and same store NOI growth for SL Green Realty over time.
Broad based Manhattan leasing from finance, tech, AI and other tenants, with 2026 deals already lifting leased occupancy to 95% and rent mark to market around 15% to 16%, positions SL Green Realty to roll remaining below market leases at higher rates and support future revenue and earnings.
See why 25 investors see SL Green Realty as 9% undervalued.
Result: Fair Value of $55.65 (UNDERVALUED)
Still, the SL Green Realty story can break if interest costs stay elevated and asset sales slip, or if Manhattan office demand weakens again.
Find out about the key risks to this SL Green Realty narrative.
Another View On SL Green Realty’s Valuation
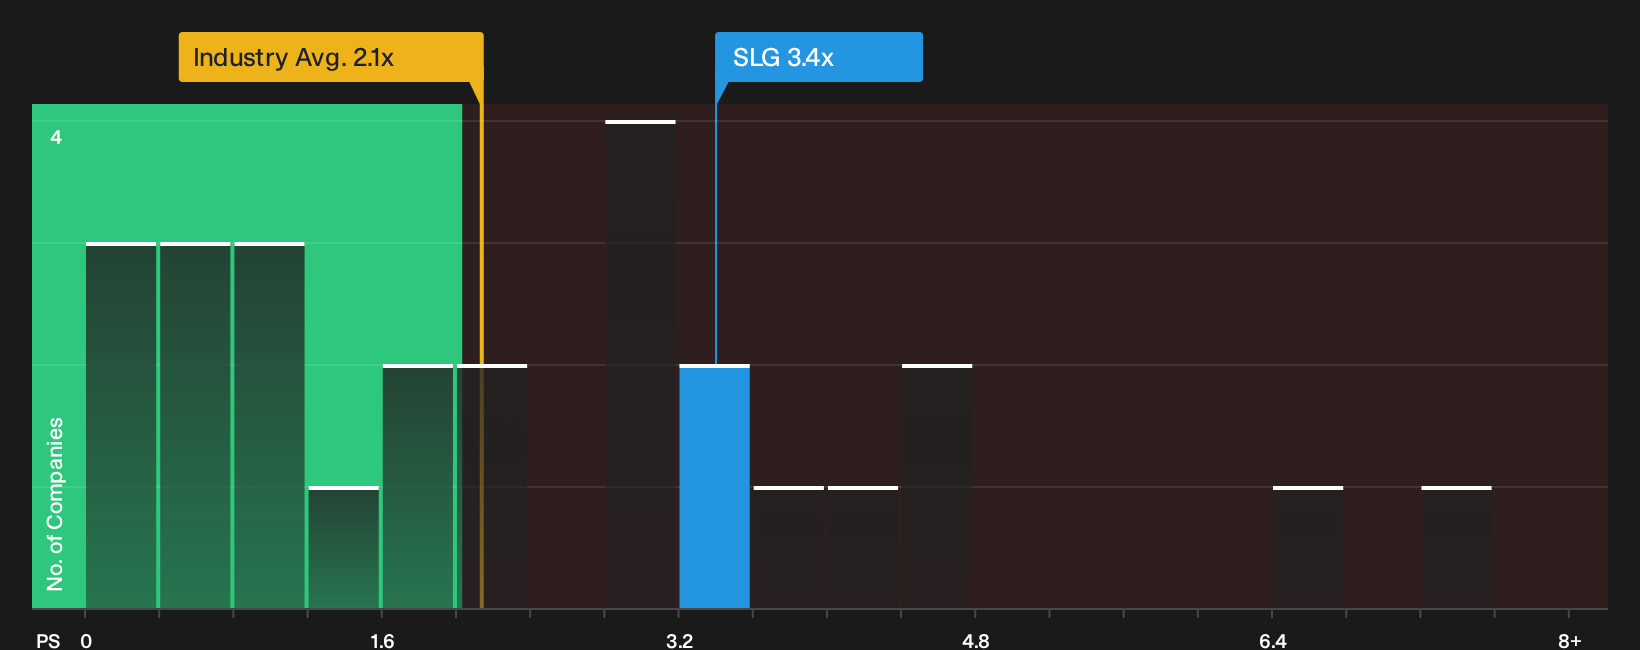
The DCF work paints one picture. On simple sales multiples, SL Green Realty looks less generous. The stock trades on a P/S of 3.4x versus 2.1x for the US Office REITs group and a fair ratio of 2.7x, which points to valuation risk if sentiment swings back toward sector norms.
Our DCF model reaches a different conclusion, which is why some investors treat it as a cross check rather than a verdict, and use the details as a way to test their own assumptions against the market price today See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around SL Green Realty can feel confusing, so move quickly to inspect the underlying numbers, weigh the moving parts, and then judge the balance between risks and upside through 1 key reward and 3 important warning signs.
Hunting For More Ideas Beyond SL Green Realty?
Do not stop with SL Green Realty. Broaden your watchlist with fresh ideas pulled from focused screeners that highlight different angles of quality and potential.
- Target resilience first and filter for stability by scanning a curated pool of 29 resilient stocks with low risk scores that historically carry lower overall risk scores.
- Pursue quality at a reasonable price and see which companies currently screen as 39 high quality undervalued stocks based on stronger fundamentals and attractive valuations.
- Strengthen your core holdings and focus on balance sheets that can absorb shocks by reviewing a list of solid balance sheet and fundamentals (24 results) before others catch on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com