


Rapport Therapeutics (RAPP) drew fresh attention after reporting statistically significant efficacy in its Phase 2 RAP-219 trial for acute bipolar mania, while pairing that update with a Q3 outlook indicating its cash runway extends through 2029.
That clinical update landed after a tough stretch for Rapport Therapeutics’ stock, with a 90 day share price return that fell 46.27% and a 30 day move down 20.80%, while the 1 year total shareholder return declined a more modest 4.75%. This pattern suggests that recent losses may reflect shifting sentiment on risk rather than a long running collapse.
Scan how Rapport Therapeutics compares to other high-conviction ideas in CNS and healthcare by reviewing our curated list of 19 high quality undiscovered gems with strong underlying fundamentals.
With Rapport Therapeutics sliding hard even as RAP-219 cleared a key Phase 2 bar and the balance sheet points to funding through 2029, are investors already paid for the good news, or is meaningful upside still on the table as the valuation stacks up next?
Most Popular Narrative: 65% Undervalued
Rapport Therapeutics closed at $24.44 compared with a widely followed fair value estimate of $69.06, so the market is pricing in a steep discount even after the recent Phase 2 bipolar mania readout.
The current valuation implies that the market assigns meaningful value to RAP-219 in epilepsy and some credit to lifecycle and pipeline options, yet still treats the bipolar mania indication and long acting injectable extension as higher risk and as underappreciated drivers for the share price.
See why 1 investors see Rapport Therapeutics as 65% undervalued.
Result: Fair Value of $69.06 (UNDERVALUED)
Still, if RAP-219 fails to repeat its bipolar mania or epilepsy profile in larger studies, or if losses persist longer than expected, the Rapport Therapeutics narrative could quickly reset.
Find out about the key risks to this Rapport Therapeutics narrative.
Another View: Rapport Therapeutics Looks Expensive On P/B
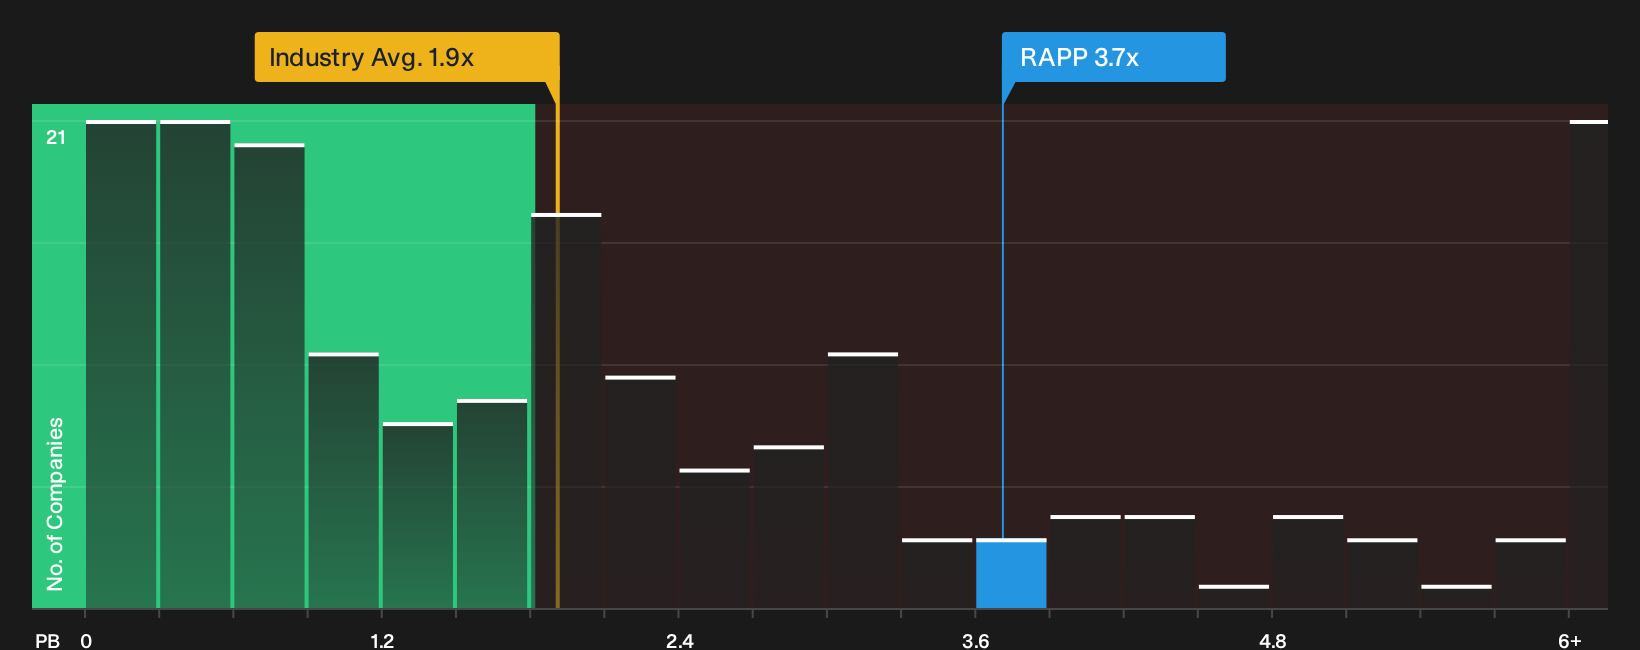
On analyst fair value, Rapport Therapeutics screens as materially undervalued. On price to book, the picture flips. RAPP trades at a P/B of 3.7x versus 1.8x for the broader US Pharmaceuticals group and sits well below a peer average of 19.1x, which points to less extreme enthusiasm than some close comparables but a clear premium to the wider sector that could matter if sentiment cools or clinical data disappoints. Which signal do you trust more when the story is this dependent on a single asset?
For a closer look at how this valuation premium fits with the rest of the numbers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Rapport Therapeutics is clearly split, which is exactly when independent work matters most. Act quickly, pull up the data, and shape your own view with the 1 key reward and 4 important warning signs
Looking for more investment ideas beyond Rapport Therapeutics?
If you only stop at Rapport Therapeutics, you risk missing other opportunities that fit your style just as well, or even better, across the market.
- Target potential mispricings by scanning a 39 high quality undervalued stocks that already filters for quality alongside attractive valuations.
- Build staying power into your portfolio by using a list of solid balance sheet and fundamentals (24 results) that focuses on resilient finances when conditions get tougher.
- Dial down portfolio stress by reviewing a 29 resilient stocks with low risk scores that highlights businesses with more measured risk profiles before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com