


Inflation worries are creeping back into corporate earnings calls, and higher interest rate expectations are back on the table. That combination puts dependable cash payouts in the spotlight. Reliable dividend income can soften the impact when share prices swing and borrowing costs squeeze household budgets. This article looks at three high-yield companies with dividends above 3% that screens suggest are better covered, more stable, and growing.
The three stocks highlighted here offer a compelling starting point if you want exposure to higher-yield dividend payers with an emphasis on coverage, growth, and stability. However, if you want the strongest names, these 8 dividend aristocrats stocks are the top of the list.
Chevron (CVX)
Chevron is a heavyweight in the Dividend Powerhouses theme because its large upstream oil and gas fields and global refining network generate the cash that funds its payout, giving income investors a link to real world energy flows rather than purely financial engineering.
Chevron operates integrated energy and chemicals businesses that explore for and produce oil and gas, then refine, transport, and market fuels, LNG, petrochemicals, and renewables across multiple continents. The group has a market value of about US$415.5b.
Record production growth, especially in the Permian and from the Hess acquisition in areas such as Guyana and the Bakken, now sits on top of capital and drilling programs that aim to keep Permian volumes around 1 million barrels per day with lower CapEx per barrel. This supports future revenue and free cash flow.
What really matters next is how one evolving cost pressure shapes the gap between Chevron’s cash generation and the dividend cheque you are relying on.
To see how that pressure could reshape Chevron’s cash cushion versus its payout, read the full narrative for Chevron for the full picture of what might be accelerating or stalling ahead.

NIKE (NKE)
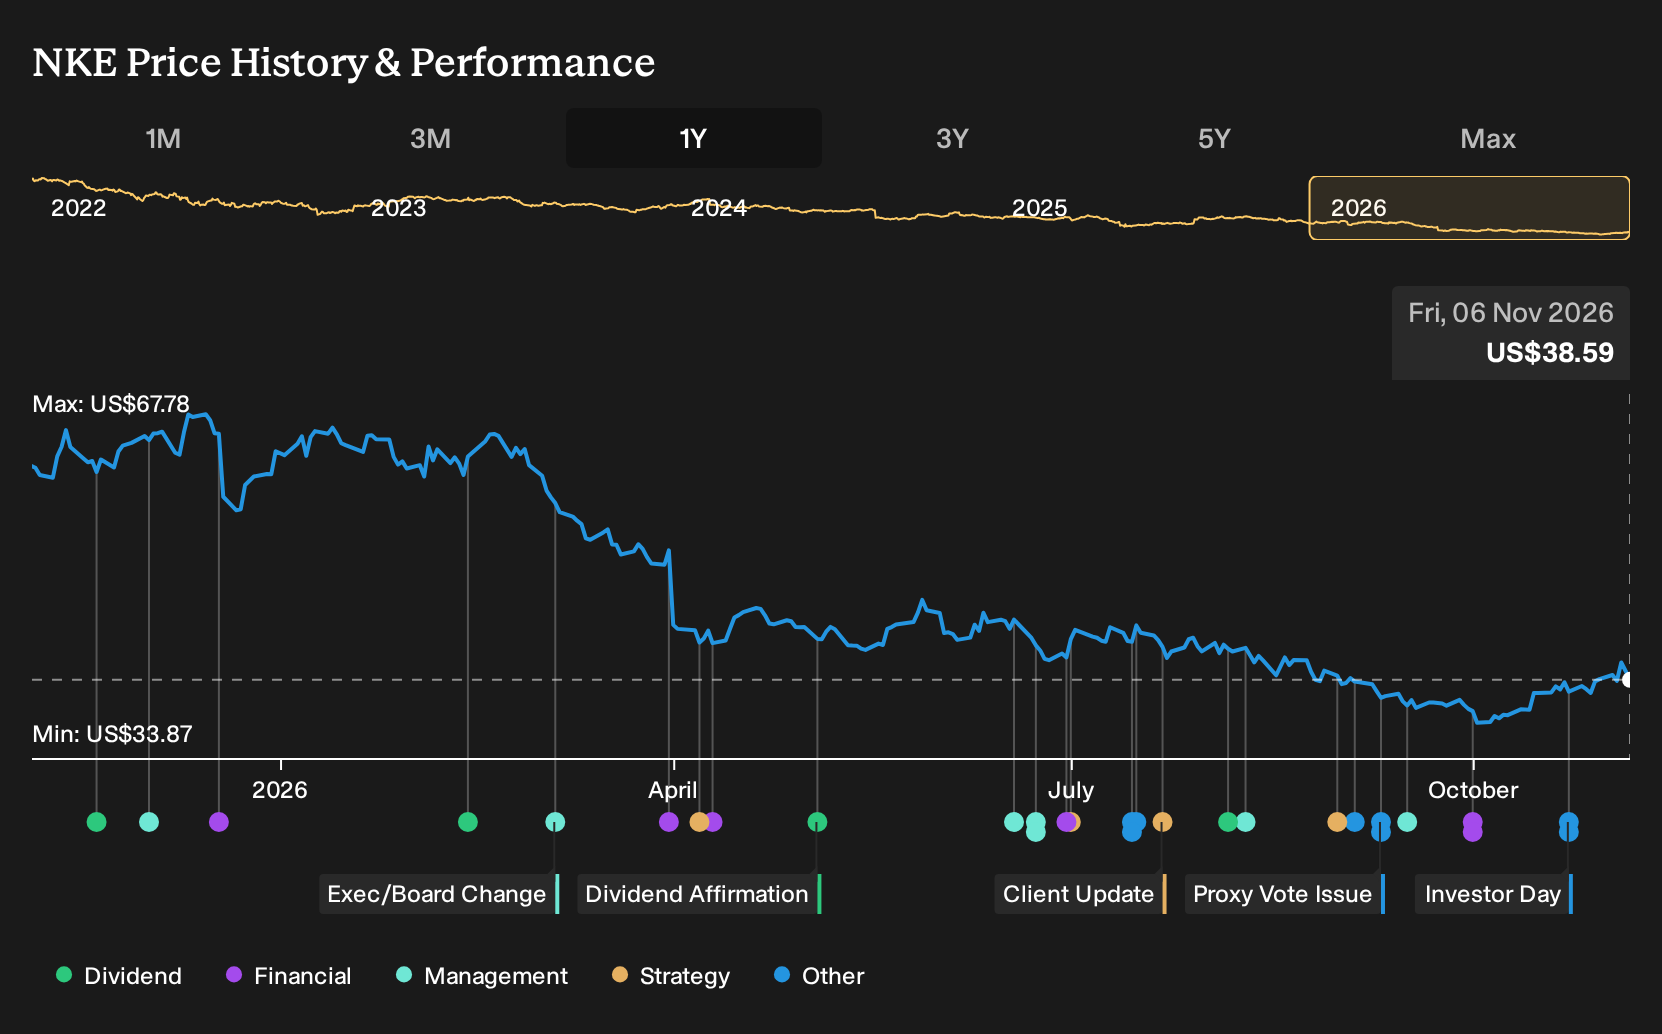
NIKE is a global sportswear giant whose steady free cash flow from trainers, apparel, and digital direct sales helps fund a 3%+ dividend that this screener targets, with most revenue still anchored in the core NIKE brand across major regions worldwide.
NIKE generates most of its sales from the NIKE brand in North America at about US$20.6b, followed by Europe, Middle East and Africa at roughly US$12.4b, Asia Pacific and Latin America at about US$6.2b, Greater China at around US$5.5b, and Converse at roughly US$1.1b, and the group carries a market value near US$58.8b.
For income investors, NIKE offers a rare mix of global consumer reach, digital direct-to-consumer momentum, and a dividend backed by substantial recurring cash flow, but the next phase of the turnaround will determine how secure that payout feels.
"The November 2026 investor day is the deciding event. It will show whether management's targets support the recovery case or the conservative one."
What eventually happens to that dividend and its coverage still hinges on how one unresolved pressure on future earnings power is resolved.
That hinge point makes it worth reading the full narrative for NIKE to see how the reset could accelerate NIKE’s recovery story and reshape the income case.
DICK'S Sporting Goods (DKS)
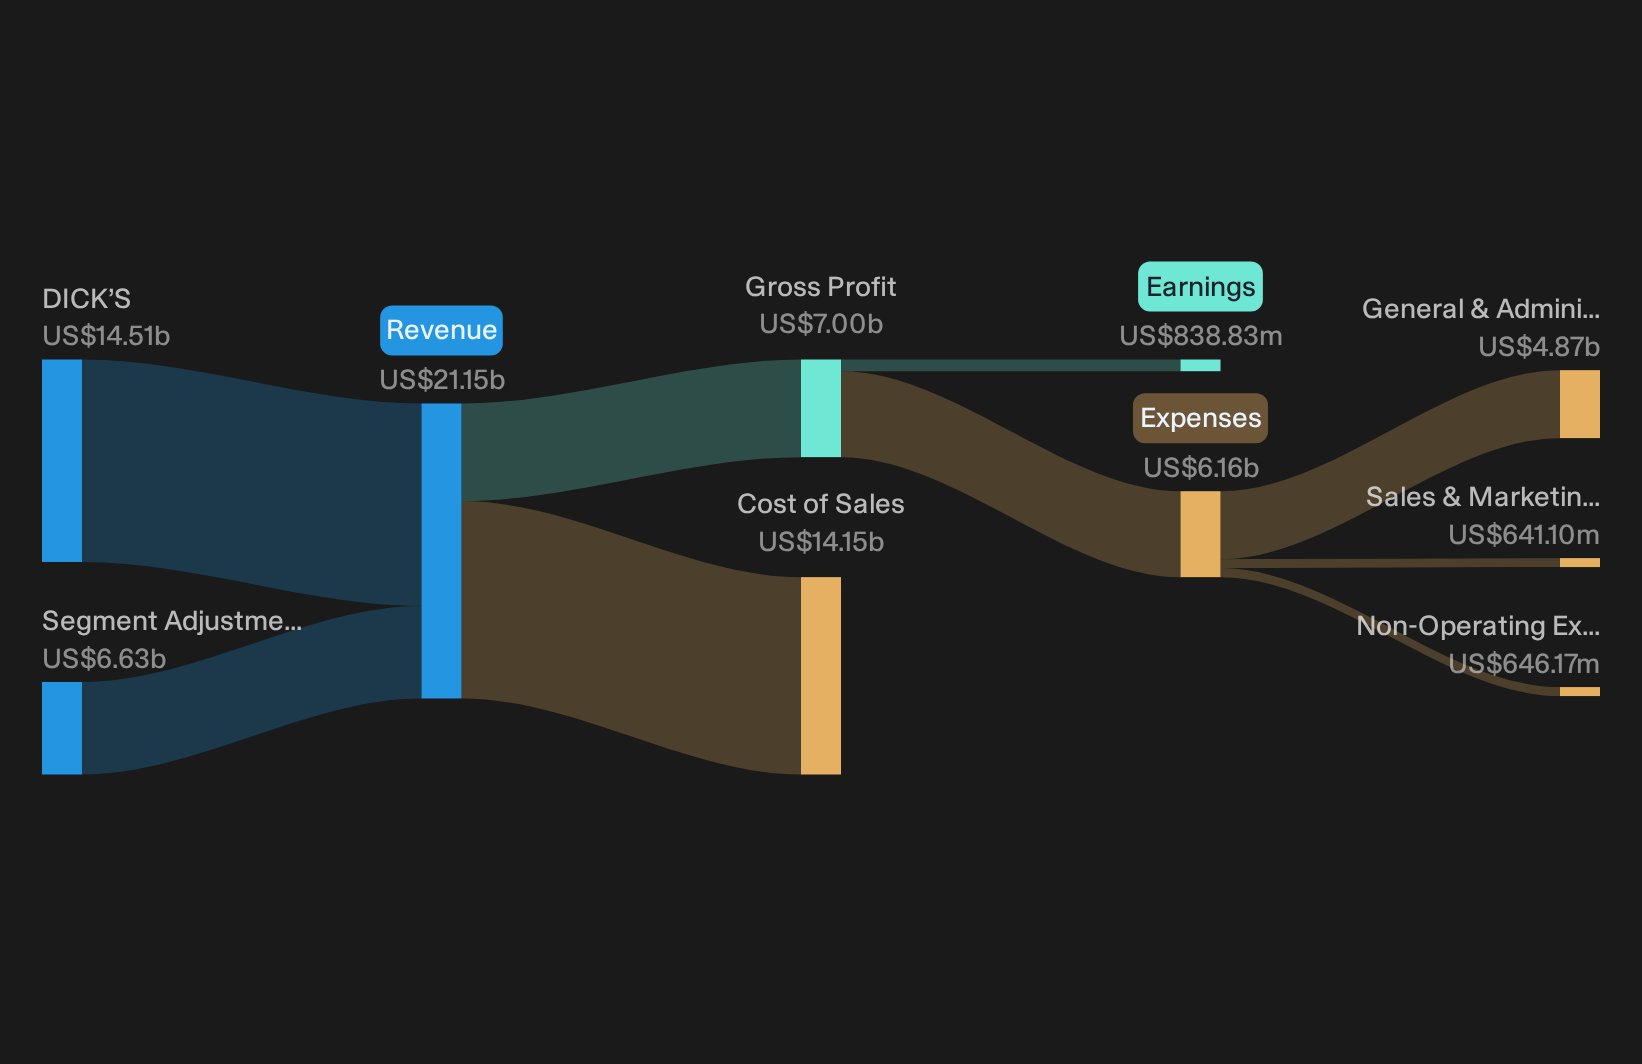
DICK'S Sporting Goods runs an omni channel sporting goods chain that sells athletic footwear, apparel and equipment, which helps fuel steady, cash driven earnings to support its higher yield dividend. Almost all revenue, about US$14.5b, comes from the DICK’S segment, and the retailer has a market value near US$12.5b.
DICK'S Sporting Goods ties into the Dividend Powerhouses theme through a mix of everyday sports spending and multi banner retail, giving its payout a base in recurring store and online cash flows while the newer banners and acquired footwear chains work through their own cycles.
"The Foot Locker "inflection point" has been deferred, full-year Foot Locker pro forma comp guidance moved from +1.5% to 3% growth to -2% to flat, and operating income shifted from a profit of $110M to $150M to a loss of $40M to $80M."
What ultimately happens to dividend cover now rests on how one pressure on cash conversion and funding costs resolves over the next stretch.
That funding question is exactly why the full narrative for DICK'S Sporting Goods examines whether DICK'S Sporting Goods is experiencing an earnings reset or has an underappreciated cash engine accelerating beneath the surface.
Seeking Alternatives Before Momentum Flies
Fresh ideas often move first. Breakout stories, dropping laggards, under the radar for now. Screens update, sentiment shifts, and potential edges can change while you wait. Consider acting promptly where appropriate.
- Identify early movers in smaller, cash-backed opportunities by scanning the 9 elite penny stocks with strong financials before momentum may be more fully reflected in prices and some entry points potentially become less accessible.
- Monitor future-facing infrastructure ideas using the 52 AI infrastructure stocks while demand develops and many investors remain focused on prominent technology names.
- Review potential supply constraints by using the 16 top copper producer stocks while these producers receive less attention and prices may not yet fully reflect all available information.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com