


- Upbound Group reported third quarter 2026 revenue of US$1.15b and net income of US$34.27 million, with adjusted EPS of US$1.01 and free cash flow of about US$121 million, alongside a new US$50 million share repurchase authorization and lower net leverage of 2.4x after debt repayment.
- The mix of stronger profitability, higher cash generation and debt reduction suggests Upbound Group is leaning on cash discipline rather than top line expansion. This may matter for investors tracking the balance between growth initiatives and returns of capital.
- We will now look at how Upbound Group's stronger free cash flow and leverage improvement could reshape the existing investment narrative.
Scan how Upbound Group’s cash focused quarter compares with other companies that are prioritizing balance sheets and fundamentals by reviewing our curated list of solid balance sheet and fundamentals (24 results).
Upbound Group Investment Narrative Recap
To own Upbound Group, you need to be comfortable with a story that leans on tighter underwriting, disciplined cash use and a non prime customer base that still feels cost of living pressure. The latest quarter fits that lens, with revenue softer but net income, EPS and free cash flow all stronger, and leverage a bit lower.
The near term swing factor is whether Acima and Rent A Center can hold credit quality and cash generation if consumer demand for big ticket items stays muted. The biggest risk remains pressure on lower income customers, alongside the ongoing CFPB related legal overhang. The recent earnings beat does not materially change that backdrop.
The guidance update on 29 October looks most relevant to frame this quarter. Management now expects fourth quarter 2026 consolidated revenue of US$1.15b to US$1.25b and has narrowed full year expectations to US$4.68b to US$4.78b. That guidance ties directly into how you think about the sustainability of the recent free cash flow strength.
For you as a shareholder, that range helps anchor what the next leg of the story depends on. Execution around Acima’s credit products, Brigit’s financial health tools and Rent A Center’s store optimization sits against that revenue corridor, while risks such as Acima’s prior GMV softness and the lawsuit against the CFPB remain key watchpoints.
Analysts' current narrative for Upbound Group points to revenue of US$5.2b and earnings of US$311.3 million by 2029, which lines up with an assumed 3.1% yearly top line growth rate and an earnings increase of about US$221 million from roughly US$90.3 million today.
Uncover why Upbound Group's fair value indicates a 17% potential upside to its current price that may not last much longer.
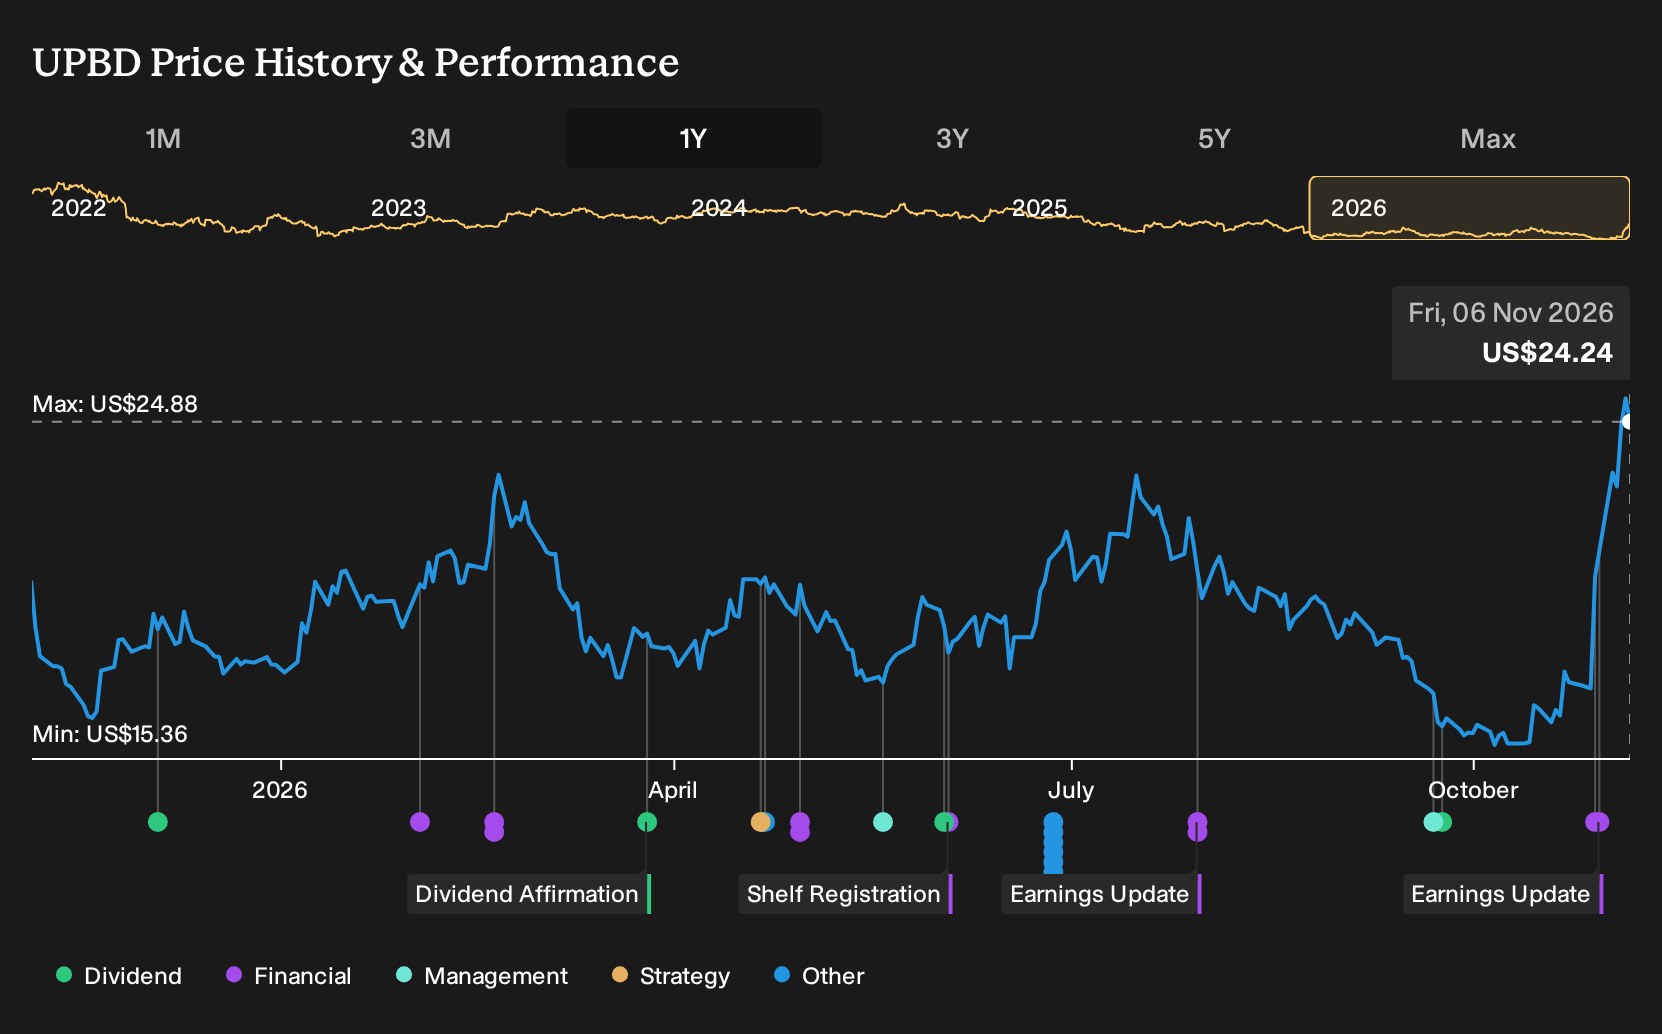
Exploring Other Perspectives
Not every analyst focuses on Brigit as the main swing factor. Some of the most optimistic voices frame Upbound Group around rising free cash flow and the path toward their US$5.4b revenue and US$382.7 million earnings forecasts for 2029. Those projections came before this quarter, so you might see opinions shift. Use that spread in expectations to pressure test your own view.
Explore 2 other Upbound Group fair value estimates, including one that suggests as much as 182% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Upbound Group research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Upbound Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Upbound Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Upbound Group?
Once you have a view on Upbound Group, it can help to cross check that thinking against a broader watchlist of companies with different risk and income profiles. The Simply Wall St Screener lets you quickly filter for businesses that match the kind of balance sheet strength, income potential or upside you are looking for.
- If capital preservation is your first filter, start by scanning a 29 resilient stocks with low risk scores that score well on resilience and risk controls.
- For investors hunting for mispriced quality, compare Upbound Group with a curated 39 high quality undervalued stocks that combine solid fundamentals with potential upside.
- If you want ideas that sit off the usual radar, look through a focused 19 high quality undiscovered gems that pair healthy financials with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com