


Q3 earnings put Distribution Solutions Group in focus
Distribution Solutions Group (DSGR) moved into the spotlight after reporting third quarter 2026 results, with sales of US$573.62 million and net income of US$8.89 million from continuing operations.
Investors also received an update on the nine month period to September 30, 2026, as the business shared cumulative sales of US$1.63b and net income of US$17.77 million over that timeframe.
Recent trading has been steady rather than explosive, with the share price roughly flat over the past month while news flow has centered on the Q3 earnings release and the appointment of a Chief Transformation Officer. Even with those muted short term moves, Distribution Solutions Group has produced a 24.57% year to date share price return and a 33.58% one year total shareholder return. This suggests earlier momentum has been stronger than the latest few weeks imply.
Compare Distribution Solutions Group's latest move with a curated list of other industrial players showing strong fundamentals and potential re rating in our 39 high quality undervalued stocks.
For Distribution Solutions Group, a flat month after a strong year raises a simple question. Are investors cooling on the story while the business keeps grinding, or has sentiment merely paused now that valuation has reached its current level?
Most Popular Narrative: 20% Undervalued
On the most followed view of Distribution Solutions Group, the fair value sits at $35.00 versus a last close of $34.93, with that small gap hinging on how effectively management turns acquisitions and mix shift into sustained earnings.
Ongoing build out of Distribution Solutions Group’s specialty distribution platform through nearly US$450 million of acquisitions since 2022, along with planned tuck ins in Canada, Europe, Asia-Pacific, Mexico and South Florida, is expected to broaden the customer base and product reach, which can support revenue growth and operating leverage.
See why 0 investors see Distribution Solutions Group as 0% undervalued.
Result: Fair Value of $35 (UNDERVALUED)
Still, the narrative frays quickly if acquisition integrations drag on or if Lawson’s sales transformation keeps adding cost without lifting organic demand.
Find out about the key risks to this Distribution Solutions Group narrative.
Another View on Distribution Solutions Group's Valuation
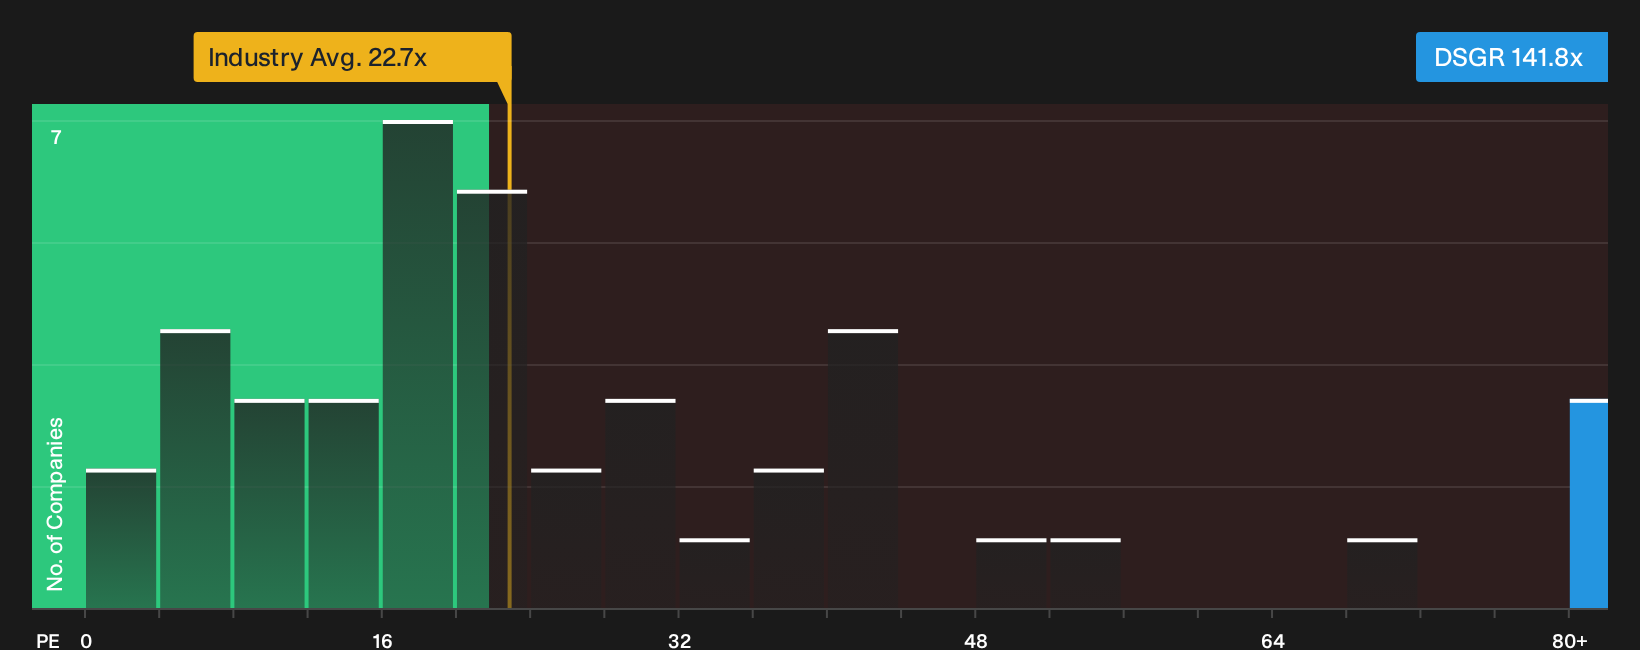
That 20% undervalued story leans on future cash flows and analyst forecasts. Swap the lens to current earnings and the picture changes. Distribution Solutions Group trades on a P/E of 141.8x versus 22.5x for the US Trade Distributors industry, a 31.9x peer average and a 115.8x fair ratio, which implies meaningful valuation risk if expectations cool.
Put simply, today’s earnings multiple leaves less margin for error than the discounted cash flow output suggests. Which signal do you trust more for your own process: the cash flow model or the earnings comparison?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Distribution Solutions Group is mixed, with both caution and optimism in the air, so move quickly to study the numbers, weigh the trade offs, and decide where you stand by reviewing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Distribution Solutions Group?
If Distribution Solutions Group has your attention, do not stop there. Broaden your watchlist with other clear ideas that could sharpen your overall portfolio decisions.
- Target stability first and stress test your portfolio against market shocks by running results through the 29 resilient stocks with low risk scores.
- Hunt for quality at a reasonable price and see which companies combine strong fundamentals with more appealing entry points using the 39 high quality undervalued stocks.
- Build your income stream more deliberately and scan for payout opportunities that match your risk tolerance with the 8 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com