


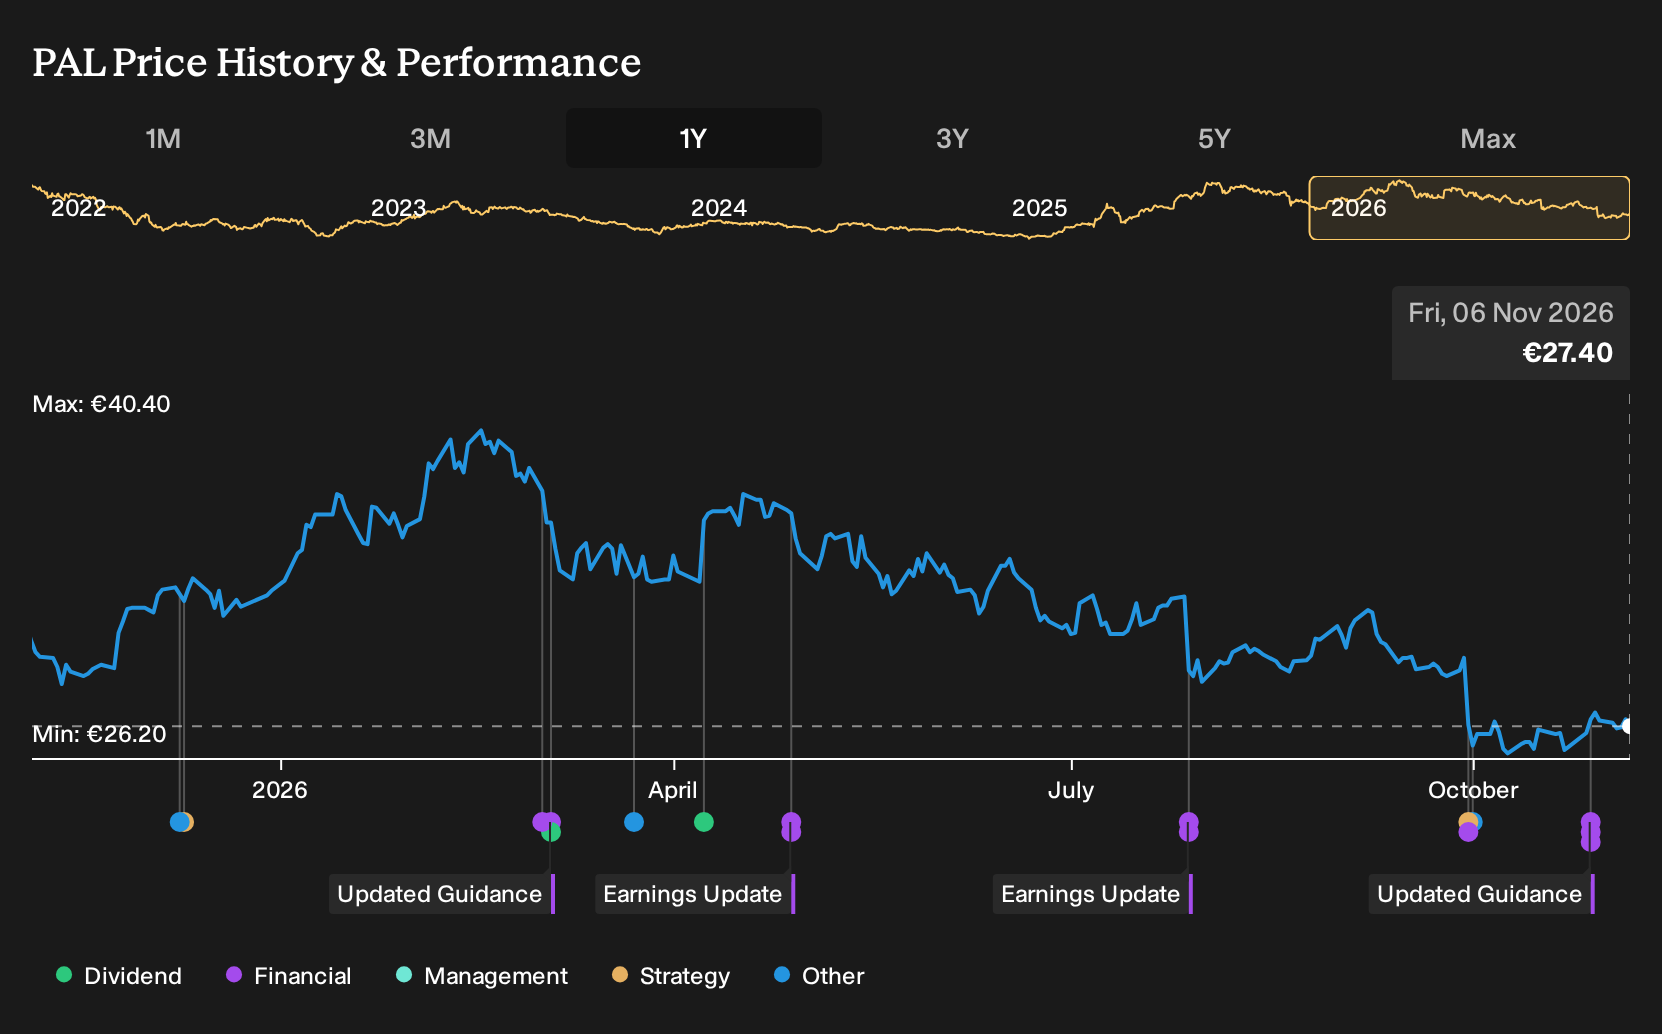
- Palfinger updated its 2026 guidance, indicating revenue slightly above and EBIT slightly below the prior year. The nine-month figures to September 2026 showed €1,616.67 million in sales and a move from net income to a net loss of €61.55 million, due mainly to non cash write offs in CIS and Tail Lifts.
- The board plans to propose a dividend despite the reported loss. This highlights how non cash revaluations can weaken earnings without reducing operating cash generation.
- The next focus will be on how Palfinger's investment narrative absorbs a 2026 profit dip driven by CIS and Tail Lifts write offs.
Contrast Palfinger's guidance and non cash write offs with other industrials by scanning our hand picked list of solid balance sheet and fundamentals (193 results) for potentially steadier balance sheet profiles.
Palfinger Investment Narrative Recap
Palfinger appeals most if you believe its lifting solutions, service activities and Marine exposure can absorb one off setbacks and still support its long term plan. The 2026 guidance signals a year where revenue edges above the prior period but EBIT sits slightly lower, with reported earnings shaped heavily by CIS and Tail Lifts write offs rather than day to day operations.
The immediate swing factor is execution on existing orders and the Reach Higher Strategy 2030+ capital projects, while demand in key regions remains patchy. The sharp move from net income to a €61.55 million loss spotlights accounting pressure as the key short term risk, while underlying activity and cash generation become the elements to watch.
The adjusted 2030 revenue target of €2.8b gives a clear reference point for anyone tracking Palfinger after this guidance update. Management kept the long term EBIT margin objective of 12% and ROCE of 15% unchanged, so the company is signalling that portfolio pruning in CIS and Tail Lifts should not alter its broader ambition for profitability on the remaining base.
For catalysts, the key link is how this long range target sits against current headwinds from trade measures, weaker demand in some markets and the loss of Russian and Tail Lifts turnover. Progress toward the €2.8b goal will depend on North American market share efforts, Marine backlog conversion and service mix expansion, while higher debt levels and an unstable dividend history remain on investors’ risk checklist.
Palfinger Consensus Forecasts In Context
Palfinger's narrative projects €2.7b revenue and €161.7 million earnings by 2029. Analysts are assuming revenue will grow by 4.7% per year, with earnings rising by about €67.1 million from €94.6 million today to reach that 2029 consensus level.
Uncover how Palfinger's fair value indicates a 51% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
You can read the new guidance as a reality check, yet the most optimistic analysts still frame Palfinger around a different catalyst. They focus on large infrastructure programs and were pencilling in about €2.8b revenue and €200.2 million earnings by 2029. Those forecasts came before this update, so opinions may shift and investors are likely to explore a range of views.
Explore 4 other Palfinger fair value estimates, including one that suggests potential upside of up to 59% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view based on careful research.
- A great starting point for your Palfinger research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Palfinger. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Palfinger's overall financial health at a glance.
Looking For More Ideas Beyond Palfinger?
If Palfinger has put capital allocation and balance sheet quality on your radar, you might want to widen the net and compare it with other businesses that match your own risk and return preferences. The Simply Wall St Screener can help you quickly surface stocks that fit very different profiles, from income focused to higher risk, higher potential situations.
- If you want to focus on value combined with quality fundamentals, scan a curated group of companies through the 224 high quality undervalued stocks.
- For investors who care most about income resilience, filter for payout strength and balance sheet support using the 232 dividend fortresses.
- If capital preservation matters to you before anything else, narrow the field to businesses with sturdier profiles across key risk checks via the 212 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com